Tag: MiFID II

  • Kaizen RegTalk 2026

    Kaizen RegTalk 2026

    Kaizen RegTalk 2026, our flagship conference for the regulatory reporting community, returns on Tuesday 2 June at Drapers’ Hall, London.

    We are pleased to welcome back Tom Soden from the Financial Conduct Authority (FCA) as our keynote speaker, alongside specialists from across the industry, including firms, trade associations and Kaizen’s regulatory experts.

    The regulatory landscape is entering a new period of transition, with significant changes proposed across UK and EU regimes.  As these changes develop, firms will face increased scrutiny on the accuracy and quality of their reported data.

    This year’s event will bring the industry together to share practical insights, examine what the changes mean for firms, and explore what comes next.

    Join us to:

    • Hear directly from the FCA
    • Gain practical insight into UK and EU regulatory developments
    • Prepare for upcoming changes to UK MiFIR Transaction Reporting
    • Explore how firms are strengthening reporting quality and controls
    • Connect with peers across the regulatory reporting community
    • Experience the next evolution of the Kaizen Hub platform, including enhancements available now and a preview of what’s to come.

    View the Kaizen Regtalk 2025 highlights in the video at the top of the page.

    Places are limited to clients and invited guests but if you would like to attend, please email your interest to communications@kaizenreporting.com and we will do our best to accommodate you.

  • WATCH: The Regulatory Reporting Landscape in 2026

    WATCH: The Regulatory Reporting Landscape in 2026

    Why watch?

    As regulatory reporting enters a new phase in 2026, firms are navigating potential changes to reporting data alongside increased regulatory scrutiny. The session provides regulatory reporting and compliance professionals with the insights needed to align their 2026/27 reporting with regulatory expectations.

    ● Audit-ready insights: Understand the areas regulators are likely to target this year.

    ● Multi-jurisdictional updates: A one-stop briefing on MiFIR Transaction Reporting, EMIR, ASIC, MAS, HKMA and North American developments.

    ● Money Markets in focus: How to prepare for heightened transparency in short-term liquidity reporting.

    ● Expert Q&A: Get direct answers to your most pressing reporting challenges directly from Kaizen’s subject matter experts.

    Speakers:

  • INTC or not INTC? FCA expectations for aggregate client accounts under MiFIR Transaction Reporting

    INTC or not INTC? FCA expectations for aggregate client accounts under MiFIR Transaction Reporting

    One MiFIR transaction reporting convention that continues to trip firms up is the aggregate client account: INTC. In this blog, we take a deep dive into how INTC is supposed to work and why regulators keep coming back to it.

    INTC isn’t obscure. It’s everywhere:

    • 108 references in ESMA reporting examples
    • a clear legal basis in RTS 22
    • detailed direction in the ESMA Guidelines
    • repeated warnings in FCA Market Watch 62 and 70, and 
    • extensive coverage again in the FCA’s discussion and consultation papers.

    So why does it still go wrong so often?

    The legal foundation for INTC: RTS 22

    RTS 22, Article 11 is clear about the objective of INTC: to enable effective market monitoring, transaction reports must include exact information on any change in position of the investment firm or its client at the time the transaction took place. Firms must therefore report related fields consistently, and report different legs of a transaction such that their reports, collectively, provide a clear overall picture that accurately reflects changes in position.

    INTC is one of the conventions that allows firms to meet this objective, but only when used exactly as intended. ESMA fills in the “how” in the Guidelines.

    What INTC actually is (and isn’t) under MiFIR

    The ESMA guidelines define INTC clearly: the aggregate client account (INTC) is a reporting convention used to provide a link between the market side and client side of transactions.

    It therefore:

    • is not “real”
    • does not represent ownership
    • does not indicate internal position-taking
    • must never introduce a net position.

    When a firm aggregates multiple client orders and executes them in the market, INTC provides the bridge that allows a regulator to connect the market execution and the allocations to the underlying clients.

    That bridge must be temporary. Any movement through INTC must net to zero within the same business day.

    When INTC may be used in transaction reporting

    When reporting with INTC, there must always be:

    • a market-side transaction(s) into or out of INTC, and
    • corresponding client-side transactions out of or into INTC

    The ESMA guidelines are unambiguous: INTC should only be used in the circumstances set out in the guidelines. It shouldn’t be used for:

    • an order for one client executed in a single execution, or
    • an order for one client executed in multiple executions.

    And where there is a transfer into INTC, there must be a corresponding transfer out within the same business day, so the aggregate client account is flat.

    FCA Market Watch: repeated warnings

    The FCA has been flagging misuse for years. In Market Watch 62, the FCA highlighted firms:

    • using INTC for single-client orders, and
    • reporting flows that did not net off on the same business day.

    In Market Watch 70, three years later, the same issues remained:

    • one client, multiple fills reported via INTC
    • INTC used to signal an internal trading account, and
    • missing the market-side or client-side leg altogether.

    The underlying message is consistent: INTC is not a convenience field. It is a controlled linking convention.

    The scale of the problem: FCA policy papers

    The recent FCA discussion and consultation papers add numbers to what had previously been more of a supervisory narrative.

    The regulator’s analysis shows

    • one in five firms had INTC imbalances
    • seven per cent of all INTC reports contributed directly to those imbalances.

    Across the most recent full year of FCA analysis (2023):

    • 342 million reports used INTC
    • 447 firms used INTC.

    The FCA considered whether to introduce more precise linkage mechanisms between market and client side. The direction of travel in the consultation is to rule that out because implementation costs would outweigh benefits and increasing complexity could worsen data quality.

    In other words: the regulator is not planning to redesign INTC for firms but it does expect firms to use it properly.

    Why the FCA cares so much about INTC

    INTC errors are not cosmetic. When INTC does not net to zero – or is used incorrectly – the consequences are material:

    • regulators see phantom positions
    • ownership appears to pass through firms incorrectly
    • market abuse surveillance becomes distorted
    • aggregation logic breaks down.

    In short: market reconstruction fails.

    What firms should be doing now

    For MiFIR firms, the message is clear. The regulator has acknowledged that structural change may not be beneficial which means it will expect higher accuracy within the existing framework.

    1. Re-validate your INTC logic:
    • is INTC used only for genuine aggregation across multiple clients?
    • does it net to zero by instrument, per day?
    • do your reporting scenarios adhere to the guidelines?

    2. Expect supervisory scrutiny:

    • the FCA is clearly focusing on INTC
    • guidance will be reviewed, but the existing expectations already apply
    • less complexity in the regime means the regulator will expect greater precision, not less.

    Four simple letters – ‘INTC’ – have an outsized impact. Getting it right is one of the simplest ways to materially improve transaction reporting quality – and one of the easiest ways to stand out for the wrong reasons if you don’t. 

    While you are driving home for Christmas or taking your chance on the trains, worrying that you’ll be getting a FCA letter about INTC, please get in touch. Our award-winning ReportShield quality assurance highlights any issues you may have with INTC and once you know you have a problem, you can put it right before the FCA gets in touch.

  • Key changes proposed by FCA on MiFIR Transaction Reporting

    Key changes proposed by FCA on MiFIR Transaction Reporting

    The FCA’s CP 25/32 has landed and at nearly 200 pages, its full impact will take some time to digest. We were all expecting proposals to tune the obligation to suit the UK market, as well as steps to improve data quality and a reduction in the reporting burden on firms. And that is what it has delivered.

    But I think it is fair to say that the consultation proposes a more sweeping modernisation of the UK’s transaction reporting framework than was expected. A full read confirms that the proposed reform marks the most significant overhaul since transaction reporting was introduced.

    Here is a short summary and we’ll be taking a deeper dive over the coming weeks to fully grasp the finer details:

    1. Fewer reporting fields, leaner data requirements

    One of the headline changes is the reduction of transaction reporting data fields from 65 down to 52. This streamlining is designed to remove low-value data while maintaining the information needed to detect market abuse. The FCA is also proposing a reduction of instrument reference data fields from 48 to 37, alongside the removal of the obligation for systematic internalisers (SIs) to submit instrument reference data.

    2. Smaller instrument universe

    Another major shift is the removal of circa six million financial instruments – those only tradeable on EU venues – from the UK’s reporting scope. This re-scoping is expected to significantly shrink the volume of daily reports while aligning the UK regime more closely with the structure of domestic markets.

    3. FX derivatives out, shorter back-reporting period

    The consultation also proposes to eliminate FX derivatives from transaction reporting entirely, removing a category that currently generates high reporting volumes but low regulatory value. In addition, the FCA plans to shorten the back-reporting window from five years to three years, reducing the long-tail workload of historical corrections.

    4. Smarter reporting through conditional single-sided logic

    The true impact of the above proposal is unclear at this stage but the expansion of conditional single-sided reporting will be welcomed by some. It is not as extensive as the much loved portfolio manager’s exemption but it should have a beneficial impact on some firms.

    We are looking forward to participating in the debate with our clients and trade associations over the coming months. Please look out for a more detailed summary shortly!  

    For a conversation with Matthew or one of our regulatory experts about the FCA’s proposals, please get in touch.

  • When the clocks go back – don’t (or maybe do) let your timestamps fall behind!

    When the clocks go back – don’t (or maybe do) let your timestamps fall behind!

    In the early hours of Sunday 26 October, clocks across the UK and much of mainland Europe will go back one hour. For most of us, that means an extra hour in bed. For those working in trade and transaction reporting, it can also mean an extra opportunity for time-related errors to impact reported data accuracy.

    Under UK and EU MiFIR and EMIR, all reportable time fields must be expressed in Coordinated Universal Time (UTC). This consistency makes it easier for regulators to monitor trading activity across jurisdictions and identify potential instances of market abuse. As we have noted before, the FCA clearly used the transaction data to analyse two successful market abuse cases this year. 

    With the clock change approaching, now is a good time to double-check your reporting systems, times received on execution messages and the many hidden locations where +/- offsets may still be applied.

    Despite how long this requirement has been in place, we continue to see firms struggle with daylight saving. We have onboarded several clients this year, who – after receiving regulatory inquiries about incorrect trade times – have commissioned us to review their wider reporting accuracy. 

    At Kaizen, our ReportShield quality assurance helps firms detect and correct time-based inconsistencies. Because whether you spring forward or fall back, as well all know accurate timing is essential to accurate reporting. 

    Get in touch for a demo or a conversation on how we can get your reporting into better shape.

  • FCA’s Market Watch 82: Key actions for firms on remediation

    FCA’s Market Watch 82: Key actions for firms on remediation

    Following on from Market Watch 81 where the FCA assessed the root causes of transaction reporting quality issues, Market Watch 82 focuses on the process firms are expected to engage with once errors are identified.

    All reporting firms should have robust procedures in place to identify, address and disclose regulatory reporting issues. Many will be actively engaged in the process. The findings detailed within Market Watch 82 stem from the FCA’s recent observations supervising the UK MiFID transaction reporting regime and focus on observed inefficiencies within the processes firms have in place.

    The Market Watch is in two halves – the first looks at remediation processes, and the second reviews remediation notifications. 

    We’ve distilled the newsletter into key actionable items that all firms must/might/should consider now if they haven’t already. 

    Remediation process

    • Document and agree a prioritisation methodology against which all “issues” are assessed
    • Remediate accordingly to the agreed prioritisation (the FCA makes it clear that under-reporting takes priority over misreporting a field where the supervisory priority has been downgraded)
    • Remediate the root cause first, then back report
    • Accurately identify all impacted records
    • Due care and diligence ensures repetition, missed records and unnecessary deadline extension requests are avoided
    • Determine and action a remediation plan to fix all impacted records within a realistic timeline
    • Ringfence resources to remediation – remediation is never done well “off the side of the desk”. A focused effort by regulatory subject matter experts will likely get the job done more efficiently than relying on individuals with other priorities
    • Make regulatory reporting and data migration a key sign off for all change projects be it new business, infrastructure or regulatory reporting driven change
    • Regular data quality testing will confirm that issues are no longer occurring once fixed and it is equally important to make sure that new issues aren’t introduced or worse, previous ones reoccur.

    Remediation notifications

    • Clearly state whether the issue is misreporting, under-reporting, or late reporting. Make sure you describe it in plain language, avoid internal jargon and keep it to the point 
    • Align your root cause analysis with the common causes from Market Watch 81. If citing human error, you should assess whether better processes, controls, or oversight could have prevented it
    • If exact impact details aren’t available, submit the notification without delay. Make this clear and provide estimated figures if needed. Indicate when the full assessment will be completed and specify whether volumes are exact or approximate
    • Give details about the planned remediation – if this is work in progress then detail the activity required to determine back-reporting timelines rather than give no details. Even the best teachers can’t mark blanks  
    • Clearly link the issue to its specific root cause, focusing on the actual weakness in systems or controls. Avoid generic statements about overall improvements. If including a third party, assess whether better vendor controls or oversight could have prevented the problem.

    As we were all reminded during the football over the weekend, a draw after two halves leads to penalties, and the FCA reminds us that “some firms must improve their operational frameworks”. A look back to the Final Notice issued by the FCA earlier this year reminds us that the firm in question was chastised for not only for accuracy errors but also for delayed regulatory notification and weaknesses in controls. 

    Our ReportShield services are used by hundreds of firms to address the issues raised by the FCA in Market Watch 81 and 82. For help with your remediation programme, a review of your controls or a comprehensive assessment of your data quality using our market-leading tools, please get in touch. 

  • Delegated Reporting: The Danger of ‘Out Of Sight, Out of Mind’ reporting

    Delegated Reporting: The Danger of ‘Out Of Sight, Out of Mind’ reporting

    At Kaizen, we see firsthand how widespread delegated reporting has become across the UK and EU financial services industry. It was one of the main panel topics at our recent Kaizen RegTalk conference where I was joined by Alpha FMC’s Bernardo Castel-Branco, Regis TR’s Nick Bruce and Fredrik Karlsson from SEB. The conversation was facilitated by ISDA’s Andrew Bayley.

    Delegated reporting is effective in enabling firms, especially the buy-side, to simplify their reporting operations. However while you can delegate the physical act of reporting, you cannot delegate the legal liability. As we frequently discuss with our clients and at the events we hold, the belief that ‘out of sight is out of mind’ is a dangerous misconception.

    The central challenge: oversight without duplication

    Under EMIR and SFTR, there are specific scenarios where delegated reporting is mandatory. But voluntary delegated reporting is also common in whole or in part for certain market segments. During the panel, we shared an example from agency securities lending, where asset management firms often completely outsource security settlement, custody, collateral management, lending, and reporting. In some cases, their first awareness of any reporting issue comes from a regulator inquiry, not their own internal checks.

    This is the key problem with delegated reporting: it can reduce operational burden, but it doesn’t reduce liability. The challenge is to ensure you have oversight and the right controls in place without rebuilding the whole reporting function that you were trying to outsource in the first place. 

    Common mistakes we see in delegated reporting

    Our panel shared four mistakes that they see frequently across the industry:

    • Treating it as free: The “zero cost add-on” model – where reporting is offered free alongside other services like custody is common but often causes problems. Limited resources go to delegated reporting because it is viewed as non-commercial, so service quality suffers and controls can be found lacking.
    • Managing issues at the wrong level: Errors and omissions are often managed at the omnibus account level across all clients rather than tackled on a firm-by-firm basis. This prevents firms receiving firm-level regulatory oversight from the delegated reporter and being able to communicate issues and remediation plans with the regulator. When problems arise, firms often can’t establish the materiality or set realistic timelines for resolution.
    • Weak agreements: Standard agreements are typically written to limit delegate liability rather than ensure service quality, which doesn’t help the delegating firm to enforce standards with the delegate or meet their regulatory obligations.
    • Missing the required data: Firms often lack access to underlying data from books and records, trade repositories and approved reporting mechanisms (ARMs) needed for proper oversight. If you can’t independently verify what’s being reported on your behalf, you’re taking an unnecessary risk.

    Best practices for effective oversight

    At Kaizen RegTalk we asked our audience of more than 200 clients what was the most important aspect of successful delegated reporting. 

    1. Shared understanding (38% of poll respondents said this was crucial): This requires ongoing dialogue between delegating firm and delegate. You can’t assume your delegate understands your business requirements, you need to actively manage this relationship. In practice, this means building your control framework with systems that let you monitor delegate performance without recreating the entire reporting function.
    2. Strong, independent controls (36%): The delegating firm must maintain the ability to independently verify the quality of their reporting. This includes reconciliation and access to trade repository data for basic checks. You also need ways to assess what’s important, and documentation showing queries raised and responses received.
    3. Clear communication (17%): Regular updates and processes to resolve disputes are critical. When issues arise, you need defined escalation paths and service level agreements for resolution. The panel emphasised keeping delegated reporters “under pressure” through regular challenging to show that you’re actively engaged and expect high standards.
    4. Well-defined roles (9%): Both parties need to understand exactly what’s expected and when. You also need the ability to terminate the relationship and report directly if the service quality deteriorates. The FCA’s approach allows flexibility in materiality judgments. Firms must exercise best judgment about what’s material for regulatory purposes versus what’s material for their business.

    Looking Ahead

    The panel highlighted several challenges they are seeing more often, including:

    • Resource conflicts between commercial priorities and delegated reporting quality
    • Cross-border complexity creating operational headaches for teams
    • Fragmented technology and incomplete datasets mean reconciliation tools are struggling to piece together trade flows and reporting requirements to validate reports.

    Most importantly, the panel was concerned that knowledge retention* is becoming an issue as teams move between projects or are outsourced or offshored.

    What was the panel’s conclusion?

    Delegated reporting can work, but only with active oversight. The “out of sight, out of mind” approach simply doesn’t work.

    You can delegate the reporting, but you can’t delegate the liability. If done right, it reduces operational burden while maintaining standards but done wrong, it creates dangerous blind spots that regulators will likely find.

    • For help in establishing effective control and oversight of your delegated reporting, please get in touch. 
    • Find out more about how our SFTR Daily Controls can support your delegated reporting.
    • *Our Single Rulebook tool helps teams collaborate on regulation to create a single company view and trace decision-making across your organisation.
  • Kaizen Appoints Michael Leach as Chief Revenue Officer

    Kaizen Appoints Michael Leach as Chief Revenue Officer

    London, 24 June 2025 — Kaizen, a leading provider of regulatory compliance solutions for global financial institutions, today announced the appointment of Michael Leach as Chief Revenue Officer (CRO). Leach brings extensive experience from his tenure at London Stock Exchange Group (LSEG), where he played a pivotal role in building UnaVista (now LSEG Regulatory Reporting Solutions) into a global brand.

    As one of the original founders of UnaVista, Leach has known Kaizen since its inception and has extensive knowledge of the regulatory reporting industry. Most recently serving as Global Sales and Regulatory Reporting Business Development Group Director at LSEG, he has demonstrated proven expertise in building successful sales teams and expanding market reach on a global scale.

    In his new role as CRO, Leach will oversee Kaizen’s sales strategy, business development initiatives, and revenue operations, with a focus on driving revenue growth and supporting the company’s market expansion objectives.

    Michael Leach, Chief Revenue Officer at Kaizen commented: “I’m excited to join the Kaizen team and contribute to the company’s continued growth. I’ve seen firsthand the value and innovation the company brings to the regulatory reporting and compliance space. I look forward to working with the talented team here to accelerate our market presence and deliver exceptional value to our clients.”

    Dario Crispini, CEO of Kaizen, said: “We are thrilled to welcome Mike to our executive team. His extensive background at LSEG, combined with his deep understanding of our industry and proven track record in building successful sales organisations, makes him the ideal leader to drive our revenue growth strategy. Mike’s leadership and industry expertise will be instrumental in helping us achieve our ambitious growth and market expansion goals.”

    Leach’s appointment comes as Kaizen continues expand its market presence in the regulatory compliance sector.

    (ends)

    For more information, please contact Fiona Wilde, Head of Marketing and Communications, at media@kaizenreporting.com

  • WATCH: Highlights of Kaizen RegTalk 2025

    WATCH: Highlights of Kaizen RegTalk 2025

    We’re thrilled to share the highlights of Kaizen RegTalk, our annual event for our client community, which took place on Tuesday 10 June at Merchant Taylor’s Hall, London. 

    More than 200 clients, partners and industry specialists joined us for an afternoon of networking, insights and best practices on regulatory reporting, with speakers from the FCA, Bank of England, ISDA, Regis-TR, FIA and many client firms. 

    Tom Soden, Manager, Markets Reporting Team at the FCA gave the keynote address.

    Key topics for the afternoon included the MiFIR Review, EMIR Refit lessons learned, delegated reporting best practices, and the growing role of AI.

    Once again, a huge thank you to all our speakers and panellists, and of course to our valued community of clients who make events like this possible.

  • ESMA’s Data Quality Report 2024: MiFiR transaction reporting remains a key focus

    ESMA’s Data Quality Report 2024: MiFiR transaction reporting remains a key focus

    ESMA’s fifth report on data quality (published 30th April) – like last year’s – seemed light on a first read for MiFIR. But a second read alongside another ESMA document, the “Data Quality Engagement Framework (DQEF) for MiFIR’ published a week after the report, reminds us that MiFIR transaction reports and their data quality remain a key focus for ESMA and EU National Competent Authorities (NCAs).

    The purpose of MiFIR transaction reporting

    In the data quality report (DQR) ESMA reinforces, should we have forgotten, that data supports the day-to-day activities of financial regulators and remains essential for them to achieve their primary mandates of financial stability, orderly markets and market integrity.

    “Reduce the reporting obligations on firms”

    The DQR provides a number of use cases, introduces the DQEF and gives a significant mention to the role of transaction reports in the transparency and volume cap calculations that will reduce the reporting obligations on firms.  In case you missed it – “reduce the reporting obligations on firms”. The proof of concept (PoC) to prove the role of reports in these calculations determined that data quality is good but the DQEF being introduced is designed to address the critical data quality issues that became apparent during the exercise. 

    Improved tooling for increased scrutiny

    Furthermore, the DQR mentions that ESMA and NCAs now have improved tooling for monitoring markets. This includes details on the ESMA Data Platform (EDP) where regulators can share reported data and access predefined analytics to support them in their work.  As we highlighted last year – firms contributing reports to these calculations that are lacking data quality can expect their NCA to give them an opportunity to discuss the issues found.

    Delving into the details

    At a macro level, reported data under MiFIR is used to monitor overall trends and key market-level developments.  NCAs use the data in national financial stability reporting and sectoral updates whilst some have established systems to monitor trading venue activity or to rank firms based on their risk profiles.

    For the detection of market abuse, NCAs have developed a variety of automated alerting tools to highlight behaviours that could threaten market integrity for follow up by surveillance staff.  Data from different regimes is combined to identify cases of potential market abuse. 

    New tests to enhance data quality

    The PoC to test the potential for using MiFIR data for transparency and volume cap calculations achieved > 95% accuracy and hence will replace the existing systems (FITRS and DVCAP) and reduce the reporting burden for firms.  The discrepancies found will be addressed via the newly established DQEF based on ESMA’s existing transaction data validation rules and the TREM (Transaction Reporting Exchange Mechanism) DQEF tests, with new completeness, accuracy and consistency tests introduced to enhance data quality.

    The aim is to launch the DQEF in the first half of 2025 to allow NCAs and firms to address the quality issues found – ahead of the go live of the new transparency and volume cap system.   

    Conclusion

    We are often asked, ‘do regulators actually use the data?’ and the DQR provides clear evidence that they do. ESMA’s reuse of MiFIR transaction data for transparency and volume cap calculations demonstrates its commitment to reducing duplicative reporting – something the industry has long requested. However, increased data usage means increased scrutiny. Firms submitting poor quality data can expect to be contacted, remediation expected, warnings given and potential enforcement action.

    Firms often approach us for quality assessments after the regulator has challenged their data. This puts them in damage control mode.  The better approach is proactive quality assurance that identifies problems before regulators do. Please don’t hesitate to reach out to us at Kaizen to see how we can help.

  • Kaizen wins Best Solution for Sell-Side Regulatory Compliance

    Kaizen wins Best Solution for Sell-Side Regulatory Compliance

    London, Wednesday 21 May – Kaizen, a leading provider of regulatory compliance solutions for global financial institutions, has won ‘Best Solution for Sell-Side Regulatory Compliance’ at the A-Team RegTech Insight Awards Europe 2025 for its ReportShield™ Accuracy Testing service.  

    Kaizen’s ReportShield™ Accuracy Testing is an automated, managed solution that tests the quality of trade and transaction data reported to the regulator. What makes the solution unique is the deep testing of all reportable trades down to field level, providing financial firms with full visibility of their reporting quality.  Accuracy Testing covers all global trade and transaction reporting regimes.

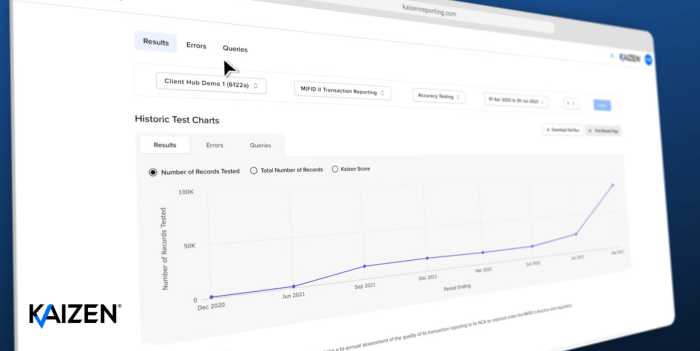
    Clients access their results including detailed management information via the Kaizen Hub, Kaizen’s easy-to-use platform, which also provides actionable insights into reporting quality. They can also assess their ongoing performance with historical trends and compare the quality of their reporting with similar firms, thanks to Kaizen’s large client base.  

    Jean-Marie Mamodesen, Head of European Sales at Kaizen, said: “A big thank you to the editorial and advisory board members who selected Kaizen as the Best Solution for Sell-Side Regulatory Compliance at this year’s RegTech Insight Awards Europe 2025. This award is testament to our commitment to helping financial institutions navigate complex regulatory challenges. As sell-side firms in Europe continue to grapple with the complex changes introduced by EMIR Refit and prepare for the upcoming MiFIR Review, our ReportShield Accuracy testing provides the confidence and clarity they need. By providing detailed insights that go beyond basic validation, we empower our clients to turn reporting from a burden to a business advantage.”

    Angela Wilbraham, CEO of A-Team Group commented: “Congratulations to Kaizen for winning Best Solution for Sell-Side Regulatory Compliance at the fifth annual RegTech Insight Awards Europe 2025. The awards recognise both established providers and innovative newcomers providing RegTech solutions that have successfully improved firms’ ability to effectively respond to evolving and ever more complex regulatory requirements across the global financial services industry.”

    At last year’s RegTech Insight Awards Europe, Kaizen’s Single Rulebook platform won ‘Best Solution for Regulatory Change Management’.

    (ends)

    For more information, please contact James Dunseath, Communications Director, on +44 (0) 7557 955795 or media@kaizenreporting.com

  • WATCH: Introducing Kaizen Insights

    WATCH: Introducing Kaizen Insights

    Kaizen Insights is an exciting new feature of our ReportShield Accuracy Testing. Clients can now navigate from Accuracy Testing results on the Hub to view explanatory texts for incident codes written by our subject matter experts and links to the regulations in Single Rulebook.  Kaizen Insights provides clients with greater transparency of the tests themselves, as well as directing to the section of the regulation where the test is derived.

    Gain immediate access to:

    • Expert interpretations of error codes from our subject matter specialists
    • Clear regulatory definitions and source references
    • Industry best practices to resolve compliance issues
    • Direct links to the relevant regulations within Single Rulebook

    Contact us for a demo or a conversation with one of our regulatory experts. 

  • It was ‘just a matter of time’ before the FCA issued its first fine: Kaizen’s Matthew Vincent speaks to FOW

    It was ‘just a matter of time’ before the FCA issued its first fine: Kaizen’s Matthew Vincent speaks to FOW

    Following the FCA’s first fine for transaction reporting failures under the MiFID II regime, Kaizen’s Matthew Vincent spoke to journalist Gregory Rosenvinge at FOW about what this means for firms and what they should now expect from the regulator.

    Before the fine was issued, Kaizen said it had sensed from clients the FCA was stepping up its focus. “Unfortunately for firms, it appears their patience may have run out. This fine is a timely warning for firms to make sure they have the right systems and controls in place for their transaction reporting,” said Kaizen’s Matthew Vincent.

    Read the full article on FOW’s website (subscription needed).

  • ‘It would be an easy win for the FCA’: Kaizen’s Dario Crispini speaks to Compliance Corylated

    ‘It would be an easy win for the FCA’: Kaizen’s Dario Crispini speaks to Compliance Corylated

    News of the FCA’s first fine for MiFID II transaction reporting errors may be hot off the press, but in 2024 alone the FCA found 139 MiFID firms failing to report transactions. 

    Following a Freedom of Information Act request, Compliance Corylated also found 450 firms have failed to check MiFID transaction reports for accuracy and completeness using extracts from the FCA’s own system. 

    Our CEO Dario Crispini, former FCA regulator, told Rachel Wolcott that “It would be an easy win for the FCA to write letters to all those firms and ask what they are doing.”

    Read the story in full on Compliance Corylated.

  • FCA issues its first transaction reporting fine under MiFID II

    FCA issues its first transaction reporting fine under MiFID II

    The FCA has issued its first enforcement notice for a breach of transaction reporting requirements since MiFID II went live in 2018. A UK-based broker was fined just under £100,000 by the FCA for failing to submit more than 46,000 single-stock contracts for difference (CFD) transaction reports between October 2022 and March 2023.

    Why was the firm fined? 

    Firms take note – what is interesting about this fine is that even though the broker had identified its failure to submit the transaction reports following a third-party review, it did not proactively report the breach to the FCA. It was the regulator that independently identified the discrepancy in transaction data.

    The expectation from the FCA is that as soon as firms identify issues with their reporting, they need to let the FCA know via an error and omissions notification. This then demonstrates to the regulator that they have the right systems and controls in place. 

    The value of the fine

    The high-risk nature of single-stock CFDs with regards to potential market abuse, and the firm’s failure to quickly bring the breach to the FCA’s attention, meant that it was initially fined more than £141,000. The broker received a 30% discount on the penalty for early resolution. The FCA initially allocated a value of £2.00 for each of the broker’s missing transaction reports (a step up from the £1.50 amount in the previous final notice from 2019). However because the FCA deemed that the broker had not acted deliberately or recklessly and there was no or little loss or risk of loss to consumers, investors or other market users this was further reduced as per the existing framework.

    Subsequently under step 4 of their determination the FCA concluded that the “absolute value of the penalty is too small in relation to the breach to meet the Authority’s objective of credible deterrence” and hence multiplied the amount by seven, to avoid “firms being tempted to see any fines imposed because of transaction reporting breaches as a cost of doing business.” This is clearly an area of FCA focus. Firms should review their current processes and governance and take note of the regulator’s less conciliatory stance.  

    What is the background to the fine?

    The general temperature of regulatory scrutiny around transaction reporting has been rising recently, and via Market Watch 81 the FCA was clear in its expectations of firms that they needed to improve their transaction reporting controls and review weaknesses in their processes.

    What did the final notice say?

    The FCA highlighted weaknesses in the firm’s change management processes and potentially a lack of subject matter expertise within the brokerage when it established and operated a new line of business in single-stock CFDs. The FCA notes, “it was the responsibility of a single individual…to manually identify which financial instruments were reportable when new business was commenced”.  It also noted that the firm “did not put in place any steps to scrutinise this process or any checks to ensure that the correct trades had been identified as reportable”. This points to a lack of effective reconciliation, which is expected under Article 15, RTS 22 of MiFIR.

    And while a third party review identified that the broker had not reported the transaction data, as mentioned earlier in this blog, the broker did not proactively contact the FCA regarding the breach. The final notice reiterated that the regulator expects to be notified quickly and not just once prompted.

    What does the fine mean for firms?

    This fine should stand as a warning for firms and a stark reminder to act now and review current processes and governance around transaction reporting. It is important to note the change in temperature from the regulator. The FCA is paying close attention to the transaction reports firms are submitting (and not submitting) and expects firms’ systems and controls to be robust where they do identify breaches.

    Our ReportShield™ quality assurance solutions are designed to give firms peace of mind in meeting regulatory expectations on MiFID II transaction reporting. Available on our easy-to-use dashboard, our solutions are unique in testing every single record at source so that all errors including under and over reporting are detected. Through our experienced team of regulatory experts, we can also advise firms on communication with the FCA and other regulators, and provide training on the reporting requirements. Please contact us for a discussion about your reporting challenges. 

  • WATCH: Regulatory Reporting – 2024 in Review, 2025 Preview

    WATCH: Regulatory Reporting – 2024 in Review, 2025 Preview

    On MiFIR transaction reporting, there were significant changes announced by ESMA and a new discussion paper launched by the FCA, and new regimes are being introduced in the money markets space.

    Watch Kaizen’s regulatory experts as they reflect on 2024, and look ahead to what’s in store for regulatory reporting in 2025.

    The webinar was hosted by Yvonne Deane Harte, Director, Secondary Markets & Post-Trade at UK Finance and featured:

    Please note, we accept business emails only.

    For any queries relating to the upcoming regulatory changes or to speak to one of our subject matter experts, please contact us.

  • Kaizen and RegGenome Announce Strategic Partnership using AI to expand regulatory content on Single Rulebook

    Kaizen and RegGenome Announce Strategic Partnership using AI to expand regulatory content on Single Rulebook

    London, December 3, 2024 – Kaizen, a leading provider of regulatory compliance solutions for global financial institutions, announced today that it has entered into a strategic partnership with RegGenome, a UK based provider of global financial regulatory data, to use artificial intelligence (AI) to vastly expand the coverage and content of Kaizen’s Single Rulebook platform including new jurisdictions and regulatory domains.

    The collaboration between Kaizen and RegGenome will support the digitisation of regulation where both parties will work together to provide fast and efficient access to a vast array of global regulatory rules, jurisdictions and taxonomies on the Single Rulebook platform. By combining Single Rulebook’s front end user interface with RegGenome’s AI powered regulatory data and information structures, the firms will provide clients with a new standard of regulatory intelligence and change management.

    Many financial institutions operate across multiple locations and global regulatory jurisdictions. Today’s announcement means that firms will be able to navigate and respond quickly to the complex landscape of regulatory change and divergence more easily and efficiently.

    In early 2025, Single Rulebook clients will be able to access regulatory content covering all major global financial markets. This includes coverage of US federal regulators and agencies, European national law and global G20 members.

    In addition to core financial services regulations, Single Rulebook users will also be able to investigate emerging compliance requirements for cryptocurrency, cyber security and digital operational resilience.

    Mark Johnston, CEO, RegGenome commented: “We are delighted to announce our strategic partnership with Kaizen’s Single Rulebook. This collaboration will make RegGenome’s comprehensive structured regulatory data available through Single Rulebook’s innovative platform. By combining our extensive regulatory content with Single Rulebook’s advanced search and analytics capabilities, we’re enabling financial institutions to better navigate the complex regulatory landscape.”

    Chris Dingley, CEO, Single Rulebook said: “We’re excited to announce our partnership with RegGenome today. Working with RegGenome’s AI solution for regulatory data and information means that we will be able to expand the Single Rulebook platform and content rapidly for our clients, continuing and enhancing our efforts to support them with the burden of managing global regulation.”

    RegGenome processes global regulation using artificial intelligence (AI) to transform what is human-readable into machine-readable and machine-consumable data. It is part of the Regulatory Genome Project (RGP), a public-private initiative between the University of Cambridge, Judge Business School, and RegGenome. RGP aims to build and review a set of open-access regulatory information structures, known as the Cambridge Regulatory Genome (CRG), and make available a global repository of aggregated, structured regulatory data.  

    Single Rulebook is Kaizen’s digital solution for searching and navigating global regulation. The platform helps firms manage regulatory change with front end functionality such as rule maps, labels and annotations which can be pinned to regulatory rules and shared across global organisations.

    About RegGenome

    RegGenome is a regulatory data technology company and a leader in computational regulation, changing how the world produces and consumes regulatory information. We process the world’s regulation using AI to transform what is human-readable into machine-readable and machine-consumable data. 

    www.reg-genome.com

    For more information, please contact James Dunseath, Communications Director, on +44 (0) 7557 955795 or media@kaizenreporting.com

  • WATCH: Is your regulatory reporting valid but wrong?

    WATCH: Is your regulatory reporting valid but wrong?

    A large majority of the reports that Kaizen tests are ‘valid but wrong’. The valid but wrong scenario occurs when reports pass the validation rules by the regulator or intermediary entity (ARM, SDR or TR) but the data within the reports is inaccurate. 

    Watch our video above to find out more or contact us for a free healthcheck to find out how many of your reports are valid but wrong.


  • ESMA MiFIR Review: Key changes proposed to MiFIR Transaction Reporting (RTS 22)

    ESMA MiFIR Review: Key changes proposed to MiFIR Transaction Reporting (RTS 22)

    ESMA has launched a consultation on Level 2 measures under the MiFIR Review, seeking feedback on transaction data reporting (amended RTS 22) and order book data (amended RTS 24).

    What’s the background to the consultation?

    ESMA published a report in March 2021 on the functioning of the transaction reporting regime under Article 26 of the Markets in Financial Instruments Regulation (MiFIR). This led to a set of legislative proposals included in the review of MiFIR. The final legislative amending text of the ‘MiFIR Review’ was published in the Official Journal of the European Union and entered into force on 28 March this year. This included an updated version of the provisions for transaction reporting (Article 26).

    In this latest regulatory milestone, ESMA is asking for input on its amendments to the regulatory technical standards (RTS) 22, the section of MiFIR which sets out the transaction reporting obligations and reportable fields. The deadline to submit comments is 3 January 2025. We are certain that clients will want to engage with their trade associations and also respond themselves.

    Some of these proposals are far reaching and will be complex to implement. This now feels almost as significant a package of change as the shift from MiFID to MiFID II in 2018.

    From first sight of the initial report through to the publication in the Official Journal, we said that the devil will be in the detail. 

    What are the key changes proposed to RTS 22?

    1. Instrument Scope

    Not a major change but for OTC Derivatives where the underlying is not ToTV or an index made up of instruments that are ToTV then these will only have to be reported if Traded on a Trading Venue unless they are specifically included in Article 8a(2) of the revised MiFIR Text. The consultation includes two diagrams that makes this scope easy to visualise. For firms understanding exactly what is in and out of Article 8a(2) will be the challenge.

    2. Additional Field – Effective Date

    Further details will become clear after consultation but so far for debt instruments, the effective date should be the date when the transaction will be settled and for derivatives it should be the date when the obligation under the contract becomes effective, which may be in the future (forward starting date).

    3. Additional Field – Entity subject to the reporting obligation

    The field will provide added value in the limited instances where the executing and submitting entity differs from the firm with the obligation to report.

    4. TIC or TVTIC, that is the question

    Here is where we start to see significant implementation challenges – the existing challenges of TVTIC will remain i.e. what format and where is the venues “TVTIC” to be found and there is to be more legislation for the extension of “TVTIC” to “negotiated” trades, a new “TIC” for trades executed on Non EEA trading venues. ESMA is also consulting on a proposal for the generation and dissemination of a “TIC” across the entities involved in OTC/XOFF transactions.

    5. Improvements to INTC

    There are proposals to introduce a new identifier to link market side executions to the ultimate fills to multiple clients where a firm aggregates client orders. Fortunately this requirement begins and ends with the executing firm – there is no mention of sharing this code with the clients themselves. So far so good, but ESMA doesn’t stop there.

    6. A new code to link to the same sequence of report chains resulting in the execution of a transaction

    A catchy title with a less than catchy implementation challenge. ESMA proposes to include a new and unique code (Chain Identifier) that is transmitted across all counterparties involved in a chain. All involved parties must make sure to transmit the code to its direct counterparty until the ultimate reporting entity. The introduction of such new identifier would also imply the identification of the primary entity responsible for the creation of the code and responsible for disseminating it. We assume though only to its immediate counterparty.

    The code should be transmitted across the counterparties along with the sequence of confirmations chains. The firm executing the transaction would have the obligation to pass the code down the chain. The firm executing the order should provide a unique code to the client that pertains to the executed transaction that allows the client to produce its own transaction report. Again, more detail will come in the Level 3 (L3) so firms won’t really know what they don’t know until it is completed.

    7. Less complex new asks but more data will be required:

    • Date transactions should be reported – fortunately this is to be a “fixed” date which will be equal to the date of application of the revised RTS 22.  Here ESMA adds further detail “The application date should also ensure sufficient time for implementation, which… should be ideally 12 months from when the technical documentation is available”. Our question is does the “technical documentation” include all Level 3 – as a lot of Level 3 will be required to clarify some of the additional requirements specifically relating to the TIC/Chain and INTC requirements.
    • Additional data to identify indexes, aligns to the benchmark regulation and splits the field into two components.
    • Alignment of Buyer /Seller /Price /Complex trades and packages to EMIR. There is a lot of detail as to the changes required for Buyer/Seller identification for derivative transactions which at least if aligned to EMIR, firms will be able to cross reference interpretation already recently undertaken for EMIR Refit.
    • Inclusion of a DLT identifier in transaction reports for financial instruments that are natively issued on a blockchain and for financial instruments that are re-issued in a tokenised form.
    • Client categorisation.

    There are a number of other changes as to Order Transmission/exclusion of some additional transaction types and some adjustments to field definitions and names, but I leave you with this one hidden in the revised text of the RTS:

    8. No 1st Priority Identifier – No Trade

    “The highest priority identifier shall be obtained by the investment firm from the client/relevant party prior to trading”. This is the MiFIR Review equivalent of ‘No LEI No Trade‘ of 2018. We know firms do and have made significant efforts to capture Level 1 identifiers but have relied on the fall back if they don’t have it. ESMA is proposing to remove that fall back altogether.

    What happens next?

    Following the consultation period, ESMA will publish a final report and submit the draft RTS to the European Commission for adoption in Q1 2025. 

    For Kaizen clients, our ReportShield quality assurance testing will continue on the basis of the current regulations, rules and guidance. We will be following the consultation process closely with our clients and partners and will provide further updates as the changes crystalise in early 2025. 


  • Book your place on the Transaction Reporting Academy

    Book your place on the Transaction Reporting Academy

    Join Kaizen and PIMFA for our Transaction Reporting Academy, developed and delivered by our regulatory experts Simon Appleton and Matthew Vincent, starting on 8 October 2024. 

    The academy aims to upskill individuals involved in the reporting process and those responsible for regulatory oversight with the expertise they need to meet regulators’ expectations and promote high-quality reporting.

    The course is suitable for those working in buy side and sell side firms. 

  • Kaizen and LPA partner to provide transaction reporting assurance solutions

    Kaizen and LPA partner to provide transaction reporting assurance solutions

    London, Frankfurt am Main – 26 June 2024 – Leading regulatory technology firm, Kaizen and Lucht Probst Associates (LPA), the German capital market technology and advisory firm, have partnered to offer a range of compliance solutions to international clients.

    The new partnership will allow Kaizen and LPA to work with clients offering them independent transaction reporting assessments and regulatory reconciliations solutions.

    Kaizen’s ReportShield™ Accuracy Testing is an automated, managed solution that tests the quality of trade and transaction data reported to the regulator. What makes it unique is the comprehensive deep testing of all records, which provides financial firms with full visibility of their reporting quality. In addition to Accuracy Testing, Kaizen offers an Advanced Regulatory Reconciliation solution that provides an independent assessment of the completeness of a firm’s regulatory reporting to identify under and over-reporting.

    LPA offers a broad range of consulting services for banks, asset managers, and exchanges, with a strong focus on capital markets. Our expertise extends to the implementation of regulatory requirements in transaction reporting. Beyond the initial setup of transaction reporting regimes, we place a significant emphasis on data analysis, optimizing data quality, and enhancing the efficiency of reporting processes.

    Jean-Marie Mamodesen, Managing Director – Head of European Sales at Kaizen, commented: “LPA has a strong reputation in Germany and we are delighted to be working with them. By bringing the skillset and expertise of the two companies together we are able to provide solutions that ensure that the data which firms are reporting to the regulators is of the highest quality.”

    Hans Joachim Lefeld, Senior Partner – Head of Transaction Reporting from LPA said: “We are delighted to be working with Kaizen, who offer an array of market leading compliance solutions. By joining forces with Kaizen we extend our eco system and will be able to better serve our clients and help them navigate the complexity of the global regulatory reporting landscape.”

    (ends)

    About LPA

    Founded in 1999 by Stefan Lucht and Roland Probst, LPA was one of the first financial services providers to focus on technology solutions and consulting that optimize processes and guarantees regulatory compliance. LPA’s success is based on sound capital market expertise combined with ongoing technical innovations. Following the integration of Modelity, EffCom and AAAccell, the rapidly growing software and consulting company employs around 400 people at twelve international locations.

    www.l-p-a.com

    For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com

  • Kaizen partners with Suite2Go to offer regulatory reporting quality assurance solutions in APAC

    Kaizen partners with Suite2Go to offer regulatory reporting quality assurance solutions in APAC

    London, Sydney, 5 June 2024 – Leading regulatory technology firm, Kaizen and Suite2Go, the Australian financial software consultancy have partnered to offer Kaizen’s ReportShield™ quality assurance solutions in APAC, as part of its continued expansion in the region.

    Kaizen’s ReportShield™ Accuracy Testing is already used by 18 firms in Australia, including some of the largest banks and asset managers. This means that 50% of ASIC’s systemically important banks use our assurance solutions.

    Accuracy Testing tests the quality of trade and transaction data reported to the regulator. What makes it unique is the comprehensive deep testing of all records, which provides financial firms with full visibility of their reporting quality. The solution is available via the Kaizen Hub, Kaizen’s easy to use web-based platform. It is the only assurance solution that is tailored to all global derivative reporting regimes including ASIC, MAS, HKMA, MiFIR transaction and post-trade reporting, EMIR, and SFTR.

    In addition to Accuracy Testing, Kaizen offers an Advanced Regulatory Reconciliation solution, which is an end-to-end solution that provides an independent assessment of the completeness of a firm’s regulatory reporting to identify incorrect interpretation or application of the regulations, enabling all under and over-reporting to be detected. The solution also identifies mismatches across all the reported data fields (e.g.  price, quantity, product difference etc).

    Dario Crispini, CEO of Kaizen, said, “This new partnership with Suite2Go is an important step in our plans to bring our ReportShield solutions to the wider APAC region. With the constant evolution in the global regulatory landscape, including the upcoming ASIC, MAS and HKMA ReWrites, firms face the challenge of being able to report their trade and transaction data in an accurate, complete and timely manner. Kaizen’s ReportShield™ solutions help firms deliver the quality of data that the regulators have come to expect, and by partnering with Suite2Go we look forward to supporting organisations in the APAC region.”

    Andrew King, Principal at Suite2Go, commented, “We are delighted to have the opportunity to work with Kaizen in the Asia Pacific region. The solutions they offer will be invaluable to the many firms that have reporting obligations in APAC and we look forward to helping develop their presence in the market.”

    (ends)

    For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com

    About Suite2Go

    Based in Sydney, Australia, Suite2Go is a financial software consultancy team of experienced professionals with deep working knowledge of the financial services industry and how to best solve for workflow challenges through technology solutions. 

    We were founded in 2017 with a team of 8, comprising principals and consultants with an average of 20+ years experience who have expertise across; capital markets, data management, regulatory and risk reporting, superannuation, asset, and wealth management, including front and back office, asset servicing and payments. We look to assist world class fintech organisations to achieving success in their chosen target market by bringing solutions to the financial services industry to overcome challenges and address problems while saving cost and time for both buyers and sellers.

    Press Contact: Leanne Bradley, Co-CEO leanne@suite2go.com

  • ESMA Data Quality Report 2023: What does it say about MiFIR?

    ESMA Data Quality Report 2023: What does it say about MiFIR?

    ESMA published its 2023 Report on the Quality and Use of Data earlier this month. In this blog, we focus on the MiFIR elements of the report. 

    In June 2023, ESMA updated its data strategy defining how data will be used to support its objectives and reiterated that data plays a critical role in the day-to-day processes of NCAs, central banks (such as the European Central Bank (ECB)) and ESMA. Data is used extensively allowing financial regulators to fulfil their obligations under their key mandates to maintain financial stability, orderly markets, and market integrity.

    How ESMA is using ARM and APA data

    In the context of supervision of data reporting service providers (DRSPs), ESMA notes in the report that it uses metrics relating to the timeliness, completeness, availability and integrity of data received by approved reporting mechanisms (ARMs) and approved publication arrangements (APAs). It draws attention to the fact that the number of files rejected by ARMs has fallen significantly, suggesting better quality of data. ESMA conducted a comparison of transactions reported to ARMs with those published by APAs, evidencing issues around APA data access and aggregation, which triggered follow-up actions from a supervisory and policy perspective. ARM transaction data was also used to detect and investigate one case of significant overreporting relevant for the MiFIR transparency calculations. 

    ESMA notes that the observations drawn from its analysis lead to new validation rules, enhancements of test methodologies and guidance in the definition of reporting fields. In the report, it publishes a list of publicly available reports detailing how regulatory reporting data has been used to support the analysis. It uses examples such as the evolution of EEA share market structure since MiFID II published in October 2023, and a study by the AMF in France that used MiFIR data to analyse the profiles of individuals conducting retail investor activity.

    Comparison between transaction and transparency data

    The report also details that ESMA assessed the consistency between transaction data reported by ARMs and transparency data published by APAs. It found that reports common to both datasets exhibit a reasonable level of price consistency, whilst the use of machine learning (clustering) allowed the identification of misreporting patterns which have been notified to reporting entities. One result of the comparison between transparency and transaction data allowed ESMA to identify an incorrect reporting practice used by multiple organised trading facilities, leading to duplication in the transparency system.

    As per last years’ report, it is clear that data remains a priority for ESMA and with that, data accuracy. Regulators are clearly using the data to support their statutory objectives and outliers in the data will be identified, action taken and importantly for firms, data quality issues will be raised with the reporting firms themselves.

    • Read the ‘2023 Report on the Quality and Use of Data’ in full on ESMA’s website.
    • Read our blogs on the 2023 Data Quality Report on EMIR and SFTR.
    • For a free heathcheck of your MiFIR reporting (transaction, post-trade transparency or RTS 23 instrument) please get in touch.
  • Berenberg Selects Kaizen for Regulatory Reporting Assurance

    Berenberg Selects Kaizen for Regulatory Reporting Assurance

    London, Hamburg, 17 April 2024 – Berenberg, one of Europe’s leading privately-owned banks, has selected leading regulatory technology firm, Kaizen as its regulatory reporting assurance provider.

    The agreement sees Berenberg take Kaizen’s award-winning (ReportShield) Accuracy Testing to support the bank to effectively meet the regulatory requirements of complete, accurate and timely EU and UK MiFIR transaction reporting.

    Kaizen’s ReportShield™ Accuracy Testing is an automated, managed solution that tests the quality of trade and transaction data reported to the regulator. What makes it unique is the comprehensive deep testing of all records, which provides financial firms with full visibility of their reporting quality. The solution is available via the Kaizen Hub, Kaizen’s easy to use web-based platform. It is the only assurance solution that is tailored to all global reporting regimes including MiFIR transaction and post-trade reporting, EMIR, and SFTR.

    In addition to Accuracy Testing, Kaizen offers an Advanced Regulatory Reconciliation solution that provides an independent assessment of the completeness of a firm’s regulatory reporting to identify under and over-reporting. It identifies mismatches of data (price, quantity, product difference etc) between a firm’s trading systems and what has been reported to the regulator.

    Jean-Marie Mamodesen, Managing Director – Head of European Sales at Kaizen, commented: “We are delighted to be working with Berenberg, one of Europe’s leading privately-owned banks, to independently check the quality of their EU and UK MIFIR Transaction Reporting data. It’s a challenging time for firms as they grapple with significant regulatory change including EMIR Refit and the EU’s MiFIR Review. The solutions we offer at Kaizen help ensure that firms have the best control framework in place and are better served to deliver the high standards that the regulators have come to expect.”

    Stephan Henning, Head of TS Clearing & Reporting at Berenberg said: “We are delighted to be working with Kaizen. In this way, we can further automate and improve processes in the area of reporting and create significant added value for our customers. We look forward to a successful long-term partnership with Kaizen.” 

    (ends)

    About Berenberg

    Berenberg was founded in 1590 and is today one of Europe’s leading privately owned banks with its Wealth and Asset Management, Investment Bank and Corporate Banking divisions. The Hamburg-based bank is managed by personally liable partners and has a strong presence in the financial centres of Frankfurt, London and New York.

    • For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com
  • FCA releases Market Watch 78 focusing on instrument reference data under RTS 23

    FCA releases Market Watch 78 focusing on instrument reference data under RTS 23

    The FCA has released Market Watch 78, which focuses on improving data quality for instrument reference data. At face value the audience for this newsletter appears to be trading venues or systematic internalisers (SIs). However all MiFIR investment firms should take a keen interest in its contents because the standards expected for the submission of IRD apply equally to other reporting obligations.

    The FCA highlights that:

    • Issues with IRD impact its ability to monitor markets effectively
    • IRD is key to its ability to conduct effective market oversight
    • IRD enables it to understand the nature and characteristics of products traded by market participants.

    Interestingly the regulator notes that UK EMIR trade reports are enriched with IRD to monitor for systemic risk. This is a step beyond just validating and supplementing of transaction reporting submissions (RTS 22) and transparency data (RTS 1,2,3).

    Data quality processes

    The FCA highlights its concerns with firms’ data quality processes, including where firms are repeatedly submitting identical records after receiving a rejection message. This should be a lesson for all firms submitting reference data as the FCA says that this could indicate weakness in firms’ exception management processes. The FCA is also concerned about, and presumably monitoring, the late submission of IRD as this can prevent investment firms from submitting transaction reports.

    In addition, the FCA draws attention to the fact that IRD submitting entities should include a review of warnings generated by the Market Data Processor (MDP). It can be inferred that the regulator does not believe this review is robustly taking place. In particular, the FCA focuses on Warning Message INS-128. Firms should be developing a check for inconsistencies with their submissions and including a process to resend the corrected record, or discuss the record with the relevant trading venue.

    The FCA provides a table with top 10 rejection codes by count and drills into best practice for firms to deal with a couple of the topics – Invalid issuer LEI and Invalid instrument classification.  A particular pattern on the table is validation errors related to the relationship between the first trade date and other key date fields. 

    Across all regimes the expectation is that firms have arrangements in place to identify incomplete or inaccurate data, and report data in a timely manner, beyond reviewing rejections. The FCA further notes that there is prevalent use of dummy or default values in IRD submissions, highlighting specifically:

    • instrument classification
    • name of the index/benchmark of a floating rate bond
    • identifier of the index/benchmark of a floating rate bond.

    Breach notifications

    In the final section of the newsletter, the regulator says it has received 135 breach notifications since 2018 and is “concerned that some IRD submitting entities may not be notifying us when they identify issues”.  When submitting IRD, firms should therefore make sure they have the same robust breach notification process in place for notifying the Markets Reporting Team across both RTS 22 and RTS 23.

    Cancelled instrument reference data

    The newsletter also highlights that only 23 entities have cancelled records in its FIRDS system over the past two years.  This means that most IRD submitting entities haven’t used this functionality.  The FCA says it expects “all entities to have processes to cancel records when required”.

    What does Market Watch 78 mean for firms?

    This Market Watch clearly highlights the importance the FCA attaches to ensuring high IRD quality as it underpins the integrity of the data for conducting effective market oversight.

    “Firms must have processes to ensure that their IRD submissions are accurate” – Market Watch 78

    It may also prompt firms without a RTS 23 reporting obligation to investigate whether their transaction reporting submissions match the static characteristics of the instrument’s reference data, and question whether they are highlighting potential data quality issues as a result.

    At Kaizen, our RTS 23 Accuracy Testing managed service provides firms with full visibility of instrument reference data reporting issues across the topics mentioned in Market Watch 78 and beyond, ensuring trading venues and SIs meet their reporting obligations and effectively manage their reporting risks.

    • For a free healthcheck of your RTS 23 instrument reference data, please contact us.
    • Read the newsletter in full on the FCA’s website.
  • What does daylight saving mean for regulatory reporting?

    What does daylight saving mean for regulatory reporting?

    On 31 March, in the early hours of the morning, clocks across the UK and the majority of mainland Europe will go forward an hour. Since Europe spans several time zones, the switch will occur at different local times. 

    Whilst you may need to adjust the clocks at home or spend another six months with different times on the microwave and oven, please remember that the time fields for UK & EU MiFIR trade and transaction reporting and UK & EU EMIR trade reporting should continue to be populated in Coordinated Universal Time (UTC).

    Trade time is of significant importance to regulators. As we have highlighted before, UK and EU NCAs are unlikely to be sympathetic if you make errors following these time transitions.  The UK’s FCA has warned firms of such mistakes for many years:

    “The time when the transaction was executed should be reported in Coordinated Universal Time (UTC). We continue to see errors in transaction reports when UK clocks transition to and from British Summer Time, as well as errors driven by inaccurate clock synchronisation. Firms should have arrangements in place to ensure consistent and accurate reporting of trading date and time.”  Market Watch 59.

    The CSSF in Luxembourg has also commented as to the importance of this field:

    “In the context of data quality tests performed on transaction reports, the CSSF identified that in several transaction reports the time indicated in field 28 “Trading date time” was the local time instead of UTC. Investment Firms have been informed that, within the framework of the transaction reporting obligation, dates and times shall always be reported in UTC.”

    • For more details or a discussion with one of our regulatory experts, please contact us. 
  • Matthew Vincent speaks to IFLR on post-Brexit divergence

    Matthew Vincent speaks to IFLR on post-Brexit divergence

    Kaizen’s Matthew Vincent spoke to Thomas Helm on the topic of post-Brexit divergence, which is forcing firms with both a UK and an EU presence to operate two separate compliance policies and reporting systems.

    Excerpt: 

    Matthew Vincent, managing director at Kaizen, used the niche topic of MiFID II’s RTS 22 as an example of a seemingly small divergence area that may come with a large price and complexity tag.

    “The EU’s review text is so unspecific around the conditions for linking specific transactions and identifying aggregated orders that it could mean anything at this stage,” he said. “In any case, this is the first legislative divergence from FCA (Financial Conduct Authority) reporting. The high level of granular detail may make this challenging for firms to implement.”

    Kaizen has been helping clients by holding awareness-raising events in which they pinpoint changes on the horizon.

    “Horizon-mapping” helps firms locate and assess the known unknowns, such as RTS 22, in an orderly manner, Vincent explained.

    Knowing when the changes will take place – or at least when ESMA, in the case of RTS 22, is expected to fill in the blank spaces – is the first step towards compliance.

    Read the article in full on IFLR’s website.

  • Chris Machin speaks to IFLR on consolidated tape implementation

    Chris Machin speaks to IFLR on consolidated tape implementation

    Kaizen’s MiFIR Reporting Director Chris Machin spoke to IFLR on the technical and political complexities that may present roadblocks for consolidated tape implementation in the EU and UK.

    “It is the sheer complexity of both the data and the political landscape that makes me question whether the regulators and mandated firms will succeed.

    “Differences in data standards among both the APAs and the asset classes make consolidation costly and difficult, especially in fixed income and derivatives.”

    Read the full article here.  (You must be a subscriber to view the article in full).

  • Regulatory Reporting – 2024

    Regulatory Reporting – 2024

    Watch our webinar replay to find out what you need to do to stay on top of 2024’s unprecedented regulatory change.

    • Proposed changes to MiFIR Transaction and Post-Trade Transparency Reporting
    • EMIR Refit go live in the EU and UK
    • APAC derivative reporting rewrites and global harmonisation of reporting rules
    • MMSR expansion and new rules on securities lending and uncleared bilateral repo in the US
    • Proposed changes to CFTC Part 43 and 45 reporting.

    Speakers

    Hosted by Kaizen’s Co-Founder and Managing Director Ian Rennie, the webinar features: 

    For any queries relating to the webinar or to speak to one of our subject matter experts, please contact us.

  • Kaizen’s CEO Dario Crispini speaks to FinTech Global

    Kaizen’s CEO Dario Crispini speaks to FinTech Global

    Following Kaizen’s inclusion in the 2024 RegTech100 listing, our CEO Dario Crispini spoke to FinTech Global about the key challenges facing the industry today, including staying connected in a post-Covid world and how the Kaizen Community is bringing compliance professionals together by combining technology and regulatory expertise with in-person networking opportunities.
     

    “We’re trying to have more touch points across our client base and use our position in the industry to bring clients together so they can share their war stories and their pain points… There is an appetite to get back together and to start chatting and networking with peers. We are facilitating that.”

    Read more

  • Kaizen selected as RegTech100 Company

    Kaizen selected as RegTech100 Company

    London, 6 December 2023 – Leading regulatory technology firm, Kaizen today announced that it has been selected for the RegTech 100 listing, an exclusive directory of the world’s leading RegTech companies, for the fourth time. The RegTech100 companies are chosen by a panel of analysts and industry experts as the world’s most innovative and disruptive businesses in the regulatory technology space that are seeking to help financial institutions manage the fast-paced changes brought on by ongoing regulatory updates and technological advances.

    Chosen from a longlist of over 1,400 companies worldwide, Kaizen was selected for its RegTech solutions which provide a network of services for the compliance and reporting community on one platform.

    Dario Crispini, CEO of Kaizen, said,

    “We are very proud to have been selected as a RegTech100 company for the fourth time and to be recognised for the range of solutions we now offer our clients. Our aim is to make working with regulation easy and cost effective and ensure clients stay on top of their compliance obligations through the introduction of new technologies and product innovation.”

    RegTech Analyst director of research Mariyan Dimitrov said, “With the tougher economic climate and the continued rise of AI, financial institutions are re-examining the compliance software’s true cost, namely whether a given RegTech solution truly will free up compliance staff for higher-level tasks and whether the software can scale, adapt, and get implemented efficiently. This year’s RegTech100 list highlights the leading companies in areas such as information security, compliance, risk management and fraud prevention working on the forefront of innovation and new AI implementations who have demonstrated a strong track record delivering regulatory and operational improvements in financial services.”

    Since last being listed as a RegTech 100 company, Kaizen has expanded its product offering. Our ReportShield™ suite of regulatory reporting assurance services, which includes Kaizen’s award-winning Accuracy Testing, is now complemented by solutions for monitoring and reporting of Shareholding Disclosures, Trade and Communications Surveillance, Research Management, and Single Rulebook, a digital platform for managing regulatory rules.

    (ends)

    • For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com.
  • Register: MiFIR Transaction Reporting – Developments in the UK and EU

    Register: MiFIR Transaction Reporting – Developments in the UK and EU

    Join Kaizen and the Investment Association for a webinar focused on MiFIR Transaction Reporting – Developments in the UK and EU. 

    The webinar will take place on Tuesday 12 December from 14:00 to 14:45 GMT.  

    During the webinar, Kaizen’s MiFIR Reporting Specialists Simon Appleton and Matthew Vincent, will join Alex Chow, Investment Association Operations Policy Lead, to cover:

    • The key announcements made by UK and EU regulators this year
    • Market Watch 74
    • The changes on the horizon that will impact firms
    • Answer your questions.

    The webinar is free to attend and open to IA members and non-members.

    Register

  • EU legislators agree changes to MiFID II and MiFIR

    EU legislators agree changes to MiFID II and MiFIR

    EU legislators have agreed the proposed changes to MiFID II and MiFIR, bringing us a step closer to their implementation. The changes are expected to be published in the Official Journal in Q1 2024.

    Focusing on Article 26, these amendments will require significant detail to be developed in RTS 22 over the following 9-18 months, meaning that it will not be possible to fully comply until the RTS is in place.

    ESMA is expected to consult on the likely changes to the RTS in Q1 2024. 

    Earlier in the year we explained what we might expect to see in the revised Article. We can now confirm the changes that will impact firms reporting to EU NCAs under the new regulations in what will be the first “real legislative” divergence between EU and UK reporting rules. 

    Broadening the scope of firms caught by the obligation to report

    MiFIR Article 52 now includes a requirement that the Commission will, in close cooperation with ESMA, assess the possibility of extending the requirements of Article 26 to Alternative Investment Fund Managers (AIFMs), and management companies which provide investment services and activities and which execute transactions in financial instruments.  They have 12 months to do so from publication.  

    Strengthening the obligation on NCAs

    ESMA has added three additional requirements on NCAs to distribute the reports to not only;

    • the competent authority of the most relevant market in terms of liquidity for those financial instruments;

    But also,

    • the competent authorities responsible for the supervision of the transmitting investment firms
    • the competent authorities responsible for the supervision of the branches which have been part of the transaction, and
    • the competent authority responsible for the supervision of the trading venues used.

    We can’t be 100% certain whether this obligation will mean any additional data will be required from firms in their reports or whether there is sufficient detail already to enable NCAs to comply with this.

    Instruments in scope

    The OTC derivatives transactions in scope has been amended. All OTC derivatives trades executed on venue will be in scope of transaction reporting – no change. Also in scope will be  off-venue OTC trades which fall within the transparency requirements.

    The amended transparency obligation has removed the link to the “traded on a trading venue”/TOTV concept and now covers OTC derivatives which are denominated in major currencies (Euro, Yen, US Dollar or Pound Sterling) and which are subject to the clearing obligation. Where these OTC derivatives are interest rate swaps, only the most liquid tenor combinations are included.

    TvTIC in Level One

    The TvTIC is now included in Level 1 legislation:

    “Reports on a transaction made at the trading venue shall include a transaction identification code generated and disseminated by the trading venue to both buying and selling members of the trading venue.”

    We are not convinced that bringing the requirement into Level 1 legislation will solve the implementation challenges associated with it.

    Farewell to the short selling flag…

    As expected, the obligation to report the short selling flag has finally been removed which aligns EU legislation with UK Supervisory priority.

    Branch Reporting

    No change to the substance but some of the text from RTS 22 covering third country firm branch reporting has been moved up into Level 1 text.

    Pre-Trade Waiver

    The obligation to report the “applicable waiver under which the trade has taken place” has also been removed. This also aligns EU legislation with current UK FCA Supervisory priority.

    Linking

    Of potential concern is the addition of the following requirement – the details of which won’t be fully realised until we see the amended RTS 22:

    ‘(j) the conditions for linking specific transactions and the means of the identification of aggregated orders resulting in the execution of a transaction;’ and

    ‘(k) the date by which transactions are to be reported.’

    This could result in significant implementation challenges for firms when we fully understand which “specific transactions” they mean and how they are to be linked. With MTCH capacity not solving the problem of linking market-side to client-side fills, it may be that paragraph (j) is ESMA’s solution.

    Paragraph (k) doesn’t seem to add much for regulators but firms will have to build complex logic to determine when exactly is T+1 – over weekends and ever shifting bank holidays.

    Our reaction

    Much of the content has been anticipated for a while and although some of these changes will reduce the reporting burden on firms, others are likely to prove more challenging to implement and report accurately.

    The implementation timeline has not yet crystallised and the changes will also likely require a revision of the reporting guidelines.  For the details we will have to wait for the consultation paper expected early in the New Year. 

    • Read the European Council’s announcement on its website.
    • To find out how you can achieve accurate, complete and timely MiFIR reporting, whether EU or UK, or for a discussion with Matthew on the reporting changes, please get in touch.
  • FCA publishes Market Watch 74 highlighting common transaction reporting errors

    FCA publishes Market Watch 74 highlighting common transaction reporting errors

    The FCA has published its latest newsletter, Market Watch 74, and once again has used it to draw firms’ attention to common transaction reporting errors.

    This Market Watch is of particular interest as it tackles several issues not highlighted in the past, as well as reminders for some more familiar issues. 

    MDP data

    Despite the number of firms downloading data from the regulator’s Market Data Processor (MDP) showing a steady increase year-on-year, the FCA has reminded firms of their legal obligation to reconcile their records to MDP data and note that they have contacted firms who haven’t done so. 

    Not all EU NCAs make this as straightforward as the FCA, and the legal obligation remains to reconcile front office records to the latest point at which the data is available, be that from the ARM or NCA. 

    However, despite the increase in the number of firms accessing their data from the MDP there has been a fall in the number of firms raising errors and omission forms. This is somewhat surprising and contrary to our experience at Kaizen where although quality is – as noted by FCA – improving, many firms are still finding and resolving issues dating back to MIFIR go-live in 2018, resulting in costly and time consuming replay exercises.

    Identification of IDM and EDM

    There has not been much written guidance here from NCAs in the past as to “who” firms should populate in this field. The FCA has given some clarity and suggests that an individual named in either of these fields should have more than “limited practical involvement in those decisions at a transaction level.”

    Complex Trades

    The ESMA guidelines here have always, in our opinion, been clear but the FCA has reminded firms that reports linked by a Complex Trade ID should be reported with the same price. The regulator has also reminded firms that adherence to ESMA guidelines is still expected. 

    Transmission Agreements

    When is an agreement not an agreement, or perhaps when is an arrangement not an arrangement, those are the questions…

    The legislation is not prescriptive but the receiving firm needs to populate its report with data received from the transmitting firm. This, in itself, implies that the transmitting firm has to seek some assurance that the “receiving firm” has a mechanism in place to take this data and will make the necessary reports to ensure its obligation to report will fall away under Article 4.

    Unfortunately, some firms relying on Article 4 didn’t get that assurance and have therefore not been making the correct transaction reports.

    Transmitting firms must make certain they have evidence of the provisions in place with their receiving firms to benefit from Article 4. 

    Inconsistent Price & Quantity Notation

    The devil is in the detail here but there should be no excuse for firms not reporting the majority correctly. ESMA/FCA validation rules will only prevent some of common errors.  ESMA also mentioned price discrepancies reported for CDS in its recent Data Quality Report albeit from a slightly different angle. 

    TVTIC on Negotiated Trades

    The FCA has clarified this is an optional field where the trade is bought under the rules of the venue. 

    Chains

    The FCA has clarified the reporting of the Fund Manager and not the Fund, and the subsidiary and not the client of the subsidiary.

    Fields 42 – 56

    The regulator has reminded firms of the importance of getting supplementary instrument data correct where an ISIN is not used in Field 41.  They have commented on this several times in previous editions of Market Watch.

    Could it happen here?

    Following the arrival of any Market Watch, best practice dictates that firms now take steps to reassure their Senior Managers that all is well and that these errors wouldn’t, couldn’t, or shouldn’t, be happening on their watch. 

    In Market Watch 74, the FCA makes it clear that firms should heed their warnings: 

    “….some firms are not paying sufficient attention to our warnings on the importance of reporting transactions to us in a complete, accurate and timely manner.”

    And:

    “We may conduct further work on the areas covered in our Market Watch articles to ensure appropriate remedial actions are undertaken by firms.” 

    Perhaps firms would be wise to read “may” as “will”. 

  • Webinar: MiFIR Transaction Reporting with PIMFA

    Webinar: MiFIR Transaction Reporting with PIMFA

    Date: Thursday 29 June 2023
    Time: 11:00-12:00pm BST

    Join Kaizen’s Matthew Vincent and Simon Appleton and PIMFA’s Kevin Sloane for a webinar where they will unpack the challenges of reporting accurately, the importance of data quality and meeting regulatory expectations, and provide practical solutions for firms to ensure they are reporting correctly.

    Key webinar discussion topics include:

    • Common errors in regulatory reports
    • How to put the right controls in place
    • Consequences of inaccurate reporting
    • How to take your reporting from ‘Good’ to ‘Great’

    Book here

  • ESMA’s spotlight on data quality – Part 2: the use and quality of MiFIR transaction data

    ESMA’s spotlight on data quality – Part 2: the use and quality of MiFIR transaction data

    MiFIR transaction reporting data was a surprise inclusion in ESMA’s recent data quality report which has previously focused on EMIR and SFTR. The report includes some noteworthy updates around the key developments affecting data quality and colour on additional use cases that go beyond the traditional uses of the data. One notable area is where National Competent Authorities (NCAs) are using transaction reporting data to understand the behaviours of retail investors.

    This work is contributing to ESMA’s wider work on retail risk indicators, again highlighting the importance of complete and accurate identification of natural persons.

    The report also details ESMA’s consistent approach to monitoring data quality and reminds readers that the cornerstone for the efficient and effective fulfilment of the authorities’ mandate is high-quality data.

    ESMA hopes that based on the lessons learnt and the development of a revised strategic approach to supervisory convergence on data quality, there will be further strengthening in its outcome-focused, data-driven, and risk-based approaches to supervising the reporting regimes.

    Key developments and the supervisory actions affecting data quality across MiFIR

    • ESMA becomes the supervisor of significant Data Reporting Service Providers (DRSPs)

    To meet the need for improved data quality convergence across the EU, ESMA became the direct supervisor of the most significant DRSPs in January 2022. In total, this accounts for almost 99% of reported transactions amongst registered ARMs. In the second half of the year, the volumes stabilised at around a monthly average of 650m transactions, but this was preceded by some volatility in the first half of the year, with the first quarter having an average of over 900m. Approximately half of the reports received by NCAs were received directly, ie. they were not reported through an ARM.

    • Insights from the analysis of CDS prices

    ESMA is looking to provide clarifications or modifications to the reporting of certain fields, with the aim of improving consistency. It provides a clear use case when highlighting the reporting of the price of Credit Default Swaps (CDS). Out of 260k reported CDS transactions, 200k were reporting with basis points as the applicable price type. Out of this population of 200k, 89% of the trades were reported with a standardised coupon and the remaining 11% were reported as a quoted spread.  This should give firms food for thought and the opportunity to review how they are reporting CDS transactions.

    • Lessons learnt from the analysis of MiFIR transactions data for the Carbon Market Report

    Another use-case comes from the Carbon Market Report where MiFIR transaction reports were used to provide important insights into the trading of emission allowances from H2 2021. The reported data was supplemented with information from other sources which will be familiar to many: ANNA, MiFIR Reference Data (FIRDS), GLEIF and ESMA counterparty data based on the EMIR trade repository data and public registers of counterparties. ESMA notes “unprecedented analysis” and the “multiple challenges associated with reconciling the various data sources”.

    This could point to areas of inconsistency with the transaction reporting data. In addition, other challenges called out were duplicated buy-sell chains and aggregation of the data. What is particularly interesting about this line is that ESMA may be proactively addressing this challenge through the proposed changes to the legislative text: “(j) the conditions for linking specific transactions and the means of the identification of aggregated orders resulting in the execution of a transaction.”

    • Consistency of transaction and transparency data

    ESMA has also undertaken a project to analyse the data from transaction reporting and post-trade transparency reporting to identify gaps in completeness in either domain. To add to this, ESMA has initiated ad-hoc supervision to assess the consistency between APA and ARM data from transaction and transparency reporting.

    ESMA’s focus on transaction reporting data quality is clear, so too is the emphasis on using the data to go beyond investigating market abuse. MiFIR transaction reporting data is increasingly providing ESMA the opportunity to delve deeper into tangible use-cases assessing and supporting the functionality of the market. Increasingly, transaction reports are cross-referenced and supplemented by additional data sources, which helps ESMA to highlight poor data quality and increasingly shape policy developments across transaction reporting and beyond. We can also see examples of this approach in the UK.

    • Read the full report on ESMA’s website
    • Read our blog on the EMIR aspects of the report
    • If you would like to discuss your MiFIR reporting data quality with Robert or one of our regulatory experts, please contact us.


  • Improving Equity Secondary Markets: A Debrief

    Improving Equity Secondary Markets: A Debrief

    The FCA has released its much-anticipated policy changes on the back of last year’s consultation: ‘Improving Equity Secondary Markets’, part of the Treasury’s Wholesale Markets Review (WMR).  As suggested, the aim is to enhance execution quality, increase liquidity and ultimately strengthen the UK’s position and competitiveness in global wholesale markets.

    This first Policy Statement relates to equities only, RTS 1 of MiFIR, and the majority of proposals will enter into force in April 2024, although it is noted that, for investment firms, changes in areas like pre-trade waivers will apply immediately (per the FCA’s existing powers). So please read through the document and understand the impact on you and your organisation…

    The Future Regulatory Framework (FRF) Review gave responsibility of retained EU law to the regulators and subsequently moves the UK MiFIR/MiFID II regime into the FCA Handbook.  Improving the content of Post-Trade Transparency (PTT) Reporting with a clearer identification of transactions that contribute to the price discovery process in a consolidated way, was important. The simplification of reporting by delineating the Systematic Internaliser (SI) regime from the new Designated Reporter Regime (DRR) was also key.

    The changes by the FCA should lead to:

    • improved market liquidity
    • more efficient prices
    • greater competition, choice and access between trading venues, SIs and investment firms
    • lower operating costs for firms
    • lower costs of trading
    • greater activity on UK trading venues.

    In this article I focus on three main areas – Exemptions, Flags and DRR.

    1. Exemptions

    The FCA was keen to expand on the list of transactions that are exempted from PTT reporting due to their non-price forming nature. The changing of conditions for when investment firms are required to PTT Report should simplify and lower costs. Article 13, RTS 1 lists the transactions exempt from PTT, adding noise to the market unnecessarily, but for consistency links to Article 2(5) of RTS 22.  Going forward, this list would include intra-group transactions, deemed non-price forming and which do not constitute addressable liquidity and are mainly used for the purpose of Risk Management (mirroring market conditions but not contributing to price). ‘Inter-affiliate transaction’ means a transaction between entities within the same group carried out exclusively as part of centralised booking for intra-group risk management purposes.”  The FCA would also streamline the overlap between Article 2, 6 & 13 of RTS 1.

    2. Flags

    The deletion of Pre & Post-Trade Transparency flags was proposed and has now been confirmed.  For post-trade this means the deletion of ‘SIZE’, ‘ILQD’ & ‘RPRI’ plus ‘ACTX’ & ‘DUPL’, taking into account the limited use of them today.  ‘ALGO’ will be maintained. Merging existing flags into one was discussed but ‘TNCP’ and ‘BENC’ will be maintained.  ‘CLSE’ has been introduced for Closing Prices and ‘PORT’ introduced to align with EU standards for Portfolio Transactions.

    The FCA highlighted that the removal of waivers would mean improved access to liquidity under the reference price waiver. In line with post-trade flags, there’s the aggregation of existing pre-trade flags ‘NLIQ’, ‘OILQ’ and ‘PRIC’ to ‘NETW’ for different types of negotiated trades.  A new flag will also be introduced for pre-trade large in scale ‘NTLS’, which has not been in place since MiFID II inception.

    It was noted that some of the pre and post trade flag changes will have an impact on fields 61 & 63 of Firms Transaction Reporting under RTS 22.

    3. DRR

    The proposal was to remove the SI status as a criterion in establishing when an investment firm is obligated to report a transaction. Under the DRR, firms could elect to register themselves as a designated reporter (DR) by notifying the FCA. A firm would be able to register as a DR regardless of its SI status. Registration would apply at entity level. This would mean DR status would apply to all that firm’s reportable trades across all eligible financial instruments. Where firms are trading with a non-DR, a DR would be responsible for reporting all trades. The seller would report where both, or neither, of the counterparties are a DR.

    Concerns were raised by some sell-side firms but the FCA clarified DRs can bilaterally agree, explicitly and in advance, which party shall fulfil the reporting obligation. The seller will always have the regulatory obligation to report but may discharge this by entering into an agreement with the buyer whereby the buyer agrees to report on its behalf. This option addresses the situation of having a reporting obligation but no arrangements to make the report public. DRR firms that wish to register as a designated reporter will need to submit a notification to the FCA. The FCA has said it will announce further details of this process in ‘due course’.

    Other points to note; the slight adjustments to the ‘Price’ field (numerical values only) ‘Price Currency’ field (incl. minor ccys) and the introduction of a new field called ‘Price Condition’ (already an existing FIX field but not published) to be populated with ‘PNDG’ when the price is not available at point of execution.

    Lastly, the FCA continues to highlight that it is developing the Consolidated Tape (CT) regime with the Treasury. The FCA intends to consult on this in the near future as part of work towards having a regulatory regime in place for a CT by 2024. A framework for CT will initially be for bonds but will have the scope to be built upon and adapted for equities.

    To summarise, the FCA post-Brexit consultation has been discussed for a while now and should not come as a surprise but there is still an impact on Investment Firms, (SIs & DRs) and APAs alike.  Careful consideration is needed on the Front Office IT development required and the understanding, across the market, of the DR responsibilities and communication with the buy-side.  Lots more to come and we hotly anticipate the non-Equities RTS 2 review in due course.

    • Read the full Policy Statement: Improving Equity Secondary Markets on the FCA’s website
    • For a conversation with Chris on any of the MiFID II Post-Trade Transparency Reporting matters raised above, please contact us.
  • FCA highlights lack of formal market abuse controls among some CFD providers

    FCA highlights lack of formal market abuse controls among some CFD providers

    What has the Financial Conduct Authority (FCA) said?

    In Market Watch 73, the FCA sets out its observations from its recent market abuse peer review into Contracts for Difference (CFD) providers. While the report was largely positive it did highlight some areas of weakness. In this blog we summarise some of its key findings and why the findings matter.

    The FCA observes that the surveillance of insider dealing is soundly covered compared to market manipulation, albeit further improvements could be made. The main concerns relate to firms not considering unrealised profits when determining whether insider dealing has potentially taken place.

    In comparison, it finds that the monitoring for market manipulation is weaker. Cross product manipulation was flagged as possibly on the increase, for example manipulating the underlying asset to profit from a related CFD or spread bet.

    ‘Narrowing the spread’ – a key area of weakness

    Although most firms were aware of ‘narrowing the spread’ behaviour, with some submitting suspicious transaction and order reports (STORs), no firms had listed this type of abuse in their risk assessments or had any ‘compliance-based’ surveillance to detect it. This behaviour is harder to detect when manipulation is conducted across multiple providers or via a dealing ring.  

    Two things can help here: communications surveillance tools can help identify different parties acting in concert and across markets. Secondly, the FCA can access MiFIR transaction reporting data to help detect such behaviour across firms. They also receive order level data covering the main UK equity markets.

    Lack of surveillance for non-equity asset classes

    Market Watch 73 also reports that most firms do not have effective surveillance for non-equity asset classes. Although a common and recurring theme over the years, firms still need to consider if insider dealing or market manipulation has occurred in retail derivatives referencing any asset class, not just equities.

    A tailored Market Abuse Risk Assessment (MARA) is key to helping identify market manipulation

    Some organisations lack a formal market abuse controls framework. Firms that undertake a Market Abuse Risk Assessment (MARA) can demonstrate that they are considering relevant market abuse risks. Furthermore, a tailored MARA is much more effective at identifying such risks.

    When conducting a MARA and building a surveillance framework, it’s important to consider:

    • All asset classes
    • Cross product and cross market manipulation
    • Trading activity in its historical context
    • Unrealised as well as realised profits
    • The different ways transactions are executed
    • How pre-trade activity (Orders, RFQs, IOIs) can manipulate prices and mislead market participants
    • The level of liquidity and pre and post trade transparency at instrument and market level
    • How electronic and voice communications are monitored
    • Keeping your MARA up to date!


    • Read the full Market Watch 73 on the FCA’s website
    • To learn more about Kaizen’s trade and communications surveillance solutions through our acquisition of Red Deer, please contact us.
  • Does your firm have an SMF for trade and transaction reporting?

    Does your firm have an SMF for trade and transaction reporting?

    The Senior Managers and Certification Regime (SM&CR) may be under review but that doesn’t mean it’s not still in place.

    The FCA and PRA recently published a joint discussion paper which asks for feedback on the operational aspects of the SM&CR.  At the same time HM Treasury also published a Call for Evidence seeking views on the legislative aspects of the regime.  This follows the announcement in December 2022 that there would be a review of SM&CR as part of the Edinburgh Reforms.  Responses to the discussion paper are due on 1 June.

    This could not come at a more crucial time for the industry with so much regulatory change afoot with expected divergence in MiFID II reporting, EMIR Refit upcoming, as well as various other rewrites concluding. 

    But in the meantime, we wanted to remind firms of their SM&CR responsibilities. Do firms have a Senior Management Function (SMF) in place for their trade and transaction reporting requirements, accuracy and approvals?  Who is your SMF16?

    SM&CR takes three key elements:

    • Senior Managers Regime – Understanding and mapping out of the SMF responsibilities and consequences of actions, personal accountability
    • Certification regime – Documenting, demonstrating, and certifying that SMFs are suitable and ‘fit & proper’ for the role, with annual assessments. “Have my SMFs been trained?”
    • Conduct Rules – Governance and documentation, procedures & policies that have been brought into line for SM&CR and controls in place for recording the implementations, steps and the decisions made by your firm to comply with the Conduct Rules across all staff within your organisation.

    Kaizen can help firms through the understanding of the accuracy of their regulatory reporting, so SMFs have a valued and independent view of their reporting.  We also provide governance and controls with our structured Control Framework services, designed by former regulators and our industry specialists experts, making sure internal GRC structures and procedures are acceptable.

    Only a few months ago, the FCA issued a Dear CEO letter to wholesale brokers reminding them of their regulatory obligations and to take proactive steps towards ensuring compliance, in particular highlighting that individuals in compliance risk personal liability when something goes wrong under the SM&CR.

    • If you’d like some help getting the right controls in place to ensure your firm meets the requirements of the SM&CR from regulatory reporting perspective, please get in touch.


  • UK gilt market crisis leads regulators to dig deeper

    UK gilt market crisis leads regulators to dig deeper

    Bank of England working paper underlines the importance of getting regulatory reporting right

    The Bank of England’s recently released working paper ‘An anatomy of the 2022 gilt market crisis’ reminds us why regulatory reporting is so crucial to the healthy operation of the financial markets.

    The paper, published in March, is a subject for further debate rather than a policy document. Nevertheless, the production of a 95-page document has clearly been prompted by a very keen interest.

    A quick recap – what happened last year?

    The Bank of England intervened on three separate occasions during September and October 2022 in order to maintain financial stability and prevent pension funds collapsing, following the Kwarteng/Truss ministerial statement, ‘The Growth Plan’ of 23 September 2022.

    The paper’s author identified such extreme concentration in the liability driven investment (LDI) pension insurance industry that just 3 firms were accountable for 70% of UK gilts they were forced to sell to primary dealers in the eye of the storm.

    Rapidly rising interest rates and inflation expectations at this time played havoc with the balance of assets and liabilities at these funds, particularly as real yields plummeted to new extreme negative levels.

    The demands of future pensioners necessitate real, rather than nominal returns, i.e. pension funds need to be able to lock in a certain level of future spending power for their members, irrespective of the future path of inflation. When you discount future liabilities with ever more negative real yields, those liabilities grow alarmingly.

    The LDI pension insurance industry faced the double whammy of significant bond market losses being compounded by margin calls on repo, inflation swap and OIS swap positions, meaning that they had to sell yet more gilts in order to cover these margin calls. Subsequently, the gilt market entered into something of a downward spiral, that it took BoE intervention to bring to a close. 

    What does this mean for regulatory reporting?

    On the first page of this working paper, the author places a quote prominently at the top of the page:

    “It was not quite a Lehman moment. But it got close.”

    (ref: Sep 2022, senior London-based banker).

    One of the outcomes of the last financial crisis was the additional regulatory reporting obligations that were placed on firms to ensure that both prudential and conduct regulators had sufficient transparency of derivative markets, securities financing markets and greater transparency of securities markets.

    This was achieved through the regulatory reporting regimes introduced post-crisis – EMIR, SFTR/MMSR/SMMD (financing & money markets) and a significant broadening of the MiFID transaction reporting requirements via MiFID II.

    These obligations allow regulators to quantify and respond effectively to the macro-systemic risks around solvency, market stability and concentration risks.  The Bank of England has been able to use this data; MiFIR RTS 22 transaction reporting (UK government bond, inflation linked and conventional ‘gilt’ markets), EMIR reporting (inflation & OIS swaps, UK gilt futures) and Sterling Money Market Daily (SMMD) reporting (UK gilt repo market) to produce this.

    Clearly, if the bank’s efforts were thwarted by low quality data stemming from firms’ transaction reports, the firms’ CEO and compliance officers would be the first to hear about it in no uncertain terms! Any reporting errors could lead to costly audits or investigations and potentially substantial fines and reputational damage. Firms need to ensure they have robust controls and procedures in place, including how accurately they report under these regimes.

    • Read the full working paper on the Bank of England’s website
    • If you have concerns about the quality of your transaction reporting under any of the regimes referenced in this blog or for a conversation with Jonathan Lee. Please contact us. 


  • UPDATED: A tale of inflation, solvency & regulatory jeopardy

    UPDATED: A tale of inflation, solvency & regulatory jeopardy

    We first published this article in November 2022 but given current market events, we’re republishing it this week with some updated opening paragraphs. 

    There is a common perception in securities trading that getting the timing right when taking positions in the market is far more difficult than having the right idea to begin with. In hindsight, the below blog, written in November 2022, was a classic example of this. Regulatory concerns I raised five months ago in relation to rising interest rates, badly positioned market counterparties, bond market losses, capital adequacy, solvency issues and fears of contagion were well placed, but four months too early…

    In a similar manner to government preparations for a flu pandemic in 2020, following the 2008-2011 financial crisis, regulators were well prepared for a series of credit events. Unfortunately, the pre-cursor to the current situation is not a credit event but an interest rate event, for which preparations are far less appropriate, regulators simply find themselves looking in the wrong direction. Regulators will be quantifying counterparty exposures, collateral concentrations, leverage, levels of collateralisation and evidence of any further systemic risks. The principal tools for identifying these risks include SFTR, MMSR, SMMD and the likes of PRA Liquidity Reporting. If this data is poor, regulators will be active in their response. For a conversation about your data quality, please contact us.

    ***

    21 November 2022

    The deflation that followed rapid Chinese industrialisation has kept interest rates on a declining and ultimately stagnant path for decades since the 1990s.  In recent years, interest rate and government bond markets could have been politely described as being as dull as ditch water.

    However, as with all things in the market, the trend is your friend, until it isn’t…

    UK Treasury 2050, 0 5/8% Bond Price – theoretically one of the safest investments…

    Source: London Stock Exchange


    Supply chain and booming inflation

    Supply chain issues stemming from Covid, compounded by the emergence of China as a new superpower with massive domestic consumption and to a lesser extent Brexit, saw the price of the long dated UK Gilt (above) dip from around 100 (or par) into the 80s in February 2021. This c.20% fall in value accelerated as war broke out in Ukraine in February 2022 resulting in a dramatic jump in global inflation, with central banks increasing official interest rates in an attempt to ensure that this inflation is transitory. The downward trajectory in UK bond prices troughed with the fallout from the misguided September UK mini-budget on 8 October 2022 when the price hit 36.40 – a fall of 64% in the 2050 Gilt price from its high to low.

    Rates markets have become sexy again

    Higher interest rates, volatility, differing views on inflation expectations all of a sudden bring bond markets, money markets and securities financing markets back into sharp focus. While this may be to the delight of rates traders, it will have been highly unwelcome by the pensions industry as the value of many of their key ‘low risk’ assets are needed to service pensioners of the future evaporated. The moves were so dramatic, some pension funds’ solvency was called into question, resulting in intervention by the Bank of England to support the Gilt market in October.

    What does all this mean for regulatory reporting?

    Central banks and regulators will be on heightened alert to identify large interest rate exposures, the effective transmission of official central bank interest rates, solvency issues, credit default risk and the potential for contagion. Trade and transaction reporting regimes are among their principle means of performing this supervisory oversight and analysis. This will encompass everything from MiFID, SFTR, EMIR, MMSR, SMMD, CFTC, FinfraG, SESTA and many more besides. When faced with something of a crisis or an emergency situation, there is a risk that regulators need to react quickly with punitive measures if their investigative work is thwarted by reporting data quality issues.

    Enforcement has been notable in its absence for a number of years, just don’t be too surprised if this now goes the way of the bond market.         

    • If your money markets reporting (under SFTR, MMSR & SMMD), your bond market transaction reporting (under MiFIR) and your interest rate derivatives reporting (under EMIR, CFTC, MAS & HKMA) is not in perfect order or you are unaware of how good (or bad) it is, please get in touch.
  • Join us at the EUREX Derivatives Forum 2023 in Frankfurt

    Join us at the EUREX Derivatives Forum 2023 in Frankfurt

    Join the Kaizen and Single Rulebook teams in person at the EUREX Derivatives Forum Frankfurt 2023 on 22-23 March.  The event will take place at the Congress Center Messe Frankfurt and will also be available virtually with thought leadership insights, industry debates and keynote speeches, focusing on trading and clearing for derivatives and securities financing across asset classes.

    We will have an exhibition stand, so please come and say hello!

    To register, follow the link below and enter the following token: Kaizen-DFF

    Register here


  • WATCH: MiFID II Transaction Reporting Valid but Wrong errors

    WATCH: MiFID II Transaction Reporting Valid but Wrong errors

    What types of errors is Kaizen able to detect with our Accuracy Testing platform? We call these ‘valid but wrong’ errors.

  • WATCH: Kaizen client conference 2023 highlights

    WATCH: Kaizen client conference 2023 highlights

    Watch this video to see highlights of our Kaizen client conference ‘Regulatory Reporting – where are we now?’ at Banking Hall in the heart of the city of London. 

    More than 180 clients, staff and industry experts joined us for an afternoon of all things regulation and reporting. 

    We were delighted to host the FCA’s Markets Reporting Team Manager Tom Soden as the keynote speaker, as well as speakers from HSBC, DTCC, FIA, and our very own Advisory Board and subject matter experts. 

    Panel discussions included:

    • The current regulatory landscape
    • Data quality and the drive to improve it
    • Regulatory reporting in 2023 and beyond.

    A huge thank you to everyone who took part in or attended the event and we look forward to seeing you next year.  For suggestions for topics you’d like us to cover, please get in touch. 

  • EU’s legislative procedure steps up the pace on revised MiFIR and MiFID II

    EU’s legislative procedure steps up the pace on revised MiFIR and MiFID II

    Matthew Vincent takes a look at what we might expect to see in the revised EU MiFIR Article 26, “Obligation to report transactions”.

    After many months of discussions starting from ESMA concluding its EU MiFID Review, the EU Parliament has caught up with the EU Council and has reached its own negotiating position on amendments to MiFID II and MiFIR.  We have now reached the “trilogue” stage during which time the Commission, Council and Parliament will work to agree on the final wording of the legislative text. Trilogues are set to commence in April and we expect to see the final legislative changes agreed during Q3 2023.

    Level 1 agreement though is only the start, as ESMA will consult and draft an amended RTS 22 before we really know all the details and the impact on firms.

    That said, a comparison of the two “negotiating” versions of the Level 1 texts gives us some idea of where we’ll likely end up by Q3.

    1. The short selling flag seems very likely to be removed as it has been removed from both versions.  
    2. The reporting obligation will probably be extended to derivatives “subject to the clearing obligation set out in Article 4 of Regulation (EU) No 648/2012 executed outside a trading venue.”
    3. Powers may be granted to ESMA to assess the possibility of extending the reporting obligation to include AIFM and management companies.
    4. The problems associated with TvTIC will probably not all be solved by its promotion to Level 1
    5. ESMA is also instructed to draft regulatory technical standards to specify:
    • The conditions for linking specific transactions and the means of the identification of aggregated orders resulting in the execution of a transaction.
    • The date by which transactions are to be reported.

    As always, the devil will be in the detail of the RTS and perhaps a revised set of guidelines will also be forthcoming.  But for now at least we can get ready to say farewell to the short selling requirements and do our collective best to avoid the temptation to say “we told you so”.

    • For a conversation with Matthew on the upcoming changes to EU MiFIR, please get in touch.
  • Kaizen Reporting acquires majority stake holding in London Reporting House

    Kaizen Reporting acquires majority stake holding in London Reporting House

    Tuesday 7 March 2023 – Leading regulatory technology firm, Kaizen Reporting today announced that it has acquired a majority stake in London Reporting House, a new service that brings unrivalled insight into the repo market.

    London Reporting House’s platform anonymises, aggregates, enriches and analyses raw SFTR trade data from multiple sources to provide unprecedented views over, and depth into, the EU and UK repo markets. There are six key elements to London Reporting House’s offering which provide clients and market participants with analytics and metrics on GC repo curves and spreads, specials, collateral haircuts and prices, flows of new transactions and open interest.

    The new London Reporting House products and analytics tools will be available via the Kaizen Hub, a web based RegTech platform for accessing a range of compliance tools.

    Dario Crispini, CEO of Kaizen Reporting, commented: “Our partnership with London Reporting House shows our commitment to expanding the services we can offer our clients.  It also highlights our belief in the expertise and creativity that Danny and Richard [Danny Corrigan: CEO and Co-founder and Richard Comotto: Head of product and Co-founder at London Reporting House] bring to LRH and the products they are building at LRH.  The products they are creating provide invaluable information for trading and risk teams at a time when financial institutions are looking for enhanced transparency and data across all markets.”

    Danny Corrigan, CEO and Co-founder, London Reporting House, commented: “We are delighted to be a part of Kaizen and by joining forces we are able to enhance our offering and build out our platform which leverages Kaizen’s IT infrastructure and legal framework for onboarding. Bringing their expertise and technology together with ours, we are able to offer the repo market a unique service that creates a transparent and deep view of the UK and EU repo markets.”

    The terms of the acquisition were not disclosed.

    (ends)

    About London Reporting House

    London Reporting House was founded by a team of repo specialists who saw an opportunity to bring a new level of transparency to the repo markets. Having access to granular, detailed and timely data is invaluable for making superior investment decisions. London Reporting House’s repo analytics tools provide a deep and granular view of the market for front and back-office functions across the industry. Our products and analytics tools are available via the Kaizen Hub, a web based RegTech platform for accessing a range of compliance tools.

    www.londonreportinghouse.com

    • For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com
  • MiFID II reporting five years on: The future of post-trade transparency reporting

    MiFID II reporting five years on: The future of post-trade transparency reporting

    MiFIR trade & transaction reporting was five years old in January. In the third of our blog series on MiFIR, Chris Machin reviews what’s ahead for MiFIR post-trade transparency reporting in Europe and the UK.

    As mentioned by Simon Appleton in part two of this blog series, there has been significant focus on post-trade transparency (PTT) reporting in the last year by both the FCA and ESMA.

    Since the foundations of MiFID II were put in place in 2018, the main area of consternation has been RTS 2 non-equities (rather than the vanilla RTS 1 equities). Leading up to go-live, the industry had been clear that bracketing all non-equities into one RTS wouldn’t work. If we could start again, segregating out OTC derivatives from bonds and the other asset classes would be essential. Five years on, this debate still painfully rumbles on.

    What we are now seeing post-Brexit, is an interesting mix of divergence and convergence from the UK and EU regulators, with a common debate around liquidity vs transparency.

    ESMA issues positive opinion on amended RTS 1 and 2

    ESMA loves to share an update just before a holiday season and so it did just before Christmas 2022, confirming its support for the European Commission’s proposed amendments to the regulatory technical standards on RTS 1 and RTS 2. The amendments are an attempt to establish increased transparency, strengthen data integrity and availability, and create a level playing field. However, it should be noted that this was the same mandate and message used more than five years ago when MiFID II went live in January 2018.

    So, is anything actually changing? And is ESMA’s approach in line with the potential changes announced by the FCA in its post-Brexit consultation paper earlier last year?

    Liquidity vs transparency

    Liquidity vs transparency, as mentioned earlier, is still the burning argument. By increasing transparency, will this improve liquidity?  A consolidated tape has been proposed since 2014 as consolidated tape providers (CTPs) were listed amongst approved publication arrangements (APAs) and approved reporting mechanisms (ARMs) as data reporting service providers (DRSPs), but none have materialised to date. It’s complex. The industry sees shares and bonds in scope for consolidation, but the complexity of OTC derivatives is still a derided topic, with trade associations like ISDA at the forefront of lobbying what members are saying. Is a derivatives tape needed? There’s also the terminology of MiFIR Article 13 and ‘reasonable commercial basis’. How do the exchanges and APAs feel about this when data sales are a big revenue driver for them?

    Dark pools/trading

    Limitations on dark trading and moving to a single volume cap have been discussed and in practice for a while. But ESMA’s latest update demonstrates how it is diverging from the UK.  ESMA is trying to increase transparency with the aim of encouraging trading on lit markets, by keeping the cap in place, whereas the UK is trying to increase liquidity by reducing these restrictions and pulling back the liquidity that was lost when the UK exited the EU.

    Clarity on transparency fields

    Clarity on transparency fields is welcomed although the somewhat ambiguous ‘price’, ‘quantity’ and ‘notional amount’ are not always relevant, depending on the asset class being traded. More clarity is required on defining non-price forming transactions and deferrals aside, however it will be interesting to see how 2023 plays out.

    FCA’s update on MiFIR transparency

    ESMA’s opinion still needs to be negotiated through the European Parliament and it is likely the new ‘Manual’ described in the guidance, will replace or co-exist with the transparency Q&A, whereas in the UK, HM Treasury has given the FCA the power to change the rules accordingly.  

    With the FCA, we know the share & derivatives trading obligations (STO & DTO) have to change as the statements from the respective articles 23 and 28 in the regulation no longer apply now the UK has segregated. Traded on a Trading Venue (ToTV ) is questionable but the biggest draw may be the delineation of the systematic internaliser (SI) regime from the reporting responsibility.  It seems that this responsibility will be at entity level which still brings uncertainty around communication of status between SI and the Non-SIs and buy-side.  A central evergreen source is needed, something like Smartstream RDU’s SI register which was made available in preparation for 2018.  This was crucial to market participants and APAs alike on the identification of who has the publication obligation, given RTS 1 and 2 post-trade transparency reporting is single-sided.

    Though trying to achieve extra transparency, the regulators need to keep one eye on creating undue risk in the market to those that are providing the much needed liquidity. On the UK side, there is mention of change in deferral flags, providing more precise information and less ambiguity, but caution should persist. RTS 1 and 2’s goals were OTC price transparency, level playing fields, and encouraging investor confidence, whilst reducing investor risk and allowing informed investment decisions for all. If the FCA and ESMA keep this in mind as 2023 progresses, taking on the feedback from the industry, the battle of liquidity vs transparency could harmonise into achieving both, a match made in heaven!

    • For a conversation with Chris about the upcoming changes to RTS 1 and 2 requirements or a free healthcheck of your MiFIR post-trade transparency reporting, please contact us.
  • MiFID II reporting five years on: what does the future hold?

    MiFID II reporting five years on: what does the future hold?

    MiFIR transaction reporting is five years old this month. In the second of a three-part blog series on MiFIR, our reporting director Simon Appleton looks ahead at some of the upcoming changes expected in Europe and the UK.

    Status check

    Five years after MiFID II’s implementation and nearly three years after Brexit, the EU and UK transaction reporting regimes are under review.  Both regimes are generally working well hence, in the UK for example; other parts of MiFID appear to be being assessed with a greater sense of urgency, such as Post-Trade Transparency.

    Transaction reporting data quality has improved steadily over the last five years, albeit accuracy levels vary greatly across firms, asset classes and data fields. Firms conducting deep, regular testing have seen reporting standards improve significantly and those with robust control frameworks have seen the greatest progress.

    However, the fact that only a third of the investment firms reporting under UK MiFIR have requested data via the FCA’s Markets Data Processor, confirms that two-thirds (over 850 UK MiFID investment firms), are at risk of being in breach of their reporting obligations.

    Pre-MiFID an independent review established that there is no viable alternative to transaction reporting that would allow regulators to monitor investment firms and markets effectively. Regulators are increasingly describing themselves as being data-led and so clearly the receipt of accurate, complete and timely reports has never been so crucial.

    MiFID transaction reporting in the UK

    Given that the rules were implemented five years ago, the FCA is reviewing its policy options to ensure that the reporting regime is not only effective but also efficient for firms and that the requirements are not disproportionate when compared to the benefits. They will be aware of the impact of divergence from EU MiFIR but will also want what works well for UK firms and the FCA.

    The FCA will be very considered in its approach to reviewing the transaction reporting requirements. This will allow it to determine which parts of the regime need to be updated, taking into account feedback from industry, as well as experience gained since 2018. 

    Which aspects of the technical standards, guidelines and Q&A require amendment or additional clarity and guidance for firms? Areas such as corporate actions and the reporting of swaps are ripe for review.

    In addition, before considering when to engage with industry, the FCA needs to absorb the UK Treasury’s:

    The Treasury’s policy statement for “Building a smarter financial framework for the UK” and Edinburgh Reform plans were both only published last month, so the publication of the FCA’s transaction reporting discussion paper (DP) may be some way off.

    Areas of likely change in the UK

    • Removal of the Securities Financing Indicator: the requirement to report securities financing transactions (SFTs) under UK MiFIR ceased with effect from 31 March 2022 and so this field is effectively redundant
    • Changes to the OTC Post-trade indicator: Given the UK Treasury’s Wholesale Markets Review it is highly likely that there will be changes to the applicable values for this field
    • Removal of the Short Selling Indicator: Given previous communication from the FCA, it would be highly surprising if they did not follow ESMA’s lead and remove the Short-Selling Indicator
    • OTC derivatives and crypto: The reporting scope for OTC derivatives is to be considered, as will the development of Unique Product Identifiers (UPIs), which could help resolve issues with the use of ISINs. Crypto-related instruments could form part of the discussion given the expected greater scrutiny on these
    • Cross-regime alignment: The UK Treasury is keen to understand where overlaps lie between MiFID II and EMIR reporting and where different reporting formats are used. Given the significant differences between the two regimes as to what constitutes a reportable event or valuable information, it’s anticipated that the use of consistent and international data standards, reportable values, formats and methodologies is where further efficiencies can be made. MAR and Benchmark Regulation are both likely to form part of the cross-regime analysis
    • ESMA’s proposals: The FCA will consider which proposals from the EU’s review (below) will form part of the forthcoming discussion paper.

    EU review of MiFID transaction reporting

    ESMA’s proposals for changes to transaction reporting under EU MiFIR were published back in March 2021 and so the EU’s review is much further advanced than the UK’s. As a reminder, the headline changes include:

    • AIFMs and UCITS management companies providing one or more MiFID services to third parties will be required to transaction report for the first time
    • Replacement of the “Traded on a Trading Venue” (ToTV) commonalities concept with a simplified “SI approach” for determining whether an OTC derivative is reportable
    • A new field, a Buy-back Programme flag, to identify trades in buy-back programs conducted on behalf of an issuer
    • Introduction of a MiFID client categorisation flag, to identify whether the transaction was for a professional, opted-up professional or retail client.
    • Replace ‘INTC’ with a unique code to the reporting firm when aggregating orders across more than one client
    • Removal of the Short Selling Indicator.

    In December 2022, the EU Council announced that it had voted in favour of final compromise amendments to the commission’s MIFID II and MiFIR proposals in the EU MIFID Review. The texts will represent the council’s negotiating position for trilogues, which are expected to commence around Q2 2023 (as the European Parliament is still working towards its final compromise position in Q1).  

    The MiFIR Article 26 level 1 text, dated 16 December 2022, was published on 21 December 2022 and includes reference to other additional information, for example, the due date for the transaction report, which could prove challenging for firms in certain scenarios. The short-selling flag has indeed been removed and a new designation for aggregated orders has been included.  For the detail though, we will have to wait for the revised RTS 22.

    Estimated timelines for implementation are contained within a recent Kaizen blog.

    Focus on data quality

    Regulators, both in the EU and the UK have frequently stated the importance of accurate reporting to support them maintain clean and orderly markets. They remain unlikely to look kindly on a firm when either mis-reporting has hampered a market abuse investigation, or where they fail to act upon observations made by regulators, either through general communications (e.g. Market Watch newsletters) or through those made directly to firms. 

    It’s now nearly 30 years since the Investment Services Directive and 2023 looks likely to be a busy year as ESMA’s MiFIR review leads to its legislative conclusion and the UK FCA digests the impact of the government’s reforms.

    Read the first part of this blog series MiFID II reporting five years on: a retrospective.

    • We at Kaizen will stay on top of any developments and continue to work with new and existing clients to detect and remediate their reporting issues. 
    • For conversation with Simon about anything raised in the commentary above, please contact us.
  • Help Kaizen win at the Hedgeweek European Awards 2023

    Help Kaizen win at the Hedgeweek European Awards 2023

    Help us win at the Hedgeweek European Awards 2023 where we have been shortlisted for two awards:

    Best Outsourced Solution

    Best Regulatory Reporting Solution

    The Hedgeweek European Awards 2023 recognise excellence among fund managers and service providers in Europe across a wide range of categories. Voting closes Monday 23 January 2023.

    All you need to do is follow the link below, fill in your details and select yes for question 9, and select Kaizen Reporting for questions 41 and 53.  And press submit! 

    A huge thank you in advance for your support. 

    Vote here


  • MiFID II reporting five years on: a retrospective

    MiFID II reporting five years on: a retrospective

    MiFIR transaction reporting is five years old this month. In the first of a three-part blog series on MiFIR, Kaizen’s regulatory subject matter expert Matthew Vincent looks back at the origins of the regulation and some of the significant changes that have occurred since go-live.

    Let’s start with some positives. The additional data captured by MiFIR transaction reporting has improved regulators’ ability to monitor and detect for market abuse whilst firms have made significant efforts to get their reporting correct and remediate mistakes of the past.

    On the flip side, whilst the regulation may have harmonised reporting requirements which was positive for the industry, differences of interpretation still arise which could potentially be resolved more quickly. In addition, the changes and centralisation have resulted in a loss of flexibility and responsiveness to change. 

    There is no doubt that the industry has congratulated regulators for their efforts in producing the reporting guidelines however, as experience has shown, you can never quite find a guideline that matches the exact scenario that you are trying to report.

    Why transaction reports?

    For UK and EU regulators transaction reports are essential to allow them to monitor for market abuse and maintain orderly financial markets. Without reports regulators would be blind to any market abuse that might occur.

    “Accurate and timely reporting of transactions is crucial for us to perform effective surveillance for insider trading and market manipulation in support of our objective to ensure that markets work well and with integrity.” – FCA, April 2015

    Transaction reporting within the European Economic Area (EEA) can trace its history back to 1993. Since then, the obligation on firms has steadily increased with MiFID I introduced in November 2007 and MiFID II/MiFIR in January 2018.

    How was MiFIR different to previous reporting obligations?

    The obligation to report and the details to be reported were incorporated into a regulation not a directive, limiting the ability of member states to implement different rules.  Some interpretation differences arise although these are subtler than historically.   

    • The data to be reported increased from 24 fields to a maximum 65 fields
    • The scope of reportable instruments was broadened to include ‘over the counter’ derivatives and certain derivatives over FX, commodity and interest rates.
    • Data quality checking and reconciliations became legally mandated in RTS 22, Article 15. 
    • ESMA produced guidelines and Q&As to assist firms with implementation of the regulation.

    What’s changed since January 2018?

    ESMA Q&A on MiFIR data reporting

    The document predates MiFIR go-live with the first question answered April 3 2017.  A further 13 questions have been answered with the latest in September 2020.

    ESMA validation rules – valid but wrong

    The validation rules are designed to improve the quality of the data received.  There have been five versions with incremental changes made over the course of the five years.  All until version 1.5 were applicable to both UK and EU regulated firms.  Versions 1.6 and 1.7 have been optional for UK regulated firms and UK ARMs alike. 

    However, validation rules can only go so far in improving data quality.  The validation rules capture approximately 400 data quality issues. Regulators have stressed that passing validation is not the only way a firm should validate its data quality.  Our comprehensive quality testing demonstrates that there are many more ways of reporting valid but incorrect data.

    “Firms should not assume that a report was accurate because it was accepted by the Market Data Processor, as business validation rules are not intended to identify all errors and omissions.” – FCA Market Watch 59 (April 2019)

    “The CSSF continuously monitors the quality of the transaction reporting data. During the last year, the CSSF not only carried out the standardised quality tests developed together with the other competent authorities and ESMA, but also conducted a series of data completeness and quality enhancement campaigns.” CSSF, February 2022

    Data Reporting Services Providers (DRSP) regime 

    Immediately post MiFIR go-live, Approved Reporting Mechanisms (ARMs) were supervised by their National Competent Authority (NCA).  On 1 January 2022, ESMA took on its new mandate as direct supervisor and now supervises firms that represent almost 99% of the transactions reported by an ARM.

    This is unlikely to have an immediate effect on firms – although there have been some concerns raised about the additional costs of this supervision. But in time this should further harmonise the implementation of the regime across member states in the EU.  UK ARMs are still supervised by FCA. 

    Brexit – limited impact so far 

    So far, the impact of Brexit on reporting firms has been limited. For example, UK nationals must now be identified using their passport numbers when a report is made to an EU competent authority – yet should still be identified using the National Insurance number when a report is made to the FCA. Other alterations have had to be made as the status of UK venues has changed, when reporting to the EU and that has impacted the way in which certain fields should be populated, TVTIC, Pre-Trade Waiver and Country of Branch Membership.  A more significant change has been to the ‘in-scope instruments’ with the introduction of UK FIRDS, and the most recent change that came into effect on 30 December 2022 are the changes to the exempt securities under the UK short selling regulation. 

    Supervisory priority

    The only significant supervisory change was made by the FCA on 13 January 2022 when the regulator announced it was in the early stages of considering policy options for the UK reporting regime which included the future of the short selling indicator.  

    “Until the future of the short selling indicator field…has been determined, we will not take action against firms who do not meet these requirements. We do not expect firms to notify us about issues affecting the short selling indicator field through an errors and omissions notification form. We will keep this position under review.” – FCA, January 2022

    Validation rule – January 2023

    This month’s five year anniversary is marked by the awakening of validation rule – 269 which states the trade date cannot be earlier than five years before the submission date. Where this is the case, reports will not be accepted by the NCA and the firm will receive a CON-281 rejection.  Hence, firms will no longer be able to correct some mistakes of the past.

    What hasn’t changed at all?

    ESMA’s table thumping Guidelines – Transaction reporting, order record keeping and clock synchronisation under MiFID – has been the go-to place for firms seeking guidance for their implementations. It is somewhat surprising that there hasn’t been a single revision to any one of its 291 pages since it was last corrected on 7 August 2017.   

    Some final thoughts

    Fields like TVTIC and the short sell indicator have been difficult to implement, and we expect some of these issues to be addressed in the next iteration of the regulation.

    In our second blog in the series Simon Appleton will look ahead at the changes to MiFIR reporting we are expecting to see this year and beyond.

  • Join us at the Asset Management Derivatives Forum 2023 in California

    Join us at the Asset Management Derivatives Forum 2023 in California

    Join the Kaizen team in person at the eighth Asset Management Derivatives Forum, hosted by FIA and SIFMA in California on 8-10 February 2023. The conference will take place at The Ritz-Carlton, Laguna Niguel in Dana Point, California and offers a comprehensive review of the most critical derivatives issues across a series of panel discussions, keynote addresses and roundtables.

    We look forward to seeing you there.

    Register here

  • What’s the latest with ESMA’s MiFIR Reporting Review?

    What’s the latest with ESMA’s MiFIR Reporting Review?

    In this blog we look at what’s happening with MiFIR Reporting in Europe and what we can expect to see in 2023 and beyond.

    Under the mandate granted by MiFIR Article 26(10), ESMA shall submit a report to the Commission on the functioning of Article (26); a consultation on MiFIR began 24 September 2020 and the conclusion summary report was released on 23 March 2021.

    The report contains recommendations and possible legislative amendments to MiFID II/MiFIR to simplify the current reporting regimes yet maintaining the quality and ensuring the usability of the reported data.

    The headline changes are as follows:

    • Replacement of the TOTV concept with the SI approach for OTC derivatives, bearing in mind the conclusions of ESMA’s Final Report on the transparency regime for non-equity instruments and the trading obligation for derivatives
    • Removal of the short sale indicator
    • Alignment with other regulations e.g., MAR, EMIR and the Benchmark Regulation
    • The reliance on international standards, including LEIs, ISINs and CFIs; and
    • The inclusion of three additional data elements to harmonise the way that they are reported and to avoid inconsistent and duplicative reporting.  In particular, these are indicators for:
      • Buyback programs
      • Information on MiFID II client categories
      • Transactions pertaining to aggregated orders.

    You can read Kaizen’s FAQ on the changes here or watch our webinar, ESMA’s MiFIR Review – what does it mean for transaction reporting? here.

    Distributed Ledger Technology (DLT) pilot

    Meanwhile in response to the rapidly changing landscape across Europe for the trading and settlement of ‘tokenised securities’, ESMA conducted a call for evidence earlier this year. ESMA released its conclusions on the DLT Pilot Regime and its impact on the regulatory technical standards (RTS) developed under MiFIR relating to certain pre- and post-trade transparency and data reporting requirements. The regulation, which is on a pilot regime for market infrastructures based on DLT, (‘the DLT Pilot’) aims to develop the trading and settlement for ‘tokenised’ securities. The DLT Pilot entered into force on 23 June 2022 and will start applying on 23 March 2023.  ESMA conducted a call for evidence from 4 January 2022 to 4 March 2022 in order to seek feedback and on September 27, ESMA released this feedback received and included proposals for the way forward.

    The conclusions of that report will have been greeted as good news for firms and infrastructure providers in that “ESMA does not consider it necessary to amend the RTS” now, however it will work on supervisory guidance clarifying the application of certain elements of the RTS and experience gained during the pilot will be considered during any MiFIR review.

    So where are we on the ‘ordinary legislative procedure’ timeline?

    EU Commission amendments to MiFIR and MiFID II were the output of the MiFID II review that was carried out, as mentioned above by the EU Commission. The consultations were wide ranging and Commission proposals for the amendments are subject to the ‘ordinary legislative procedure’ which means the European Parliament and the Council negotiate a final legislative text on the basis of the Commission’s proposals. The EU legislative procedure usually takes approximately 18 months.

    The Commission’s proposals were published towards the end of last year (2021) so we are coming towards the end of the legislative procedure.

    The European Parliament has published its amendments and the Council has drafted its own compromise proposals. More discussion is needed to finalise their respective positions before trialogue can commence.

    What happens next?

    If the European Council and Parliament reach a compromise by the end of December 2022 and Q1 2023 respectively, then trialogues between the European Commission, Parliament and Council will follow before a final position is agreed – maybe by Q3 2023. 

    Legal language review and translation will then take place before the final changes to MiFIR and MiFID II can be published in the Official Journal. Based on the timings above, we could anticipate that this will be sometime in the last quarter of 2023.

    The changes to MiFIR are likely to apply 21 days later and changes to MiFID II will need to be implemented in member states within 12 months. Changes to underlying RTS will also be required. 

    What can we expect to see in 2023?

    Change to MiFIR itself is likely to be fairly limited vis a vis Article 26 with most of the detail once again to be found in the amendments ESMA will make in Level 2.

    Looking back at history is no guide to the future, as the final MiFIR and MiFID II texts were published in the Official Journal of the EU on 12 June 2014 and entered into force 20 days later on 2 July 2014. Entry into application was supposed to follow 30 months after entry into force on 3 January 2017. This of course was delayed until 3 January 2018. 

    It’s unlikely to take that long this time around as the scale of the change is significantly smaller than the changes under MiFID II. Assuming that there is no major derailment in the political negotiations, ESMA is likely to produce consultation and discussion papers setting out its proposed advice to the Commission on changes to the RTS and ITS, with implementation during 2024. 

    We will be watching this space and will update you further as progress is made. 

    For a conversation with Matthew or one of our regulatory specialists about the upcoming changes to MiFIR or how to prepare for regulatory change, please contact us. 

  • FCA releases Market Watch 71

    FCA releases Market Watch 71

    In today’s Market Watch 71, the Financial Conduct Authority (FCA) has taken the opportunity to highlight to firms the importance of compliance with obligations laid out in the UK Market Abuse Regulation (MAR) to include personal information in insider lists. The regulator also reiterates the importance they attach to firms maintaining accurate insider lists and reducing access to inside information to employees to prevent market abuse.

    Insider lists

    The newsletter draws attention to firms that have provided insider lists in response to regulatory requests which do not contain personal information. The lists should include telephone numbers, dates of birth, and national identification numbers. The FCA uses this data to cross reference the information with MiFIR transaction reports, MAR suspicious transaction and order reports and other information sources. Without accurate and complete information, the FCA’s ability to review potentially suspicious trading is hindered. Firms are reminded that insider lists must be in the format and include the information set out in the UK version of Implementing Regulation (EU) 2016/347 and that these technical standards are legally binding.

    Personal identifiers

    Personal information is also required in firms’ transaction reports and must be used to identify the ‘investment decision maker’ and ‘execution decision maker’ (i.e. a firm’s employees), whilst also being used to identify clients of the firm who are natural persons and where applicable, the client’s decision makers. The same standards are used for completing the details provided in ‘insider lists’ and a firm’s transaction reports. These are found in Article 6 of RTS 22. The FCA reminds firms that the first priority national identifier for UK nationals is the national insurance number when reporting to the FCA, and of course the passport number when reporting UK nationals in the EU. Read our recent blog on this topic.

    Getting these identifiers correct in a transaction report is clearly important to the FCA as it has reminded firms of their duty to get this right several times. In both Market Watch 59 and 62, it highlighted that first priority national identifiers must be used wherever available to identify natural persons in transaction reports. Again the FCA mentioned this obligation in October’s Market Watch 70.  The regulator stressed the need for firms to capture this information correctly at onboarding and drew attention to firms who offer services to retail clients electronically, as being particularly weak in this area.

    Important for all NCAs

    Correctly identifying individuals is important to all national competent authorities in Europe and they all have similar duties to the FCA in monitoring for market abuse. 

    The CSSF in Luxembourg stressed the importance it attaches to this field in a notice to firms in February this year and highlighted the following failings:

    • Use of CONCAT code for nationals where this code is not allowed
    • The CONCAT code was not used for nationals where it is the only possible identifier
    • Use of an identifier for non-EEA nationals other than the National Passport Number or CONCAT code
    • The CONCAT code is not correctly constructed when compared with the other personal data provided in the report
    • The national identifiers provided in the transaction reports do not comply with the format as described in ESMA’s Q&A on MiFIR data reporting.

    Clearly getting the personal identification correct within reporting is very important to regulators allowing them, borrowing British television presenter Shaw Taylor’s phrase, to ‘Keep ‘em peeled’, in their efforts to keep markets clean. And perhaps equally important to individuals keeping on the right side of MAR, correct identification allows regulators to quickly ‘eliminate people from our enquiries’.

    • Read Market Watch 71 on the FCA’s website. 
    • For a conversation with Matthew about the topics above, or how Kaizen can help you achieve accurate and complete transaction reporting, please contact us. 
  • Transaction Reporting How-to Guide: Personal Identifiers

    Transaction Reporting How-to Guide: Personal Identifiers

    The FCA recently released Market Watch 70 providing a reminder to firms of the importance it attaches to the transaction reports it receives.  Transaction reports are used to help them detect and investigate cases of market abuse, combat financial crime, support conduct supervision and examine market events.  For the regulator to be able to do that efficiently, reported data must be complete, accurate and sent on time.

    Despite MiFIR heading for its 5th birthday in January 2023, Kaizen’s testing is still finding a high number of personal identifier errors within transaction reporting, something also highlighted in Market Watch 70:

    • Buyer/Seller identifiers
    • Buyer/Seller decision maker identifiers
    • Investment decision within firm
    • Execution within firm

    These codes are essential to regulators for their work in detecting market abuse.  Harmonisation of the population of this field is vital for regulators attempting to identify individuals insider dealing through several trading accounts held at a number of different firms.  Regulators can only attempt to detect such activity if all the firms use the same and correct code to identify these unscrupulous types. 

    Personal Identifier Essentials

    The first thing to remember is that all personal identifiers start with the ISO two character country code of the individual’s nationality (e.g. ‘GB’, ‘US’, ‘FR’ etc.) followed by the national identifier relevant to that country.  Kosovo being the one outsider here in that it doesn’t have an official ISO-3166 code but its unofficial “XK” is now being recognised by competent authorities.

    National identifier taxonomies

    A list of the national identifier taxonomies can be found in the RTS 22 Annex.  For some countries, there is a single taxonomy; for example, for German nationals, only the ‘CONCAT’ can be used. For other countries, there are up to three taxonomies.

    In all cases you can only use the ’Priority 2’ taxonomy if the ‘Priority 1’ taxonomy is not applicable to that individual.  For example, the ‘Priority 1’ taxonomy for UK individuals is the National Insurance Number (NINO) and priority 2 is ‘CONCAT’.  So if you are identifying a British person, you should only use a ‘CONCAT’ if that person does not have a National Insurance Number.  In theory every British person over the age of 16 is issued with a National Insurance number so for the purposes of transaction reporting you should not be identifying any British person over the age of 16 with a CONCAT code.

    What is ‘CONCAT’?

    ‘CONCAT’ is the concatenation of the following four elements:

    • 2 character ISO country code (as for all personal identifiers)
    • Birth date – in the format YYYYMMDD
    • First five characters of first name (right pad with hashes if less than 5 characters)
    • First five characters of surname (removing prefixes and right pad with hashes)

    Further rules:

    • For the name elements, there is a conversion/removal of diacritic characters, apostrophes, hyphens, spaces etc using the transliteration table in ESMA’s Guidelines
    • Prefixes to surnames must be removed unless they are ‘attached’
      e.g. ‘Von der Leyen’ is ‘LEYEN’; McNeil is ‘MCNEI’ (rather than ‘NEIL#’)
    • The individual’s full name should form the basis of the CONCAT – incorrect abbreviations or nicknames must not be used (e.g. ‘JAMES’ rather than ‘JIM##’)
    • Titles (e.g. ‘Prof’, ‘Dame’ etc) should be removed
    • All UPPER CASE

    So, for example, the CONCAT code for that well known French chanteur Jacques Dutronc, born 28 April 1943, would be: FR19430428JACQUDUTRO.

    What about joint nationalities?

    • If both countries are within the EEA, use the country code of the first nationality when sorted alphabetically by its ISO 3166-1 alpha-2 code
    • If one country is within the EEA and one outside, use the EEA code
    • If both countries are outside the EEA, use the country whose ISO 3166 code is first when sorted alphabetically

    So if it’s joint German and French – use the German taxonomy as ‘DE’ comes before ‘FR’.

    For joint Swiss and French – use French taxonomy even though ‘CH’ comes before ‘FR’ (as Switzerland is outside the EEA).

    Post Brexit reporting to an EU NCA

    So post-Brexit, for the purposes of reporting to an NCA based in the EU, the UK is now outside of the EEA which impacts two things: 

    • Joint nationalities, see above
    • And, as the UK now falls into the category of “All Other Countries”, according to RTS 22 Annex II, UK individuals can no longer be identified using their National Insurance number, the passport number becomes the 1st priority identifier and CONCAT the 2nd priority identifier.

    One final pitfall – the code type

    Because these are XML fields, you need to identify the ‘code type’.  This might vary from ARM to ARM, but the standard code types are as follows:

    ‘CCPT’       – if you’re using the passport

    ‘CONCAT’   – if it is a CONCAT code

    ‘NIDN’    – for any other national identifier

    Where to go to for help

    If you are unsure about any of the reporting standards or just need a refresher, join our upcoming MiFIR core training course which will help ensure you are interpreting the MiFIR transaction reporting requirements correctly.

    Our ReportShield™ Accuracy Testing identifies all transaction reporting errors including those related to personal identifiers, providing a regular health check of all your reported data. 

    • To find out more or for a conversation with one of our regulatory specialists, please contact us.
  • Dario Crispini speaks to WatersTechnology on ESMA’s expanded supervisory powers

    Dario Crispini speaks to WatersTechnology on ESMA’s expanded supervisory powers

    Kaizen’s CEO Dario Crispini spoke to WatersTechnology on ESMA’s expanded supervisory powers and big data capabilities that have caused some confusion on how the data will be used and how its new role will shape reporting regimes.

    “Esma has a revenue-based fee process and all the DRSPs were smarting at the level of those fees, but at the end of the day, those fees are going to get passed on to the investment firms and potentially down to the consumer.”

    Read the full article 

     (You must be a subscriber to view the article in full).

  • Regulatory reporting industry expert Matthew Vincent joins Kaizen Reporting

    Regulatory reporting industry expert Matthew Vincent joins Kaizen Reporting

    London, 18 October 2022 – Leading regulatory technology firm, Kaizen Reporting today announced that Matthew Vincent is the latest senior hire to join the team.  Matthew joins as a managing director, bringing with him 30 years of experience in finance, including more than 10 years’ experience working in regulatory reporting functions at tier 1 banks.

    Prior to joining Kaizen, Matthew spent three years at the London Stock Exchange – UnaVista where he was the director of regulatory reporting strategy.  This included providing MiFIR reporting subject matter expertise to clients in the UK and EU.  Matthew was also Head of MiFID Regulatory Reporting at Credit Suisse for five years, and previously worked for Barclays Investment Bank in the operational compliance team advising on MiFIR transaction and EMIR reporting.  He has also worked at Citigroup and Deutsche Bank.  He is a member of the Consultative Working Group supporting ESMA’s Market Data Reporting Working Group and chaired the UK Finance Transaction Reporting Working Group for over ten years.   

    Dario Crispini, CEO of Kaizen, commented: “Matthew is a well-known and respected industry specialist and it is great to have him on board.  He brings a wealth of experience and a deep understanding of the industry and reporting regimes.  Regulators across the globe are being increasingly vocal that they expect the highest quality of regulatory reporting data from all firms and with the addition of Matthew, we can continue to meet the demand from our clients for high quality services that help them to meet their reporting obligations and manage their reporting risks.  It’s the expertise of people like Matthew and the team here at Kaizen that enables us to deliver the deepest and most comprehensive assurance services to the financial community.”

    Matthew Vincent, who joined the company on 17 October, said: “Kaizen Reporting has established itself as a market leader within the regulatory reporting industry and I am delighted to be joining the talented team at a time when the company is growing so rapidly and we are seeing so much regulatory change.  I look forward to being part of the Kaizen team as we continue to develop and enhance products that make working and complying with regulation easier for financial firms.”

    (ends)

    • For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com
  • Join us for a Transaction Reporting Workshop on FCA’s Market Watch 70

    Join us for a Transaction Reporting Workshop on FCA’s Market Watch 70

    Kaizen Reporting and AQMetrics are coming together for an interactive workshop to run through the FCA’s recent Market Watch 70.

    Tom Soden, Manager – Markets Reporting Team from the FCA will be joining our regulatory reporting specialists Simon Appleton and Matthew Vincent to discuss what this update means for firms, analysing the points raised and covering pragmatic solutions which can help firms.

    When: Wednesday 23 November 2022

    Time: 8:30-11:00am

    Where: Frobisher Suites, Barbican Centre, Silk Street, London EC2Y 8DS

    Visit AQMetrics’ website to find out more and book


  • In the news: Simon Appleton on FCA’s latest Market Watch 70 newsletter

    In the news: Simon Appleton on FCA’s latest Market Watch 70 newsletter

    Following the FCA’s publication of its latest Market Watch newsletter and its heavy focus on transaction reporting, Kaizen’s Director, MiFID II Transaction Reporting, Simon Appleton spoke to Global Investor Group about the surprisingly low number of firms that are testing their transaction reporting against the FCA’s data.

    “The latest FCA Market Watch newsletter shows that less than half of the UK’s MiFID investment firms are testing the quality of their transaction reporting against FCA data, which is a clear breach of their obligations. While the FCA has seen improvements in transaction reporting, today’s comments show that the regulator’s expectations around transaction reporting are increasing, and robust and comprehensive testing must be in place for all firms. There are no excuses.”

    Read more


  • FCA’s Market Watch 70 cites progress but areas for improvement on transaction reporting

    FCA’s Market Watch 70 cites progress but areas for improvement on transaction reporting

    The FCA has released its latest Market Watch newsletter which has a heavy focus on transaction reporting. The UK regulator says it is encouraged by the progress firms are making in terms of data quality and has released data showing the number of investment firms taking data extracts via their Markets Data Processor (MDP) is continuing to rise each year. 

    What is interesting is that although 716 firms requested data from the FCA’s MDP in 2021 to assess the accuracy and completeness of their reporting, this suggests that more than half of all UK MiFID firms are not doing so, a clear breach of their reporting obligations.  

    While the number of error and omission notification forms continues to rise, the data quality alerts suggest to the FCA that many firms are not conducting sufficient data checks including across asset classes. The quality of the E&O notifications (see our recent blog for tips on how to complete these) also varies, with the FCA explaining the usefulness of including examples of how fields have been misreported.

    Other concerns include the over-use of second and third priority identifiers for natural persons as well as how firms are identifying appointed representatives. Greater improvement and consistency is needed in relation to branch activity and determining when trades are being ‘executed’ thus leading to a reporting obligation.

    The order aggregation ‘INTC’ account is also being misused in certain cases and there is a warning to trading venues that they are responsible for the transaction reports made on behalf of their non-MiFID participants. It is stated that some venues have been putting too much responsibility on their members. The misreporting of the venue and the instrument full name fields is also mentioned.

    Trading venues are also reminded of their obligations in relation to instrument reference data and Systematic Internalisers are often sending instrument reference data to FIRDS in error which is confusing reportability for firms under RTS 22. Instrument testing is of particular sensitivity due the dependence on the quality of the data for the wider transaction reporting regime.

    While the FCA has seen improvements in transaction reporting, today’s comments show that the regulator’s expectations around transaction reporting are increasing, and robust and comprehensive testing must be in place for all firms. 

    Read the newsletter on the FCA’s website.

    • If you are unsure about any of the reporting standards, or just need a refresher, we would heartily recommend our core training course which will help ensure you are interpreting the MiFIR transaction reporting details correctly.

    • Kaizen’s ReportShield quality assurance services are designed to detect all reporting errors including those mentioned in the FCA’s Market Watch 70.  Contact us for a conversation about how we can get your transaction reporting in the right shape.
  • Errors and omissions notifications: the regulatory reporting confession letter

    Errors and omissions notifications: the regulatory reporting confession letter

    Regulatory reporting is hard, and mistakes inevitably do happen. But knowing what action to take once you’ve discovered errors and omissions in your reported data is equally challenging. Sometimes issues are found via internal means, but they can also be discovered by regulators who then begin asking questions.  At Kaizen, we regularly help firms in this position, supporting them with their communication to the regulator and correcting and re-reporting the transactions via our Accuracy Testing.  Here, we share some of our insights on errors and omissions notifications and what to do once your firm finds regulatory gremlins lurking.

    1. Regulatory clarity – clarify your mis-reporting

    Before enthusiastic (or defensive) emails are sent to the regulator, you must clarify exactly how deep the problem goes.  What volume of trades have been missed or impacted, over what time period?  Coupled with this is the need to understand exactly what the mis-reporting actually was.  Vague explanations will inevitably lead to further questions from a puzzled regulator.

    At this stage of issue discovery, many firms choose to perform assurance and accuracy testing on their reporting population, to ensure that any other hidden powder kegs are uncovered well before further regulatory scrutiny prevails.  Independent assurance testing is the most efficient and complete way of undergoing such checks and can also help paint a good picture to the regulators when it comes to submitting an errors and omissions notification.

    Regulatory reporting is the counterparty’s responsibility. Firms must be able to understand and explain why the reporting was wrong or incomplete. Importantly, this is true for those making direct reporting submissions to a trade repository/ARM/SDR, and it is equally true for those utilising a form of ‘delegated reporting’.

    2. Preparing the Errors and Omissions notification

    If you’ve completed the above, now it’s time to own up to all the things you’ve got wrong. To do this, most regulators expect firms to fill in an errors and omissions notification.  The ideal point to draft the notification is not the same for all situations. Generally though, only once a firm has performed satisfactory checks and is confident with the known scope of the errors, can the notification be drafted. The UK FCA Errors and Omissions form* and the Central Bank of Ireland’s form* are good starting points to illustrate what details you should include, but each regulator will have its own variation on this theme and some even simply ask for a free format email.

    The notification should ideally confirm:

    • The full scope of the mis-reporting
    • Remediation steps undertaken
    • The cause of the issues
    • How these errors will be avoided in future.

    The regulator needs to see that you have control over these issues and over the reporting in general.  Failure to demonstrate strength in this area will undoubtedly prompt the regulator to probe for more information and place demands on how and when further data is provided, often citing how and when remedial actions are carried out.

    In our experience, it is exponentially better to provide all the information in advance. The motive here is to answer all the questions the regulator may have before they are asked.  Providing the bare minimum of detail, in an evasive or defensive manner, can backfire and lead to further scrutiny and the possibility of fines.  

    In all cases, you should be ready for follow up questions from the regulator.  The more thorough and prepared you have been with your scope investigation, the more comfortable you will be in answering such questions. In addition, it’s important to remember that the aim here is to close out as many questions as you can before there is a chance to ask them.  Therefore, the deeper the dive in reviewing existing reporting quality and completeness, the better prepared you will be and fewer questions will arise.

    3. Frequency and strength of notifications

    In our experience, fewer but stronger, notifications is the optimal strategy here.  As mentioned earlier, the aim of the notifications is to demonstrate the strength of your regulatory reporting, and control over the errors at hand.  Some firms have legal and compliance policies in place to notify their supervisor for each and every error uncovered on an ad-hoc reactive basis. However when it comes to the regulator, too frequent notifications risk demonstrating a lack of control over issues and procedures, and can lead to further regulatory scrutiny.  Some regulators may request regular updates for known issues or existing independent reviews, but usually only for many errors across large data arrays.

    Whatever frequency is explicitly committed to, you must ensure that any deadlines are adhered to, or give reasonable written notice with clear sensible justifications as to why a specific date is no longer feasible.

    4. Remediating errors and other useful actions

    Notifications should demonstrate an organisation’s remediation plans, taking into account factors such as technology build requirements, prioritisation alongside existing commitments, and it is always a shrewd move to add contingency for unforeseen delays.  Firms would also be wise to use this opportunity to:

    • Create or enhance deep, tailored and universal accuracy and completeness testing controls incorporating all fields and all reports submitted
    • Ensure supporting policies and procedures are up to date and fully cater to avoid a repeat of the identified issues
    • Check that reporting errors are escalated appropriately with clear and written action points for defined responsible stakeholders
    • Confirm access to the reported data from the regulator or trade repository/ARM/SDR which is regularly saved down for future endeavours
    • Engage in annual regulatory training to ensure that all impacted internal parties are up to date on reporting requirements.

    5.  Final thoughts

    Demonstrating the appropriate controls and strength of process regarding how you approach errors and omissions notifications, and the manner in which information is relayed to the regulator, is absolutely crucial to that working relationship, and will proactively influence the nature of any further regulatory scrutiny, fines or demands that follow. Having a well thought through errors and omissions notification policy will help ensure that communication with the regulator is open and effective.

    • If you find yourself in this position and would like a discussion with one of our regulatory specialists about this process, please get in touch.

    *Both forms will download rather than open in a webpage.

  • Join Kaizen at the bwf and ICMA Capital Markets Conference

    Join Kaizen at the bwf and ICMA Capital Markets Conference

    Join the Kaizen team in person at the annual bwf and ICMA Capital Markets Conference in Frankfurt on 13 October.  The event will take place at the Deutsche Nationalbibliothek – Frankfurt and will be combining the current regulatory discussion with an analysis of various aspects of the German and European securities market.

    Our senior regulatory reporting specialist, Jonathan Lee, will be speaking on why data quality matters to regulators and reporting firms alike.

    Book here

  • Kaizen wins at the Risk Technology Awards 2022

    Kaizen wins at the Risk Technology Awards 2022

    London, Thursday 4 August 2022 – Leading regulatory technology firm, Kaizen Reporting has won ‘Regulatory Reporting System of the Year’ at the Risk Technology Awards 2022 for its ReportShield™ Accuracy Testing service. This is the fourth time that Kaizen has won a Risk award for its regulatory reporting services. 

    The 2022 Risk Technology Awards were divided into 25 categories and received 120 entries, which were narrowed down to a shortlist of 80 firms. A panel of eight industry experts and Risk.net editorial staff reviewed the shortlisted entries. The judges individually scored and commented on the shortlisted entrants, before meeting to review the scores and, after discussions, made a final decision on the 24 winners.

    Antony Chambers, Publisher, Risk.net, commented:

    “This year’s Risk Technology Awards were as competitive as ever with both the number of firms entering and the quality of the services they provide the market. Kaizen Reporting stood out for its Accuracy Testing service which enables firms to submit high quality and accurate data to the regulators.”

    Dario Crispini, CEO of Kaizen, commented:

    “Global regulators are giving the financial services industry a clear and consistent message that they expect the trade and transaction data they receive to be of the highest quality. Kaizen’s Accuracy Testing service helps firms deliver just that and we are honoured that the service has been recognised as the ‘Regulatory Reporting System of the Year’ at the Risk Technology Awards for 2022.”    

    Kaizen’s Accuracy Testing is part of the company’s ReportShield™ suite of quality assurance services, which help financial firms meet their reporting obligations and effectively manage their regulatory risks. The service is tailored for global trade and transaction reporting regimes including MiFIR, EMIR, CFTC, SEC, SFTR, MAS, ASIC, HKMA, and FinfraG. Accuracy Testing is unique in being able to fully assess the quality of the data that firms report to the regulator.

    (ends)

    • For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com
  • FCA consults on improving equity secondary markets

    FCA consults on improving equity secondary markets

    Earlier this week FCA released its Consultation Paper (CP) on improving Equity Secondary Markets.  Although some elements cover ALL asset classes, the expectation is that we will see the staggering of topics and the equivalent for the more complex Non-Equity asset classes released soon too. 

    Since Brexit there has been the gradual transition of MiFID II/MiFIR into UK Law, without the need for a ‘bonfire of regulations’, but with the indication that the UK and HMT (see Wholesale Markets Review WMR) look to right some of the ambiguity and unnecessary complexity caused by the regulation since its inception in 2018.  HMT’s first step was to give the FCA the power to change and adapt the regulation, without the bureaucracy of legislative changes.

    With that, we now see this CP, seeking feedback from the industry, with responses due by mid-September 2022.

    For this blog, I’ll concentrate on Post-Trade Transparency Reporting (PTT) RTS 1, in which the FCA’s plan, along with the WMR, is to lower costs and improve the information content of trade reports and how Equity Markets operate;

    “We want to change our rules to enhance the quality of execution for investors and improve the information content of post-trade transparency”.

    So as we dig into the details, we can see the aim of improving the content of PTT reporting by enabling market participants to better identify transactions that contribute to the price discovery process and to improve the consolidation of trade reports from multiple sources.  Price Discovery being the key element to close to real-time reporting, within 1 minute of execution for RTS 1. In addition, a high priority is simplifying the reporting of OTC transactions by removing the Systematic Internaliser (SI) status as a criterion for establishing when an investment firm is required to report transactions.  The FCA is proposing to adopt a new regime based on designated reporting firms, thus segregating the SI requirements from reporting responsibility.  n.b. SI’s will not go away.

    Two of the main issues identified within the PTT regime;

    1. The current system of flags does not always provide sufficiently precise information to separate price forming transactions from technical trades
    2. There is ambiguity as to which flags should be used leading to different firms adopting different standards which lowers the comparability of trade reports and the ability to consolidate them.

    These shortcomings negatively impact the quality of the information contained in post-trade reports, increase compliance costs for the reporting entities as well as the costs for firms that use post-trade data to inform their trading decisions.

    Yes there is an overlap of descriptive flags and a tidy up will make things clearer e.g. clarification of TNCP and NPFT but the removal of some flags should be closely reviewed with feedback from the industry as to whether there is any exposure to undue trading risk to some firms.

    The Designated Trade Reporter adoption is stepping back into what looks like more of a MiFID I reporting regime.  Investment Firms electing themselves as the designated reporter, with notification to the FCA mandatory and regardless as to whether they are an SI in the instrument or asset class, delineating the SI regime from the reporting responsibility.  This will certainly favour the buy-side but as a reminder, there is still the possibility of reporting if neither party to the trade is an SI or a Designated Reporter and as before the seller will report.

    In my opinion, for this to work, a central source, database or register has to be consolidated and maintained with the emphasis on the SIs and Designated Reporters to register and communicate to their buy-side clients.  We saw this succeed leading up to MiFID II go-live with the APAs coming together as a consortium along with Smartstream RDU to create the SI Register (SIR), which was imperative to understanding reporting obligation.  Ultimately with a change in rules, there will be reporter uncertainty or missing reporter status’s which could lead to under or over-reporting, which is a key area Kaizen’s PTT testing service highlights.

    The FCA is aware and did highlight the high costs associated with regulatory changes. These can be seen across multiple teams within firms that regulatory reporting affects and industry conversations have been and will continue to be had.

    What the industry wants from any change or divergence around PTT is; simplification, less ambiguity meaning consistency of reporting across firms and ultimately better quality trade reporting data, so investors can be better informed on pricing, liquidity and best execution.

    • For a conversation with Chris about the topics above or for help with your trade reporting data quality please get in touch.
  • Sunshine and surveillance star in FCA’s summer update

    Sunshine and surveillance star in FCA’s summer update

    The FCA’s data-led approach is clear to see in a welcome update that sheds light on the regulator’s Markets Data Processor (MDP), which is described as a “source of regulatory sunshine that allows us to oversee the market…with dedicated software…to detect potential issues.”

    The FCA’s MDP receives over 30 million transaction reports and over 100 million order reports a day which are then analysed for a variety of offences, including insider dealing and market manipulation.  This surveillance effort is supplemented with Suspicious Transaction and Order Reports (STORs) received from market participants which averaged more than 90 per week last year and represented an increase of almost 15% on 2020.

    Market abuse approach

    In this update, the regulator highlighted the importance of the deterrence factor offered by transaction reporting and monitoring, explaining that ‘intensive scrutiny’ meant that participants are less likely to abuse markets if they know they are being watched. 

    The FCA gave an insight into its approach and powers to monitor, detect and prosecute market abuse as well as a general overview of its current case load.  When the perpetrators of market abuse are more organised and operate across borders, the FCA continues to collaborate and exchange data and intelligence with regulators globally. The efforts of 90 FCA enforcement staff reinforced with specialist cyber, legal, intelligence and primary and secondary market oversight teams are focused on tackling market manipulation and insider dealing.

    Data-led strategy

    One common theme running through this update is the obvious importance of the FCA’s data-led approach to surveillance and regulation. It will therefore be interesting to see whether the FCA’s forthcoming MiFID transaction reporting consultation paper proposes to follow ESMA’s lead with the introduction of new data fields to assist with firm-based supervision and monitoring the compliance of conduct of business-related rules.

    With the FCA’s data strategy being published in the coming months, prioritising the monitoring of firms’ more general trading and a broader range of activities through transaction-related data will require more granular information. 

    Simplification of reporting?

    If the transaction reporting consultation paper is published before the full data strategy, it could be that ‘simplification’ and a focus on increased data quality is given priority over the data strategy in the short-term. Although, through the quality assurance testing we do at Kaizen, we can see that data quality is still very poor*, starting to incorporate the FCA’s data strategy into the MiFID transaction reporting consultation paper will bring it in line with the FCA’s strategy as a whole.

    As misreporting can lead the regulator down blind alleys and cause market abuse and other offences to go undetected, we can see from this interestingly timed update, that accurate and complete transaction reporting is still of paramount importance to the FCA.

    • For a conversation with Simon about the topics above or for help with your transaction reporting data quality please get in touch.

    *Only 10% of transactions are successfully reported under MiFID II. 

  • Join Kaizen at the FIA Forum in Frankfurt

    Join Kaizen at the FIA Forum in Frankfurt

    Join the Kaizen team in person at the FIA Forum in Frankfurt on 12 July.  The event will take place at the Hilton Hotel – Frankfurt, City Centre and will be addressing key issues impacting listed and cleared derivatives market participants in the region. 

    Our regulatory reporting specialists will be speaking on various topics from the EU regulatory landscape to the need for improved data quality. We look forward to seeing you at the forum.

    Book here

  • In the news: Simon Appleton on the state of play for transaction reporting

    In the news: Simon Appleton on the state of play for transaction reporting

    Regulated firms trading in markets globally are bracing themselves for what’s been termed a ‘sea change’ in the regulators’ approach to transaction reporting. Kaizen’s Simon Appleton, Director, MiFID II Transaction Reporting, spoke to A-Team Insight about the scope and complexity of reporting.

    “The key features of a transaction reporting solution can be divided between report generation, submission, and quality assurance, according to Appleton, who believes it is important to segregate quality assurance from the reporting process to ensure independence and optimisation of reporting quality through a universal, broad and deep testing approach.

    “This three-way separation also ensures firms retain flexibility over their reporting and do not get too baked into a single solution.”

    Read the full article here. 

  • In the news: Simon Appleton on MiFID II data standards

    In the news: Simon Appleton on MiFID II data standards

    While efforts to create a consolidated tape tend to dominate recent market structure conversations, regulators and market participants also stress the urgent need to improve data standards and reduce duplications in reporting.  Kaizen’s Director of MiFID II Transaction Reporting, Simon Appleton spoke to IFLR about MiFID II data standards and the overlaps in EMIR and MiFID II transaction reporting.   

    “The government is looking for views on how to mitigate duplicative reporting between regulations, like it did with Securities Financing Transaction Regulation (SFTR), when the Temporary Transitional Power expired.”

    Read the full article here.  (You must be a subscriber to view the article in full).

  • New body for APAs and ARMs grows legs

    New body for APAs and ARMs grows legs

    Authors: Simon Appleton and Chris Machin

    Last week’s announcement of the formation of APARMA, a Trade Association (TA) for Approved Reporting Mechanisms (ARMs) and Approved Publication Arrangement (APA) providers, is long overdue. The implementation of MiFID II brought with it a significant increase in the rules and regulations covering ARMs and APAs (which took over from Trade Data Monitors (TDMs), under MiFID I) and with it a lot more risk and the potential to be penalised for breaching their obligations. 

    Collectively known as Data Reporting Services Providers (DRSPs), ARMs and APAs facilitate the effective supervision and transparency of financial markets allowing regulators and investors to receive timely and comprehensive trading information. 

    The other category of DRSP is Consolidated Tape Providers (CTPs) which collect trade reports from APAs and Trading Venues. Forthcoming changes to regulations in the UK and EU could mean that it’s just a matter of time before this new trade body brings CTPs into the fold but likewise there is huge debate about the need and effectiveness of such a requirement.  That debate will surely continue…

    The rules governing Data Reporting Services Providers are substantial and are defined in the FCA’s Regulatory Framework, which comprises:

    MiFIR also outlines in Regulatory Technical Standard (RTS) 13 the obligations covering the authorisation, organisational requirements and the publication of transactions for DRSPs. The most significant aspects are in Articles 10 and 11, which set out the rules governing how ARMs, APAs and CTPs should manage incomplete or potentially erroneous information.

    The European Securities and Markets Authority (ESMA), recently published Draft RTS setting out criteria for the sound and prudent management of DRSPs as well as for their operational effectiveness under MiFIR.  Many reasons have contributed to the reduction in the number of ARMs and APAs over time, including additional regulations, data and rule complexities, operational risks, Brexit and reduced margins to name a few.

    However, the formation of APARMA will give members renewed purpose, momentum and a unified, louder voice when speaking with regulators and clients alike.

    Following yesterday’s ‘Dear CEO’ Letter from the FCA, we are seeing the regulator outline their approach to supervision:

    “This letter outlines our view of the key risks of harm in the DRSP portfolio and communicates what we expect DRSPs to do to minimise potential risks to consumers and market integrity from failures to meet regulatory requirements”. 

    The FCA will also expect the DRSPs to evidence the actions they have taken in response to this letter. 

    Along with this, the FCA have reiterated that enforcement, reviews and assessments will be applied “with real and meaningful consequences for firms who do not follow the rules” and highlighted their take on the key risk of harm:

    • The Market is concentrated among a small number of DRSPs, limiting the opportunity for clients to change provider and may lead to lower incentives to provide high quality services
    • DRSPs may have inadequate systems and controls to identify incomplete and potentially erroneous trade or transaction reporting data
    • Insufficient operational resilience may lead to disruption for market participants, consumers and Regulators, or the loss, compromise, or lack of availability of data

    This is a clear indication that competition is essential and encouraged to create higher levels of reporting services, along with complete and accurate data, that has been clearly defined over many years, since pre-MiFID II inception. APARMA lobbying will be key to this evidencing of operational resilience but the FCA have stated their expectation of an “Open and co-operative relationship”, which I’m sure will be tested from both sides.

    From Kaizen’s perspective, we have been checking the accuracy and completeness of trade and transaction reporting across multiple regimes for a nearly a decade now, identifying potentially erroneous reporting.  The FCA’s guidance is clear and firm but the new trade association for APAs & ARMs is perfectly timed to build their point of view around the complexities of MiFID II. Hopefully, all parties can work together to create an improved and innovative framework in a post-Brexit regulatory environment.

    • For a conversation with one of our regulatory specialists about the topics mentioned above, please contact us.
  • Data at the forefront of FCA’s annual business plan

    Data at the forefront of FCA’s annual business plan

    The FCA recently published its 2022/23 business plan and short to medium-term strategy.  The three-year strategy and yearly business plan are of significant interest as they provide an insight into current areas of primary focus for the regulator.  In this blog, we highlight the matters that are most likely to impact regulatory reporting as well as other areas of interest to us and our clients.

    Data led regulation

    In terms of how the FCA will operate going forwards, the key changes relate to the way the regulator will make use of data and use real time intelligence to see how firms and markets are performing generally but also to help them recognise and detect risks at an early stage. 

    Although the FCA’s data strategy will be published in the coming months it’s already clear that the regulator is keen to become data-led and is looking to establish what information, technology and staff are needed to achieve its objectives.  Over time, it will become increasingly likely that any rule changes will be based on actual data.

    Market integrity and confidence

    The FCA actively monitors transaction reports and other data to identify insider dealing and market manipulation and has emphasised that it’s looking to deliver assertive action on market abuse, and increase the perceived effectiveness of their action to promote market integrity, by introducing a new perception metric.

    Separately, the FCA is looking to deliver the Market Surveillance Refresh project and Market Data Processor (MDP) refresh to improve alerting, triage, enquiry analytics and increase their detection capability through advanced analytics and improved data coverage.

    Promoting competition and positive change

    One of the FCA’s three areas of focus will involve tailoring rules to better suit UK markets in a global context to help prepare financial services for the future.  Ensuring the UK is one of the leading markets of choice for issuers, intermediaries and investors alike is designed to reinforce the UK’s position in global wholesale markets.

    Interestingly, the eagerly awaited MiFID Transaction Reporting Consultation paper will indicate how much weight the FCA places on each of the three priorities outlined above.  In the meantime, it’s clear that the role of data is assuming more and more importance with the regulator as they determine exactly what data they want to receive and how to best use the vast array of reports, transactions and information received since the financial crisis.


    • For a conversation with Simon or one of our regulatory specialists about the topics mentioned above, please contact us.
  • Join Kaizen at the EUREX Derivatives Forum 2022 in Frankfurt

    Join Kaizen at the EUREX Derivatives Forum 2022 in Frankfurt

    Join the Kaizen team in person at the EUREX Derivatives Forum Frankfurt 2022 on 24-25 May.  The event will take place at the Congress Center Messe Frankfurt and will also be available virtually with thought leadership insights, industry debates and keynote speeches, focusing on trading and clearing for derivatives and securities financing across asset classes.

    We will have an exhibition stand, so please come and say hello!

    Book here


  • Join us at the ISDA AGM in Madrid

    Join us at the ISDA AGM in Madrid

    Join Kaizen at the ISDA 36th AGM on 10-12 May 2022 in Madrid.  Targeted at derivatives professionals, this year’s event will feature high-level keynote speakers with panels on critical topics such as benchmarks, sustainable finance and crypto derivatives.

    We will have an exhibition stand, so come and say hello!

    The event is being held at the Hotel Riu Plaza España.


  • In the news: Chris Machin on European consolidated tape for derivatives

    In the news: Chris Machin on European consolidated tape for derivatives

    The complexity and cost of developing a consolidated tape for derivatives has led market experts to question the contentious European proposal.  Kaizen’s Senior Regulatory Reporting Specialist, Chris Machin spoke to Global Investor Group.

    “The development of the CT has been an incredibly complex issue. Not only is it the selection criteria and the inclusion of multiple asset classes, but it’s bringing that all together in one format, and then sending it out and publishing it in an agreed format.”

    Read the full article here.  (You must be a subscriber to view the article in full).

  • Crypto to remain under the spotlight: MiFID view

    Crypto to remain under the spotlight: MiFID view

    It seems like not a week goes by when we don’t hear something about the regulation of crypto. It is clear that regulators globally are looking closely at the risks posed by digital assets to consumers, markets and the financial system.

    More regulation is on the way

    In the past few weeks, Russia’s invasion of Ukraine has brought crypto into sharp focus due to concerns that it could be used to circumvent economic sanctions.  More generally, in the EU, the proposed Markets in Crypto-Assets Regulation (MiCA) will change the regulatory perimeter for crypto-currencies and derivatives on crypto currencies. 

    In the UK, the FCA recently reminded regulated firms of their obligations when interacting with cryptoassets and related services, whilst also looking to set up a new crypto department.  Across the pond, the Senate is showing increasing interest in crypto, holding several hearings on digital assets and their regulation, an area the CFTC and SEC are actively looking at.

    How regulators are handling crypto assets differs greatly in Asia. Crypto transactions are now considered criminal financial activity in China, whereas retail cryptocurrency advertisements have been banned in Singapore.  The HKMA’s recent discussion paper on Crypto-assets and Stablecoins talks about a risk-based approach to handling risks posed to monetary and financial systems.

    Additional regulation will be broadly welcomed by the crypto community and investors, but that is still some time away.

    So what are the reporting obligations for crypto currencies under MiFID?

    Since 2018 when we saw the FCA comment that “we do not consider cryptocurrencies to be currencies or commodities for regulatory purposes under MiFID II”, there has not been much change in the reportability of crypto derivatives under MiFID.   

    Spot trading in crypto currencies is not in scope for MiFID reporting and as with FX and commodities, where there is a derivative with a currency or commodity underlier, they will not be reportable unless the derivative itself is admitted to trading on a trading venue (TOTV).  This is irrespective of the classification of crypto currencies by regulators.

    ESMA’s Opinion Paper in May 2017, expanded the scope of reportable instruments to include OTC derivatives “sharing the same reference data details” as TOTV instruments. In practice, this process is managed by the ANNA Derivative Services Bureau (DSB).  The DSB sets out the relevant instrument data details, after consultation with the industry, that are to be assessed to determine effective equivalence to TOTV instruments.  These go beyond the reference data details pointed to by ESMA.   This change made it harder for firms to establish reportability on an instrument by instrument and trade by trade basis. 

    What instrument types are transaction reportable under MiFIR?

    • Spreadbets and Contract for Difference (CFDs) with crypto-currency underliers that do not share the same reference data details as TOTV instruments admitted to trading are not reportable.
    • Exchange traded options and futures with crypto underliers that are admitted to trading on a third country venue are not reportable. For example, the trading of bitcoin futures on the CME is not reportable because the CME is not a trading venue.

    Based on our review of UK Financial Instruments Reference Data System (FIRDS) we have identified the following categories of crypto related instruments. The table below shows the number of crypto related financial instruments on UK FIRDS by instrument category ISO 10962.


    Instrument category   

    Number of instruments

    FX Forwards   

    8

    Entitlements (rights)   

    433

    Equities   

    126

    Debt instruments   

    133

    Collective investment vehicles   

    3

    Total   

    703


    There are some venues that do admit to trading crypto currency futures.  Where those instruments are traded they are reportable. Examples are:


    Post Brexit    

    UK reportable   

    EU reportable   

    Spot crypto-currencies   

    N

    N

    LMAX Digital (Gibraltar)   

    Y

    N   

    Crypto Facilities   

    Y

    N

    CME Bitcoin Futures     

     N

    N  


    Under UK MiFIR, the instrument has to be traded on a trading venue, or the immediate underlying has to be traded on a UK, EU or Gibraltar trading venue to be reportable.

    Under EU MiFIR, the instrument has to be traded on a trading venue, or the immediate underlying has to be traded on a trading venue within the EEA, to be reportable.

    A path away from complexity

    As can be seen from the above, assessing reportability of crypto instruments under MiFIR is challenging and it is built on an ever-changing set of data.  This makes the likelihood of under-reporting much higher should venues start admitting DSB crypto derivatives. 

    Assessing instrument reportability under EU MiFIR will be simplified after the recent MiFID review by partially moving away from TOTV for derivatives and incorporating an ‘SI approach’ but that’s a couple of years away.

    We are waiting to hear from the FCA to know whether the UK regulator intends to follow ESMA’s lead to simplify this area. Whether the FCA mentions crypto specifically in its long-awaited MiFIR Transaction Reporting consultation paper remains to be seen but it is something we would welcome.

    • For a conversation about reporting crypto under MiFIR or any other regulation, please contact us.
  • Focus réglementaire de l’union Européenne – Qualité des données déclarées sous MiFID II

    Focus réglementaire de l’union Européenne – Qualité des données déclarées sous MiFID II

    Peu importe où vous regardez, quelqu’un, quelque part est en train de parler des révolutions technologiques et de données en générale. Les données sont désormais omniprésentes dans nos vies, que ce soit à travers le nombre de pas que nous faisons quotidiennement ou via la quantité d’actions négociées chaque jour. Il est donc impératif que ces données consommées soient très précises pour nous permettre de prendre des décisions très importante. Cette philosophie et cette approche est reprise par les régulateurs financiers de toute l’Europe avec leur attention qui se concentrent sur l’amélioration de la qualité des données pour 2022.

    Parmi la liste des priorités de supervision du secteur des services financiers récemment publiées, l’Autorité des Marchés Financiers (l’AMF) a souligné et a mis beaucoup d’importance sur la qualité et la précision des données déclarées par les entreprises d’investissement et les échanges financiers. Il est indispensable que ces déclarations soient précises pour la surveillance des activités de trading et pour détecter les manipulations et les abus du marché.

    Ce n’est, par ailleurs, pas un hasard si la « qualité des données » figure parmi les deux seuls thèmes des régimes déclaratifs introduits par la directive MiFID II. En effet, l’Autorité européenne des marchés financiers (ESMA) engage les autorités nationales compétentes (NCA) à tenir compte dans le cadre de leurs activités de surveillance en 2022. L’autre thème concerne les frais et les commissions facturés par les sociétés de gestion.

    L’accent mis sur la qualité des données est en partie un sous-produit du fait que les sociétés de gestions ont commencé à déclarer leurs transactions qu’en vertu de la MiFID II depuis 2018, alors que le côté vendeur fait des déclarations en vertu de la MiFID I depuis 2007. Ceci représente un autre exemple d’élaboration de politiques axées sur les données par les régulateurs qui, de manière compréhensible, deviennent de plus en plus axées sur les données.

    Devenir davantage axé sur les données élimine la nécessité pour les régulateurs d’allouer leurs ressources limitées en fonction du risque, où l’accent est principalement mis sur les grandes entreprises, par exemples à travers des visites de supervision et de correspondance, permettant ainsi que les petites entreprises soient supervisées à l’aide d’une approche basée sur des événements ou des revues thématiques. En utilisant à meilleur escient les données qu’ils reçoivent à l’aide d’outils d’analyse de données permet une revue plus systématique et plus approfondie de toutes les activités des entreprises autorisées concernées. Ils ne seront plus contraints d’examiner des échantillons d’activité car les capacités informatiques disponibles aujourd’hui permettent d’analyser toutes les données minutieusement.

    La prévention des abus de marché au sein du secteur des sociétés de gestion était également l’une des priorités thématiques de surveillance de l’AMF pour 2021. Certes, mieux vaut prévenir que guérir, on sait que les régulateurs européens utilisent également les déclarations de transactions transmises par les acteurs buy-side comme sell-side pour surveiller des délits initiés et des manipulations de marché ainsi que rechercher les anomalies du marché.

    Cependant, il existe depuis longtemps un gap dans le réseau de surveillance en ce qui concerne les gestionnaires de fonds d’investissement alternatifs (Alternative Investment Fund Managers) et les sociétés de gestion UCITS qui fournissent des services MiFID à des tiers. L’ESMA prend donc des mesures supplémentaires et propose que ces entreprises commencent à déclarer les transactions sous MiFID pour la première fois à la suite de leur revue de l’année dernière.

    L’ESMA suggère également d’introduire un indicateur de catégorisation de client de MiFID, un exemple qui démontre que les régulateurs utiliseront les rapports des transactions déclarés non seulement pour surveiller ‘les marchés’ mais également pour surveiller les ‘entreprises d’investissements’.  Cet indicateur de catégorisation des clients MiFID permettra aux régulateurs européens d’évaluer à grande échelle et de manière automatisée si des produits inadaptés ou risqués sont vendus aux clients de détail.

    Un régulateur guidée par les données

    Jessica Rusu, responsable des données, de l’information et du renseignement de la FCA, a déclaré lors du forum RegTech de la FCA le 10 février 2022 qu’une industrie axée sur les données a besoin d’un régulateur axé sur les données. La FCA donne la priorité à l’utilisation de la science des données, des technologies numériques et des capacités de renseignement pour suivre le rythme des changements dans les services financiers.

    Leur division de données, technologie et innovation cherche à construire une révolution numérique grâce à des projets de science des données et à créer un environnement d’intelligence numérique unifié pour réévaluer la façon dont FCA collecte et analyse les données. Le recrutement des scientistes experts en données est au premier plan de la stratégie de la FCA et permettra au régulateur d’être plus innovant et flexible dans sa façon de réagir aux changements de l’industrie.

    La CSSF explique que des données de mauvaise qualité peuvent engendrer des faux positifs

    La Commission de Surveillance du Secteur Financier (CSSF), le régulateur luxembourgeois a récemment émis un communiqué de presse pointant le doigt sur la qualité médiocre des déclarations de transactions qu’il reçoit en vertu de la directive MiFIR.  Attentive à la qualité des données, la CSSF a identifié un certain nombre d’erreurs reportés fréquemment par les entreprises. Elle reconnaît toutefois que ses observations ne sont pas à la mesure de la montagne de problèmes rencontrés par ces entreprises et ne sont peut-être pas les plus flagrantes.

    Le régulateur luxembourgeois souligne l’importance cruciale des déclarations de qualité pour pouvoir détecter des abus potentiels du marché. Elle indique en outre que des données de piètre qualité peuvent engendrer des faux positifs et représenter une violation grave, notamment si les erreurs déclaratives provoquent la dissimulation de possibles cas d’abus de marché.  La CSSF fait rappelle à l’article 47, qui fixe les sanctions, mesures et pénalités pouvant être infligées aux entreprises d’investissement en cas de déclarations erronées en vertu de l’article 26 de MiFIR.

    La période de grâce est donc bel et bien terminée pour les entreprises d’investissement avec les directives de MiFID II étant désormais en vigueur depuis plus de quatre ans.  Ainsi, de la même manière que nous exigeons des données précises dans toutes nos activités quotidiennes, les régulateurs ont besoin de données de meilleure qualité de la part des entreprises d’investissement et échanges financiers.

    Il ne serait pas surprenant que nous commencions à voir des mesures d’activités forcée au cours des 12 prochains mois en ce qui concerne les échecs de déclaration des transactions, en particulier en Europe, où l’ESMA a encouragé les régulateurs à être plus proactives avec leur pouvoir d’exécution.

    • Kaizen Reporting peut non seulement aider les entreprises à détecter les problèmes de qualité dans leur reporting réglementaire, mais aussi les aider à comprendre les obligations de reporting et les mesures correctives
    • Pour une conversation avec Simon ou l’un de nos spécialistes en réglementation, veuillez nous contacter.
  • EU regulatory focus – MiFID II reporting data quality

    EU regulatory focus – MiFID II reporting data quality

    Lire cet article en français

    Everywhere you look, someone somewhere is talking about the tech revolution and data. Data is now an integral and unavoidable part of our lives, from the number of steps we make to the number of stocks traded each day. It therefore goes without saying that the data we consume and use as the basis for important decisions must be accurate. This ethos is being echoed by financial regulators throughout Europe who are turning their focus to improved data quality for 2022.

    The Autorité des Marchés Financiers’ (AMF) recently published its supervisory priorities for the financial services industry, highlighting the importance of accurate data and high quality regulatory reporting from investment firms and trading venues. Accurate reporting data is of paramount importance to the oversight of trading activity and the detection of market abuse and manipulation.

    ESMA MiFID II guidelines

    It is quite revealing that ‘data quality’ in the various reporting regimes introduced by MiFID II is one of only two themes flagged by ESMA, that national competent authorities (NCAs) should take into account, in their supervisory activities in 2022. The other theme relates to costs and fees invoiced by asset managers.

    The focus on data quality is partly a by-product of asset managers only having to transaction report under MiFID since 2018, whereas the sell-side have been reporting under MiFID I since 2007. This is another example of data driven policy making by regulators that are understandably becoming more data led.

    Becoming more data driven removes the need for regulators to allocate their limited resources based on risk where the focus is primarily on larger firms, e.g. through supervisory visits and correspondence, with smaller firms being overseen using event based supervision or thematic reviews. Clever use of the data they receive using data analytics tools allows more routine and closer scrutiny of potentially all activity by authorised firms covered by the data. They will no longer be constrained to reviewing samples of activity, the computing power now available allows all the data to be subjected to scrutiny.

    The prevention of market abuse within the asset management sector was also one of the AMF’s thematic supervisory priorities for 2021. Whilst prevention is better than cure, we know that European regulators are also using transaction reports submitted by buy-side and sell-side firms alike to monitor insider dealing and market manipulation as well as to look for market abnormalities.

    However, there has long been a gap in the surveillance net when it comes to Alternative Investment Fund Managers and UCITS management companies that provide MiFID services to third parties. ESMA is therefore taking further action and proposing that these firms will start to transaction report under MiFID for the first time as a result of their review last year.

    ESMA is also proposing to introduce a MiFID ‘client categorisation flag’ which is an example of where regulators will use transaction reports to not just monitor ‘markets’ but to also monitor ‘investment firms’ specifically. The MiFID client categorisation flag will allow European regulators to assess on a large scale and, in an automated way, whether unsuitable or risky products are being sold to retail clients.

    The FCA, a data-led regulator

    Jessica Rusu, the FCA’s Chief Data, Information & Intelligence Officer, stated at the FCA’s RegTech Forum on 10 February 2022 that a data driven industry needs a data-led regulator. The FCA is prioritising the usage of data science, digital technologies and intelligence capabilities to keep pace with changes in financial services.

    Their Data, Technology and Innovation division is looking to build a digital revolution through data science projects and building a Digital Unified Intelligence Environment to reassess how FCA collects and analyses data. The recruitment of data scientists is at the forefront of the FCA’s data strategy and will allow the regulator to be more innovative and flexible in the way it reacts to changes in the industry.

    CSSF on MiFID II data quality

    The Commission de Surveillance du Secteur Financier (CSSF), the Luxembourg regulator, recently issued a press release regarding the poor quality of transaction reports it receives under MiFIR. The CSSF’s continued focus on data quality has identified a number of errors repeatedly being made by firms. However, the regulator acknowledges that their findings will not represent the universe of issues firms are facing nor potentially the most egregious.

    The Luxembourg regulator emphasised that high quality transaction reports are essential if they are to detect potential market abuse. Furthermore, they stated that poor data quality can trigger false positives and may constitute a serious breach, particularly if reporting errors lead to the concealment of potential market abuse cases. The CSSF is, therefore, recalling Article 47 which determines the sanctions, measures and penalties that may be imposed against investment firms for misreporting under Article 26 of MiFIR.

    Essentially, the honeymoon period is over for firms as it’s now over four years since MiFID II went live. So, just as we demand and want accurate data in our everyday lives, regulators need and expect better quality data from investment firms and trading venues.

    It wouldn’t be surprising if we start to see some MiFID II enforcement activity over the next 12 months in relation to transaction reporting failures, particularly in Europe, where ESMA has been encouraging NCAs to be more proactive with their enforcement powers.

    • Kaizen Reporting can help firms not only detect quality issues in their regulatory reporting, but also help them understand the reporting obligations and corrective measures.
    • For a conversation with Simon or one of our regulatory specialists, please contact us.
  • In the news: Dario Crispini on crypto derivatives

    In the news: Dario Crispini on crypto derivatives

    With the regulation of crypto being a hot topic right now, Kaizen’s CEO Dario Crispini shared his insights with Radi Kasawneh at Global Investor Group.  

    “Not everybody knows that crypto derivatives are in scope, so it’s making clients aware of how to report, and making sure they are reporting properly,” Crispini told Global Investor. “The next step will be more clarity on the reporting side, so the big message from us is that there is a lot of regulation on its way.”

    Read the full article here.  (You must be a subscriber to view the article in full).

  • Kaizen CEO Dario Crispini to speak at TISA MiFID II Virtual Conference

    Kaizen CEO Dario Crispini to speak at TISA MiFID II Virtual Conference

    We’re delighted to be taking part in TISA’s MiFID II Virtual Conference on 3 March 2022.

    Kaizen CEO Dario Crispini will be speaking about the key issues for regulatory reporting this year with a particular focus on both transaction and post trade reporting under MiFID II.

    The regulatory reporting landscape is set to become more demanding as well as more complex this year as regulators place increased importance on improving data quality and at the same time, the UK prepares to release its own Consultation Paper on MiFIR.  As the burden of regulatory reporting increases, Dario will cover how firms can stay ahead of the game and deliver accurate results with their reporting. 

    When: Thursday 3 March 
    Time: 9.40 – 10.10am BST

    Find out more and book on TISA’s website. 

  • WATCH: What’s next for regulatory reporting?

    WATCH: What’s next for regulatory reporting?

    The webinar covers the following reporting regimes: 

    • MiFIR Transaction – Simon Appleton
    • MiFIR Post-Trade Transparency – Chris Machin
    • EMIR – Tim Hartley and Francesco Angelini
    • SFTR – Jonathan Lee 
    • CFTC and SEC – Alan McIntyre
    • MAS, ASIC and HKMA –  Tim Hartley and Francesco Angelini
    • Shareholding Disclosure – Angie Huff.
  • FCA shows flexibility on Short Selling Indicator for MiFIR transaction reporting

    FCA shows flexibility on Short Selling Indicator for MiFIR transaction reporting

    The FCA has made public its position on the Short Selling Indicator (SSI) for UK MiFIR transaction reporting. 

    Although we have been liaising with clients on this point for some time, it’s now been confirmed that where firms are aware of misreporting in relation to the SSI, they are not required to both cancel and replace those reports or notify the FCA of the misreporting via an errors and omissions notification form.  The FCA will keep this temporary measure under review.

    However, given this measure only addresses back-reporting, we would surmise that the FCA still expects firms to address erroneous reporting in their daily reporting flow until further notice.  Therefore Kaizen will continue to identify issues with the SSI that arise in our testing.

    This is an interesting development and a good example of a flexible and pragmatic approach by the FCA that will certainly be welcomed by the industry. Is this the shape of things to come from the FCA?

    Reporting obligations to EU regulators continue to apply and are unaffected by this announcement however ESMA announced it will be dropping the short-selling flag following its MiFID II Review in April last year.

  • FCA proposes ending transaction reporting of SFTs under UK MiFIR

    FCA proposes ending transaction reporting of SFTs under UK MiFIR

    The FCA recently published a quarterly consultation paper (No 34) in which they propose to completely exclude securities financing transactions (SFTs) from any MiFIR transaction reporting obligations under RTS 22. In particular, at present, while SFTs facing the Bank of England or a European System of Central Banks (ESCB) member as ‘Other counterparty’, are excluded from SFTR reporting, they are required to be transaction reported under UK MiFIR.  The proposal is for the requirement to report these transactions under UK MiFIR to cease, with effect from 31 March 2022.

    The industry will be very grateful for this very sensible change.  At present the requirement to provide MiFIR reports on central bank SFT transactions is very much a case of trying to push a round peg into a square hole. The MiFIR taxonomy is wholly inappropriate for reporting SFTs, with very little guidance available.  The resultant MiFIR reports appear sufficiently meaningless as to add no apparent value to regulators.  This proposed change comes alongside the FCA’s earlier removal of the obligation to report SFTs executed by non-financial counterparties. The additional move to eliminate all MiFIR SFT reporting demonstrates further pragmatism in keeping UK SFTR equivalent to the EU regime while listening to the industry’s operational concerns and taking a more pragmatic approach.

    Comments are to be sent to FCA by 17 January 2022.  

    • To read the consultation paper, please visit the FCA’s website.
    • For a conversation with Jonathan or one of our regulatory specialists about the above topics, please contact us.
  • In the news: Chris Machin speaks to Global Investor Group

    In the news: Chris Machin speaks to Global Investor Group

    The FCA confirmed it will remove the requirement for execution venues and firms to produce best execution reports and change the rules governing research provision to investment managers after a market consultation. Kaizen’s Chris Machin, Senior Regulatory Reporting Specialist, spoke to Global Investor Group on the matter.

    “As is widely known in the industry, Best Execution reporting has never been fully utilised, was seldom reviewed, and was complex and time-consuming. The FCA’s announcement is not the biggest surprise but will be applauded by industry participants, reducing unnecessary regulation, complexity and ultimately the cost of maintaining and reporting for investment firms.  It’s a big statement from the FCA and will be interesting to see what further divergence we see from them, as we head into 2022.”

    Read the full article here.  You must be a subscriber to view the article in full.


  • FCA uses MiFIR transaction reports to bring enforcement action

    FCA uses MiFIR transaction reports to bring enforcement action

    The recent FCA fine of an interdealer broker is another good example of how the regulator is repeatedly using transaction reporting data to investigate market abuse and financial crime. 

    In the final notice, released on 12 November, the FCA referenced that their investigation and conclusions in respect of the purported trading were based on a range of information including, in part, analysis of transaction reporting data received from six broking firms.

    The interdealer broker was fined £642,400, of which £407,273 was disgorgement, for having:

    • inadequate systems and controls to identify and mitigate the risk of being used to facilitate fraudulent trading and money laundering; and
    • not exercising due skill, care and diligence in applying its AML policies and procedures and in failing to properly assess, monitor and mitigate the risk of it being used to facilitate financial crime

    The interdealer broker ignored or failed to notice a series of red flags in relation to a trade in a stock it executed on behalf of a broker client.  The circumstances of the on-boarding and trading relating to that broker client ought to have prompted interdealer broker to consider the serious financial crime risks the trade posed, particularly given it was executed at nearly twice the prevailing market value of the stock.

    By having an audit trail of trading activity reported under the MiFIR Transaction Reporting regime, the authorities were able to piece together trading patterns that highlighted a circular pattern of transactions that included extremely large-scale purported OTC equity trading, back-to-back securities lending arrangements and forward transactions.

    The interdealer broker stated that it took a risk-based approach and deemed that it was not necessary to carry out any pre-trade or post-trade surveillance for a number of reasons, including that all transaction reporting was to be provided by regulated firms. 

    As well as emphasising the importance of the transaction reporting regime, this final notice reiterates the need for firms to have effective systems and controls to monitor their own trading and payment activity, regardless of whether MiFIR transaction reports have been submitted to the regulator.

    To read the final notice visit the FCA website.

    • For a completely independent assessment of the accuracy and completeness of your Transaction Reporting, please contact us.
  • ESMA updates MiFIR Transaction Reporting validation rules

    ESMA updates MiFIR Transaction Reporting validation rules

    In case you did not catch it, ESMA recently published updated 2022 MiFIR validation rules.  The changes are applicable from 31 May 2022.

    It is unlikely that any of these changes will impact Kaizen clients as these validations are already covered in our tests.  Firms should expect the additional validations to be implemented by their Approved Reporting Mechanisms and Competent Authorities going forward.

    Although the additional validations and clarifications make sense, this was a missed opportunity as a lot more could have been done and additional strengthening and tightening of the validation rules would have been helpful to firms.

    Here are the changes:

    • New validations have been introduced to check that the Buyer and Seller date of birth (fields 11 and 15), Buy and Sell decision maker date of birth (fields 20 and 24) should not be later than trading date.
    • Since sending an order to a trading venue does not constitute transmission, a new validation has been introduced to check that if the transmission of order indicator (field 25) is ‘true’, then the venue (field 36) must either be XOFF or XXXX.
    • As the country of branch membership (field 37) should only be populated for the market side of a transaction executed on a trading venue or on an organised trading platform outside of the Union, a validation has been introduced to check that this country of branch membership (field 37) is blank where the venue (field 36) is populated with ‘XXXX’ or ‘XOFF’ or a MIC pertaining to a Systematic Internaliser.
    • In addition, rule ID 117 relates to field 37 (Country of the branch membership) and previously included clarification that this field should not be populated for transactions executed on Systematic Internalisers (SIs). This clarification has now been removed given that this field is not applicable to SI executions.
    • Rule IDs 027, 043, 056 and 072 were updated to include clarification that the ‘EntityStatus’ shall be Active on the trading date in relation to Buyer & Seller ID codes and Buyer & Seller Decision Maker codes.
    • Rule ID 220 was updated in relation to Error Code CON-412 to clarify that the MIC also needs to be valid in the reference data on transaction date.
    • Rule ID 228 relates to field 57 (Investment decision within firm) and was updated to include clarification for cases when Buyer Decision Maker (Field 12) and Seller Decision Maker (Field 21) are left blank.

    • Rule ID 270 relates to field 36 (Venue): Clarification was provided that if ‘XXXX’ is populated in field 36, the full instrument description must be provided and the ISIN reported must not be present in reference data for the relevant trade date.

    • All other changes related to the addition of a number of CFI codes to a variety of validation rules and data fields, namely rule IDs:

    • 111 and 262 which relate to field 35 (Net amount);
    • 140 and 250 which relate to field 45 (Notional currency 2);
    • 154 and 264 which relate to field 48 (Underlying index name); and
    • 166 which relates to field 53 (Option exercise style).

    • For a conversation with Simon about the updated rules or to find out more about the quality of your MiFIR transaction reporting, please contact us.
  • Trade Reporting vs Transaction Reporting

    Trade Reporting vs Transaction Reporting

    Regulatory trade and transaction reporting is a strange beast.  I think most people fall into it by accident rather than choosing it (including myself), but people still get confused with the terminology and understandably so, as it does get complex.  Inconsistent wording across regulations doesn’t help, as they interchange between using the term ‘trade’ and the term ‘transaction’ and if you are lucky, a bit of ‘position’, even when it is the same regulator writing the rules. If you are sitting comfortably then I’ll begin (to confuse you)…

    MiFIR trade reporting

    Let’s start with MiFIR trade reporting (RTS 1 and 2). This is real-time trade transparency reporting, made public at the point of execution via an Approved Publication Arrangement (APA). Simple enough but MiFIR also has transaction reporting (RTS 22).  This is T+1 reporting of all transactions, either directly to the regulator or via an Approved Reporting Mechanism (ARM), to allow the European regulators to monitor market abuse.  Similar by name but very different in nature…

    Not to forget MiFIR also has its Commodities Derivatives Reporting (RTS 21) but that’s at position level.  Hold on…

    EMIR trade reporting

    EMIR has trade reporting where you report your derivative transactions to a Trade Repository (TR). That is of course unless you take up the option under EMIR to report some of your trades at position level instead! Keep up!

    Even though EMIR is more similar to SFTR transaction reporting than MiFIR trade reporting, both EMIR and SFTR mandate reporting to a Trade Repository and not a Transaction Repository. Yep, I’m lost…

    The good news is that the sensible people in the Asia Pacific region have tried to keep it consistent and retain the model of transaction reporting. HKMA, MAS & ASIC all use transaction reporting terminology.  Phew…

    Dodd-Frank Act price reporting

    The US Dodd-Frank Act (DFA) Part 43 price reporting, similar to MiFIR trade reporting, reports through a Swap Data Repository (SDR) that accepts data relating to (you guessed it) swap transactions, not a standalone publication tool like an APA.  Part 45 transaction reporting or swap reporting, also uses trade reporting terminology throughout.  Full circle, for CFTC commodities position reporting, all the terms trade, transaction and position are used.  HELP!!

    • Clear as mud?  Our team of ex-regulators and regulatory reporting specialists love talking about this stuff and can guide you though any reporting challenge. For a conversation about your trades, I mean transactions, across any of the global reporting regimes, please contact us.
  • ESMA admits MiFID II transparency still not achieved in derivatives

    ESMA admits MiFID II transparency still not achieved in derivatives

    There were some interesting comments at the recent FIA International Derivatives Expo (IDX) in London, where Natasha Cazenave, ESMA’s new executive director, discussed the EU regulator’s priorities in the derivatives markets and how its MiFID II review reports showed that it had met its “objectives of establishing sounder, more transparent and more integrated EU capital markets.”

    Cazenave summarised by recommending “less complexity, more effectiveness”, which is music to the ears of participants, investment firms and the regulatory infrastructure alike but surely that is what MiFID II was trying to achieve in the first place?

    Almost four years since the inception of MiFID II, frustratingly, transparency is still very much a work in progress.

    Data quality and transparency

    Cazenave does identify that poor data quality, complexity of transparency regimes and provisions for waivers and deferrals have not improved the level of transparency.  Again, for those of us covering MiFID II for a number of years, this was obvious. Hopefully, ESMA will simplify this going forward and perhaps as we continue to see divergence, the FCA will soon come out with its own streamlined requirements for optimum transparency. Cazenave highlights the CFTC success story in this space, in that market integrity can still be maintained alongside a more transparent trading landscape.

    Potential solutions

    And likewise, it has finally dawned on ESMA that a consolidated tape is not an easy thing to achieve. Frameworks need to be in place, complexity needs to be reduced, synergies in reporting increased and data costs are still high (let’s be honest, they always have been and always will be. We live in a data-centred world).

    So the question is, is ESMA finally going to bow down and admit that by de-facto it is actually the golden source of MiFID II European data and can hence go a long way to help with this?

    We saw earlier in the year the memorandum of understanding between ESMA and the FCA and there will be a further transition period. It makes sense that this is maintained, as Cazenave says, “given the interconnectedness of EU and UK Markets”.  My hope is that we will keep capital markets open, orderly and liquid as well as competitive, and one day we’ll get to true transparency.

    What’s next?

    In addition to the lack of transparency in derivatives, Cazenave explained that although ESMA is on a journey with regards to data quality, it is a key priority to make the best use of the data that it collects. ESMA is also keen to promote data-driven regulation, she said.

    Cazenave said that the numerous initiatives ESMA had put in place as part of its data strategy had really helped it improve data quality and that it is trying to work on standardisation of reporting requirements wherever possible including making sure that data is more usable for the relevant authorities and market participants alike. Something that will definitely be welcomed by the industry.

    To read the read the full speech, please visit ESMA’s website.

  • FCA Publishes 2021/22 Business Plan

    FCA Publishes 2021/22 Business Plan

    The FCA recently published its 2021-2022 Business Plan covering many areas within the wholesale and retail space. This provides further evidence and also aligns with its recent updates on regulatory reporting that it’s looking to be more assertive across the industry. We note that the FCA states that it needs to transform and change the way it does things given the recent challenges such as Brexit, the pandemic and technology are placing on them, and have outlined three key changes which are:

    • More innovative – taking advantage of data and technology to increase their ability to act decisively in the interests of consumers
    • More assertive – testing the limits of their powers and engaging with partners to make sure they bring their powers to bear
    • More adaptive – constantly learning and always adjusting their approach as consumer choices, markets, services and products evolve.

    In addition, there are several references to data quality, technology, automation and innovative data analysis that will allow them to identify risks to concentrate on more closely.  Hence, they will focus on the following during the next 12 months:

    • Data: Strengthen the foundations of their data, improving accuracy and accessibility. This will mean they can use it more effectively to identify harm and intervene more quickly
    • Information: Build capabilities to deliver automation and efficiencies, improve systems infrastructure and use technology to make operations more efficient
    • Intelligence: Use advanced analytical techniques to proactively identify and prioritise firms or harms for investigation.

    • To read the full FCA Business Plan visit its website.
    • For a conversation with Francesco or one of our regulatory specialists about the above topics, please contact us.
  • Complexity from simplicity – the INTC story

    Complexity from simplicity – the INTC story

    The replacement of the INTC code when aggregating client orders is one of the changes proposed by ESMA in its recent review of MiFIR Transaction Reporting.  On the surface this is to be welcomed, but do ESMA’s proposals go far enough?

    How INTC currently works

    When investment firms aggregate orders across more than one client, they are required to enter a value of ‘INTC’ in the relevant Buyer or Seller identification code field in their MiFIR transaction reports.

    It is by necessity that firms must use the ‘INTC’ aggregate client account as it’s generally not possible to allocate individual fills to specific clients until the aggregated order has been completed and an average price is known.  For example, if a firm is buying 100,000 Vodafone shares on behalf of three clients where Client A wants 25,000 shares, Client B wants 30,000 shares and Client C wants 45,000 shares, when reporting a first execution fill of 9,000 shares it’s not possible to accurately allocate the shares pro rata to all three clients in a single transaction report, so they must be linked using the INTC account.

    Essentially, the ‘INTC’ account is used to facilitate the reporting of the market-side executions and ‘warehouse’ the Vodafone shares until the order is completed.  Once the order is fulfilled, e.g. 100,000 shares at an average price of 113 pence then the three allocation transaction reports can be made showing the shares switching from the ‘INTC’ account into the accounts of client A (25,000), client B (30,000) and client C (45,000) all at the average price of £1.13 GBP.

    The INTC rules

    Use of INTC comes with a few simple rules:

    1. The INTC account must be flat at the end of each reporting day.
    2. INTC can only be used where orders from more than one client are being aggregated prior to execution. A client here, means a single LEI or single National Client Identifier.
    3. The timestamp on the allocations must be the time of the first fill trade
    4. Allocations would be at the average price of each of the fills.

    These rules seem simple enough, however in practice, they do lead to a great deal of complexity when trying to apply them to real world activity.  This has led reporting firms and system providers alike to struggle with certain real-world scenarios. A few examples are shown below:

    • Firstly, ensuring the INTC account is flat at the end of the day.  Firms that work orders over midnight UTC are effectively required to close their books at midnight and apply the allocations based on the fills accrued at that point, then start again with any post-midnight fills.  This of course would double the amount of allocation transaction reports required but also presents a scenario in which most systems have not considered. Trading in the APAC region often faces this challenge.
    • Secondly, some asset managers group orders across entities.  This is primarily driven by their best execution policy and group trading arrangements.  Where this happens, scenarios arise where only a portion of the fills may be allocated to reportable activity. 
    • Thirdly, where systems operate at sub-fund or sleeve level but they roll up to the same LEI, INTC should not be used.  Many systems are unable to cope with this.
    • Fourthly, regulators have asked where INTC is used for multiple client orders, but some allocations relate to the same LEI that they are rolled up into a single allocation for that LEI so that there are never two allocations with the same LEI for the same group order.

    ESMA’s proposal

    Challenges with the INTC account have led ESMA to suggest some changes which will allow NCAs to more easily review how an order is being reported.  ESMA is proposing that the generic and consistently applied ‘INTC’ account code is replaced by a code, internal to the investment firm but that uniquely links the market-side execution reports and the client-side allocation reports.

    What makes sense about ESMA’s proposal

    In terms of usefulness, it makes sense to replace the generic ‘INTC’ code with a unique code that links market side executions with the related client-side allocations.  This linkage is currently often difficult to do, particularly for firms that aggregate multiple orders in the same financial instrument at different points or throughout the same trading day.  It will also make it easier for firms to ensure that the ‘INTC’ account is flat at the end of every day and to more efficiently identify which specific transaction reports are leaving a position in the ‘INTC’ account.

    But….

    However, not proposing a separate field for what is effectively a “Group Order ID” could be a missed opportunity as it could have involved fewer coding changes for firms.  Importantly, it would have linked transaction reporting data with the related order record-keeping information. This would be hugely advantageous from a market abuse detection perspective.  The “Order ID” could also be applied to non-INTC related trades to further enhance the effectiveness of surveillance more broadly.

    Additionally, ESMA’s final report does not provide guidance or direction for instances where client orders are aggregated across more than one investment firm within the same financial group. This is a scenario where we have seen several firms have difficulties.

    Time will tell whether the FCA will follow ESMA’s lead or propose to use this as an opportunity to go further and create a powerful link between transaction and order data.

    • While ESMA’s proposed changes to MiFIR Transaction Reporting are at least a few years away, adequate implementation time will be required for firms to make the necessary changes.  For a conversation with Simon or one of our regulatory subject matter experts about these changes or how to get your transaction reporting into better shape, please contact us.  

    • Read our recent Industry Q&A on ESMA’s proposals here.
  • Kaizen Reporting Strengthens Regulatory Expertise

    Kaizen Reporting Strengthens Regulatory Expertise

    London, 15 July 2021 – Leading regulatory technology firm, Kaizen Reporting (Kaizen), is pleased to announce the expansion of its regulatory team with the hiring of three senior regulatory reporting experts. Francesco Angelini, Simon Appleton and Alan McIntyre join Kaizen’s existing specialists. They bring a wide range of experience and knowledge of the challenges clients face in the regulatory reporting space, and will be well placed to help clients meet some of those challenges through the application of Kaizen’s services and solutions.

    Dario Crispini, CEO at Kaizen said: “What sets Kaizen apart from other firms is its deep understanding of the global reporting regimes. We do this by hiring only the leading experts in each regime, whether that be EMIR, SFTR or MiFIR.  This expertise enables us to deliver the deepest and most comprehensive assurance services to the financial community.  So I am delighted to welcome Francesco, Simon and Alan to the Kaizen team. Their deep understanding of regulatory reporting and the complexities that firms face will enable us to better serve the needs of our clients and the industry at large.  By combining both regulatory expertise with advanced technology Kaizen continues to position itself as the leading regulatory technology firm.”

    Francesco Angelini – Senior Regulatory Reporting Specialist

    Francesco is a compliance and regulatory reporting specialist with extensive experience in the financial services industry. He joins Kaizen as a regulatory subject matter expert to support clients with their EMIR Reporting needs. Before joining Kaizen in February 2021, Francesco was Chief Compliance Officer at CME European Trade Repository.

    Simon Appleton – Director, MiFID II Transaction Reporting Subject Matter Expert

    Simon is a leading expert on MiFIR transaction reporting with over 30 years’ transaction reporting experience working at regulatory bodies, trading venues and for the last twelve years in a consultancy role helping banks, brokers, asset managers, wealth managers, ARMs and trading venues meet their MiFIR transaction reporting obligations. He is also one of the leading experts on market abuse and surveillance.  Simon is also alumni of the Financial Conduct Authority’s Transaction Monitoring Unit (TMU) now Markets Reporting Team where he covered both transaction reporting and surveillance and previously worked as a Director at Duff & Phelps providing consultancy services.

    Alan McIntyre – Senior Regulatory Reporting Specialist

    Alan is a leading G20 Reporting and DTCC Global Trade Repository expert and will be supporting Kaizen’s clients with their G20 reporting challenges, including the upcoming SEC and CFTC reporting obligations. Alan worked for DTCC on the EMIR rollout in 2014 and played a key role in building the GTR reporting platform. More recently, he helped DTCC by leading their Brexit programme and the rollout of separate FCA and ESMA trade repositories for EMIR and SFTR.

    In addition to expanding its regulatory team, Kaizen had also strengthened its business development and client support team with new joiners: Andy Green who has joined as Managing Director and Head of New Business Development, Colin Wallace who was Director and Head of Derivatives, Collateral & Securities Operations at Mizuho Bank Ltd in London joins to head up client on-boarding and Jean-Marie Mamodesen who joins as Managing Director and Head of European Sales.

    Kaizen also recently announced the formation of a new Advisory Board to address reporting quality within the industry and is made up of industry experts including Mark Ibbotson, David Lawton, Ana Fernandes, Catherine Langlais, Jonathan Herbst and David Nowell.  Kaizen has also grown its delivery and technology teams in the past 12 months, doubling in size to meet the increasing demand for its RegTech solutions.

    (ends)

    For more information, please contact James Dunseath, Communications Advisor, on +44 (0) 7557 955795 or media@kaizenreporting.com.

  • ESMA’s MiFID Review:  An FAQ on the Significant Changes Proposed to MiFIR Transaction Reporting

    ESMA’s MiFID Review: An FAQ on the Significant Changes Proposed to MiFIR Transaction Reporting

    It may seem just like yesterday when the industry was grappling with the introduction of new regulatory reporting requirements following the introduction of MiFID II.

    However, following the publication of ESMA’s MiFID II Review in April, there will be further changes to MiFID II, including to the Transaction Reporting regime.  The idea of MiFID 2.1 was hard baked into the MiFID directive.  As with MiFID I, it was recognised that the significant changes MiFID II introduced would necessitate a finessing of the rules at a later stage.

    In April and May, Kaizen Reporting held three events to brief clients and the industry on ESMA’s final report and the changes it recommends on the Level 1 text i.e. both MiFID and MiFIR.

    Approximately 250 clients attended our series of webinars on the MiFID Review. We received a great deal of positive feedback on the sessions as well as questions from the audience which we have published below as an FAQ for the industry. 

    ESMA’s MiFID II Review – Frequently Asked Questions (FAQ)

    1. Changes to INTC

    Will the INTC be replaced by a new code to recognise a firm, what will that new code do?

    The aim of the new code is not to identify the investment firm that’s aggregating orders across multiple client accounts. It is to replace INTC (order aggregation account) with what is effectively a grouped order identifier code.

    So, this could eventually link the transaction reporting regime with the order record keeping regime which is immensely powerful from a market abuse monitoring perspective. It will be a code that is unique to the firm and can be any code the firm wishes to use but it does need to be unique over time to the aggregated order and the related market-side executions and client-side allocations.

    However, we believe it would be more useful for ESMA to retain the ‘INTC’ flag as it is and introduce a separate field/flag for the new code so that firms won’t have to make changes and it becomes more visible where INTC and grouping is taking place. We would suggest the new code to be the order ID of the grouped order which should already exist in firms’ systems for the aggregation of client orders.

    Regarding the order ID, will this help the regulator identify combined reporting scenarios where there are multiple fills with one underlying client?

    Where you have a single client and multiple fills for that one client, these multiple records cannot be linked by the reviewer because INTC is not used in that circumstance. That is another reason why having a separate field for the grouped order ID would be useful.

    For more insights on INTC changes, please read Complexity from simplicity – the INTC story.

    2. The SI approach for determining reportability

    If you are given an ISIN through confirmation of an FX derivative but are not facing the SI directly, would you deem that as non-reportable even if the ISIN then appears on FIRDS following the RTS 23 submission?

    Unfortunately, it is more nuanced than that. You must decide if the ISIN is TOTV. If you trade an FX derivative and that derivative is admitted to trading on a trading venue, then it would still be reportable as it is today. However, if it is only on FIRDS via the SI and you are not facing the SI directly then it will not be reportable. The same will apply to interest rate derivatives.

    Is there a database for firms to search and therefore identify if they are trading with an SI? In particular for FX and CFDs.

    There is an existing, market solution called SmartStream RDU. If an SI wants to partake, they submit their data to this mechanism but it’s not mandatory and so it does not provide 100% coverage although participation in the scheme is high. Going forward, ESMA is hoping to create such a database. ESMA wants to have a proper solution with universal and comprehensive look ups, covering all instruments.

    3. Removal of the short-selling flag

    As the Short Selling indicator is being dropped, will the FCA expect corrections of historic reports where they may have been wrong?

    The changes proposed by the MIFIR Review have been published by ESMA and so we are yet to see the FCA’s stance in this regard.

    There is a backwards compatibility question. Under EMIR, we had multiple iterations of validations being introduced and changes to EMIR reporting, however, there was no backward compatibility. So, if you were being asked to re-report a trade under EMIR you would have to comply with the latest reporting obligations which is the retrospective application of the rules.

    Therefore, with the MIFIR Review, we would recommend raising the importance of backwards compatibility with trade bodies, ESMA and the FCA so that firms aren’t asked to put any new flags on historical reports or to assess reportability based on the revised instrument scope.

    In respect of how the short selling flag stands today, the FCA will continue to expect that to be reported. There’s currently no change on the FCA’s stance on backwards reporting so they’re still asking for 100% of records to be replayed.

    4. Scope changes for UCITS and AIFMs

    Can you run through the scope changes applied to UCITS management companies and AIFMs – where these are entities within the same Firm group entity (and not outsourced). Will this mean they are brought into scope?

    AIFMs and UCITS management companies providing one or more MiFID services to third parties will be required to transaction report.  Activity in relation to their own AIFs and UCITS funds will remain out of scope but reporting activity falling under their MiFID and so called MiFID “top-up provisions” will become mandatory.  This activity is a gap in the current surveillance net which ESMA is looking to close by levelling the playing field with asset managers authorised under MiFID.  Where AIFMs and UCITS management companies are required to report, there remains the option for them to transmit their orders to another MiFID investment firm under an Article 4 transmission agreement which would remove the need for them to make separate transaction reports. 

    5. Consistency with other reporting regimes

    Do the proposed changes create any inconsistencies/misalignment with reporting expectations under other regulations such as EMIR?

    Despite some calls to do otherwise, we believe it is sensible that ESMA continues to focus its efforts on harmonising the MiFIR and EMIR reporting regimes, where possible, without attempting to fully replace one regime with the other.  Given the significant differences between the two regimes as to what constitutes a reportable event or valuable information that is captured by each regime, the use of consistent and international data standards, reportable values, formats and methodologies is where further efficiencies can be made. This will naturally reduce costs and also help to increase the accuracy of data being reported.

    Will the FCA follow ESMA on the changes resulting from the MiFIR Review?

    We think that the selection by ESMA of which proposals to move forward with and which ones to drop has been sensible. If there is going to be divergence we expect the FCA to consult with trade bodies and then more broadly with firms to ensure everyone has their say. The FCA will consider the views of firms dual-reporting in the UK and EU and their desire for harmonisation. They’ll also consider firms that solely report to the FCA that may want a lighter touch. We have to remember that the FCA was the main advocate of transaction reporting in the first place and now relies heavily on these reports. We think they’re likely to adopt the vast majority of these proposals. We have yet to see what level 2 changes will be proposed by ESMA.

    6. Implementation timeline

    What is the timeline for when these changes will go-live and how long will firms have to implement the changes?

    We know that these proposals still have to go to the European Commission for approval and then to the European Parliament. That will take some time. The EMIR Refit is also happening at the same time and we would like to see an alignment of timings for the EMIR Refit and the MiFIR Review.

    In addition, we expect more changes under Level 2 and in the detailed RTS. Realistically, it is therefore likely to be 2-3 years before these changes go-live, and could be up to 3-4 years, so we anticipate it being 2023 to 2024.

    In terms of timing of implementation, it is costly for firms to make these changes, so adequate implementation time is required and it will be up to firms and their representative trade bodies to request and lobby for adequate implementation time.

  • WATCH: Kaizen CEO Dario Crispini on the Future of Regulatory Reporting with Alpha FMC and SteelEye

    WATCH: Kaizen CEO Dario Crispini on the Future of Regulatory Reporting with Alpha FMC and SteelEye

    In the last 12 months, the regulatory reporting landscape has become increasingly complex. A number of vendors have closed their reporting businesses and we have also seen reporting changes on the back of Brexit.

    Looking ahead, ESMA recently announced a proposed set of amendments to MIFIR transaction and reference data reporting regimes and there are a range of other upcoming changes, including the EMIR Refit and further anticipated divergence between the UK and EU.

    Kaizen CEO Dario Crispini joined Bernardo Castel-Branco from our consultancy partner Alpha FMC and Matt Smith from RegTech vendor SteelEye to discuss the past and future changes that are shaping the regulatory reporting landscape and what firms should be doing to improve their reporting in the long term.

    Watch the recording by visiting SteelEye’s website.

  • WATCH: Kaizen Reporting’s MiFID II Post-Trade Reporting service

    WATCH: Kaizen Reporting’s MiFID II Post-Trade Reporting service

    Watch our video to find out why it’s time to focus on the quality of your MiFID II Post-Trade Reporting data.

    RTS 1 and 2 of MiFIR require firms to report the financial details of their trades to an APA for publication to the market, as close to real-time as possible after the trade has occurred.

    As well as reporting in a timely manner, firms need to ensure that the data they’re submitting is accurate too. At Kaizen we don’t just check data samples – our multi-dimensional testing methodology has been adapted to meet the requirements of RTS 1 and 2 and provides a full, impartial quality assessment by testing every data field on every report.

  • MiFIR Transaction Reporting and the meaning of a ‘transaction’

    MiFIR Transaction Reporting and the meaning of a ‘transaction’

    Article 2 of RTS 22 outlines what does and does not constitute a ‘transaction’ for the purposes of transaction reporting under Article 26 of MiFIR.  What’s interesting is that only seven bullet points make up what is deemed a ‘transaction’ and therefore potentially reportable, whereas there are twice as many exclusions.

    It would be easy to assume that the shorter list is more important. However it should be remembered that not only does over-reporting constitute a rule breach, determining what must not be reported is where most of the complexity sits. 

    Many of the reporting problems we see in our quality assurance testing sit within the world of corporate actions and events. So the importance of documenting which actions and events are included and excluded from a firm’s reporting (including the rationale) cannot be over-stated.

    ESMA Q&A update

    ESMA has recently added to the list of examples of what does not constitute a reportable transaction by updating its MiFIR data reporting Questions and Answers (Q&A) document as part of its May 2021 publications. The key point to note is that “a voluntary switch to risk-free rates” is not transaction reportable under Article 26 as it would fall under the RTS 22 Article 2(5)(i) exemption. This means firms have some clarity around the impact of the decommissioning of LIBOR: there will not be a need to re-report LIBOR based swaps, including equity swaps that have a LIBOR component, as well as LIBOR-based interest rate swaps.

    This specific exemption covers the creation, expiration or redemption of a financial instrument as a result of pre-determined contractual terms, or as a result of mandatory events which are beyond the control of the investor where no investment decision by the investor takes place at the point in time of the creation, expiration or redemption of the financial instrument.

    All other minor changes to the Q&A also relate to section 18 which covers the ‘reporting of rates not included in RTS 22 and RTS 23’.

  • WATCH: ESMA’s MiFIR Review – what does it mean for transaction reporting?

    WATCH: ESMA’s MiFIR Review – what does it mean for transaction reporting?

    Kaizen’s CEO Dario Crispini and Regulatory Subject Matter Expert Simon Appleton, both former regulators, have reviewed the report which contains recommendations and possible legislative amendments to MiFID II/MiFIR. 

    In this live discussion Dario and Simon outline the key changes impacting firms in the EU and ask whether the UK regulator, the FCA, will follow suit.

  • Recent FCA fine shows importance of MiFIR Transaction Reporting

    Recent FCA fine shows importance of MiFIR Transaction Reporting

    A recent FCA fine of a boutique UK investment bank is a good example of how the UK regulator is using transaction reporting data to detect market abuse and financial crime. 

    In the final notice released last week, the FCA referenced that their investigation was (in part) based on their analysis of transaction reporting data and material received from the firm, which was fined £178,000 for “failings which led to the risk of facilitating fraudulent trading and money laundering.”

    At Kaizen we are often asked “what does the regulator do with all of this transaction reporting data?”. It is often a criticism levelled at regulators – do they actually do anything with the data?

    The answer is – yes they do. By having an audit trail of trading activity reported under the MiFIR Transaction Reporting regime the authorities were able to piece together trading patterns that highlighted “sophisticated and organised criminal activity”.

    Being a former regulator myself, I know first-hand that regulators are looking at the data and continually assessing, monitoring and considering a long list of offences, many of them not related to market abuse.

    ESMA’s recent review in relation to MiFID transaction and reference data reporting shows that they intend to use transaction reports to monitor other parts of the rulebook, including suitability and compliance with the buy-back programme safe harbour under the Market Abuse Regulation.

    Long gone are the days when regulators monitored firms by relying on visits and the review of prudential related returns. Given the sheer scale of trading activity and the fast pace in which markets evolve, having a database of transactions showing data elements that include traders, decision makers and who is buying and selling when and where, is extremely powerful.

    What’s crucial is that the reporting regime keeps up with market developments. Although the key proposals following ESMA’s recent review look sensible, there are a number of missed opportunities with a key one being in relation to cryptocurrencies where the level 1 text needs updating.

    The final notice also highlighted the need for firms to have effective systems and controls to monitor their own trading and payment activity. Having accurate and complete transaction reporting not only allows the regulator to meet its own objectives but should allow firms to detect unscrupulous activity as a first line of defence.

    Having confidence in UK and global markets is of paramount importance and given that the competition created by MiFID has led to a fragmented marketplace and trading environment, the need for regulators to have a holistic cross-market view through accurate and complete transaction reporting has never been greater.

    • To read the final notice visit the FCA’s website.
    • For a completely independent assessment of the accuracy and completeness of your Transaction Reporting or for a conversation with Simon about your transaction reporting challenges, please contact us.
  • Significant changes proposed to MiFIR Transaction Reporting by ESMA

    Significant changes proposed to MiFIR Transaction Reporting by ESMA

    It may seem just like yesterday when we were all grappling with the sweeping changes being brought by the introduction of MiFID II. But we all need to brace ourselves for the further changes that ESMA’s review of the MiFID II Transaction Reporting regime will bring.  The idea of MiFID 2.1 was hard baked into the MiFID directive.  As with MiFID I, it was recognised that the significant changes MiFID II introduced would necessitate a finessing of the rules. 

    ESMA’s review, partly delayed by both Brexit and Covid-19, has now delivered its final report on the changes it recommends on the Level 1 text i.e. both MiFID and MiFIR.  

    The revised reporting rules stemming from this review are expected to be finalised in a couple of years following the completion of the review of the Level 1 text and after more detailed industry consultation and approval by the EU Commission.

    ESMA’s key decisions around which proposals to pursue further and which ones to drop seem sensible at first glance and it seems that detailed consideration of responses to the consultation process has been made. That said, there are some potential missed opportunities too. 

    Here are some of the key changes being proposed or dropped:

    Which firms will need to report for the first time?

    Alternative Investment Fund Managers (AIFMs) and UCITS management companies providing one or more MiFID services to third parties will be required to transaction report this activity.  Under the proposed changes, activity in relation to their own Alternative Investment Funds and UCITS funds will remain out of scope for reporting but reporting activity falling under so-called MiFID top-up provisions will become mandatory. 

    This activity is a gap in the current surveillance net which ESMA is looking to close.  Where AIFMs and UCITS management companies are required to report, there remains the option for them to transmit their orders to another MiFID investment firm under an Article 4 transmission agreement which would remove the need for separate transaction reports to be made. 

    ESMA had originally proposed to make it an obligation for the receiving investment firm to report the transaction which pertains to a transmitted order, when the transmitting investment firm requests to transmit its orders.  However, this proposal has been dropped.

    What are the changes in reporting scope?

    One of the aims of MiFID II was to extend the reporting obligation to cover FX, interest rate and commodity instruments that had been subject to manipulation and abuse. Increased transparency in this area was seen as being vital to ensure the cleanliness and orderliness of the markets in which these instruments were traded. 

    It was expected that the majority of trading activity would be driven onto venues and would therefore be captured by the “Traded on a Trading Venue” (ToTV) obligation.  This then led to an extension of this concept to capture instruments that had commonalities to ToTV instruments leading to the need for lookups to ANNA DSB as well as FIRDS to establish reportability.  In reality this is a difficult and expensive process so one proposal is to replace the ToTV commonalities concept with the “SI approach”. Under this approach, derivative instruments that are exclusively traded through SI systems and all derivatives belonging to the same sub-asset class would have to be reported under Articles 26 and 27 of MiFIR and made transparent. 

    This extension to scope would only be applicable to SIs and their counterparties. It would not be applied to non-SI firms trading against each other in the same instruments nor interestingly, would it apply to any DEAL trades with underlying clients carried out by the non-SI counterparties.

    The idea is that this proposal will succeed in giving a more complete view of the market whilst simplifying some of the existing reporting complexities. We can see a few challenges and issues with this proposal however, which we will cover in more detail in a future blog.

    What changes are being proposed to the data content?

    Two new additional data elements are being added to the transaction reports. These are:

    • A buy back programme (BBP) flag
    • MiFID client categorisation flag

    The BBP disclosure obligations are seen as been overly burdensome across the industry.  So including a flag in the transaction report may enable the obligation under Article 5(3) of MAR to be removed and could also facilitate a more efficient approach to monitoring compliance with this ‘safe harbour’ within MAR.  

    The MiFID client categorisation flag is being proposed to allow NCAs to monitor the distribution of certain complex products to investors or identify market trends when analysing the data on transaction reporting. 

    These changes would be consistent with the idea of improving the efficacy and efficiency of overall data provision by firms but it also means that the accuracy and completeness of the transaction reports becomes even more vital for regulators.

    It is not surprising to see the regulators looking to utilise transaction reports for the monitoring of suitability and other areas beyond market abuse.  This is consistent with ESMA’s data strategy which involves using data more efficiently to minimise the number of separate data requests submitted to firms. 

    INTC changes

    Where orders are aggregated across multiple clients a pseudo account “INTC” is used to provide linkages between the market-side fills and the allocations to the clients.  The proposed change is to require firms to use a code unique to the reporting firm instead of the simple character set “INTC”.

    This change will certainly make the data more meaningful to the regulators but will also help firms internally when analysing their transaction reports.  The use of INTC and the specific rules around its use represent one of the most difficult aspects of transaction reporting.  As grouping of client orders prior to execution is typical of asset and wealth management firms, this change will lead to significant new challenges for these firms and their system providers.

    My view is that it would be preferable to keep the status quo in terms of how systems are coded to handle the reporting of the INTC account but introduce a separate field to hold what is effectively a grouped order ID. Such a field would also be useful in allowing all transaction reports related to a single order to be grouped together.  This transparency is often very helpful when analysing trading activity and is a missed opportunity as it would involve fewer coding changes and would provide a link between the transaction reports and the orders maintained under the order record-keeping requirements. 

    What’s going?

    The short selling indicator.  One of the most frequently misreported fields is to be removed. This will certainly be welcomed by firms not least because we now have divergent requirements between the FCA and EU reporting rules.  However, the need for regulators to have transparency of short selling activity seems to be greater than ever given the real possibility of short selling squeezes being coordinated through social media.

    Going forward

    As all firms know, applying corrections to historic transaction reports is mandatory under RTS 22 Article 15.  Any proposals to change reporting obligations should consider and deal with the question of backward compatibility.  To require back reports to be made under new reporting requirements is effectively the retrospective application of the regulations.  So, to avoid this, any proposals for change should include provisions to deal with any such back reporting so that replay records would not need to implement the new flags or the replacement INTC code. 

    From an implementation perspective, it would be best if the timing of implementation of these changes is aligned with any transaction reporting changes proposed by the FCA.  We believe a lot of the proposed changes will be welcomed by the FCA and we would support consistency of reporting across regulations which reduces costs and increases data accuracy. 

    Our verdict?

    These are just the level 1 changes.  Most of the action takes place at level 2 and 3 in the delegated regulations, guidelines and Q&As.  There are a whole slew of areas where improvements can be made here and we look forward to ESMA’s proposals.  

    Whatever the outcome, ESMA recognises the need to have better quality data and to ensure it meets the needs of 21st century regulation.  This is just the second step in that journey. 

    • Kaizen exists to help improve the quality of regulatory reporting data.  For a conversation about ESMA’s proposed changes to MiFIR transaction reporting or any transaction reporting challenges, please get in touch.

    • To read ESMA’s Final Report please visit their website.
  • Kaizen CEO Dario Crispini to speak at TISA Transaction Reporting Forum

    Kaizen CEO Dario Crispini to speak at TISA Transaction Reporting Forum

    This January marked the three year anniversary of MiFID II’s implementation, a complex piece of regulation meant to enhance investor protection. During the past three years, the industry has been sharing best practices on how to overcome MiFID II implementation challenges, resulting in some positive changes. However, when it comes to transaction reporting, challenges remain with firms still grappling to adopt the right regulatory reporting process; to put in place the right controls to correctly meet obligations. 

    Kaizen’s CEO Dario Crispini joins a line up of speakers including Tom Soden, the new head of the FCA Markets Reporting Team (Dario’s former job!), at the Investing and Saving Alliance’s (TISA) Transaction Reporting Virtual Forum. 

    When: Thursday 29 April 
    Time: 9.30-12.30am BST

    Hear about the latest regulatory developments and expectations and get an insight on how to counter reporting risks and overcome all remaining challenges and obstacles that the industry faces.


  • The Kaizen Helpdesk one year on

    The Kaizen Helpdesk one year on

    A year ago, at the start of the pandemic, we launched the Kaizen Helpdesk to provide our clients with direct access to our team of regulatory specialists and test analysts. Our goal was to improve support and enable clients to raise any questions about their ReportShield™ testing and reconciliation results while many were working remotely from home. 

    What is the Kaizen Helpdesk?

    The Kaizen Helpdesk provides an instant way to communicate with our team of specialists either for technical queries relating to the regulation itself, or for data issues with your ReportShield Accuracy Testing and Reconciliation results. When submitting an enquiry, clients can highlight the exact service and regulation their question relates to, ensuring it reaches the correct recipients immediately. Clients can also attach documents, spreadsheets, emails and screenshots directly into the comment box for the Kaizen team to review.

    Any question can be submitted to the Helpdesk and it’s designed to encourage:

    • Efficiency – direct access to the entire team of Regulatory Specialists, Data Analysts and Relationship Managers, avoiding your message being lost in crowded inboxes or receiving an Out Of Office reply
    • Transparency – your request will be shared with your fellow colleagues with Helpdesk access
    • Auditability – requests are never archived and don’t disappear if the user leaves the organisation
    • Traceability – to prevent duplication of Q&A and provide evidence of decisions made
    • Tracking  – of changes to client’s business and data discovery profiles or Kaizen’s test parameters.

    How long will it take to process my enquiry?

    The Helpdesk is monitored by our team of regulatory specialists, relationship managers and support functions to ensure that queries are dealt with as quickly as possible. We aim to respond to clients and resolve enquiries within 24 hours.  If you need urgent assistance, please contact your Relationship Manager or support contact quoting your Kaizen Helpdesk reference and they’ll assist with escalating your enquiry.

    Future Plans

    We have received great feedback on the Kaizen Helpdesk over the past year and the number of clients using the service continues to grow.  As a result, we have been gathering feedback to design and launch a new, improved Helpdesk which is currently in testing. Watch this space for further announcements on the new Helpdesk service with additional functionality in due course.

    • As always, if you have any suggestions or feedback on how we can improve any of our services, including the Helpdesk, please contact us. And keep raising those questions…
    • If you’re not a client and would like more information about our ReportShield services and how you can access our Helpdesk, please also get in touch! 
  • WATCH: MiFID II Transaction Reporting trends with Kaizen’s David Nowell

    WATCH: MiFID II Transaction Reporting trends with Kaizen’s David Nowell

    In this video, Kaizen’s Senior Regulatory Reporting Specialist David Nowell talks about what we can expect to see from MiFID II transaction reporting in 2021.

    David, a former FCA regulator, covers the following topical issues:

    1. What can we expect from see from MiFID II in the coming months?
    2. What are the main MiFID II reporting issues that firms should be looking out for?
    3. What is the difference between FCA Transaction Reporting and EU Transaction Reporting?
    4. What should firms have in place now that the UK has left the EU? What likely changes might we expect to see down the line?
    5. What are regulators expecting now?
    6. What are the main risks of poor regulatory reporting practice?
    • For a virtual discussion of your own with David or one of our regulatory reporting specialists, please contact us.
  • WATCH: An Introduction to Kaizen Reporting

    WATCH: An Introduction to Kaizen Reporting

    Watch Kaizen’s CEO Dario Crispini explain what led him to set up Kaizen Reporting, what makes our quality assurance services unique, and how we are helping financial firms achieve accurate and complete reporting.

  • WATCH: MiFID II Post-Trade Reporting trends in 2021 with Kaizen and SmartStream

    WATCH: MiFID II Post-Trade Reporting trends in 2021 with Kaizen and SmartStream

    What are the key developments when it comes to MiFID II Post-Trade Reporting this year? What impact might Brexit have? What should Systematic Internalisers be focusing on?

    We caught up with Kaizen’s Senior Regulatory Reporting Specialist Chris Machin and SmartStream’s EVP Reference Data Utility Linda Coffman and asked them the following:

    1. What can we expect from see from MiFID II Post-Trade Reporting this year?
    2. What are the main MiFID II Post-Trade Reporting issues that firms should currently be looking out for?
    3. What should firms already have in place now that the UK has left the EU and what likely changes might we expect to see down the line?
    4. What will regulators be expecting now in terms of MiFID II Post-Trade Reporting?
    5. What are the main risks of poor regulatory reporting practice?
    • For a virtual discussion of your own with Chris or Linda or with one of our regulatory reporting specialists, please contact us.
  • Kaizen Reporting in the news 2020

    Kaizen Reporting in the news 2020

    17 December 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – Emir and Mifir – all effort no value

    2 December 2020: Dario Crispini spoke to Justin Pugsley at Global Risk Regulator – Regulators FCA ponders UK rules post-Brexit

    6 November 2020: David Nowell spoke to Wendy Lisney at Global investor group – Brexit data split raises systemic risk concerns – expert

    28 October 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – EU and UK diverge on Mifid II options as Brexit nears

    13 October 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – Brexit: firms brace for immediate enforcement

    5 October 2020: David Nowell spoke to Sam Wilkes at Risk.net – Escape from Emir? Not so fast, swaps users


    9 September 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – Data Reporting RTS 22

    18 August 2020: Jonathan Lee featured in the Securities Lending Times – SFTR Diaries

    23 June 2020: David Nowell spoke to Securities Lending Times – EMIR Refit may have regulators seeing double

    26 May 2020: Jonathan Lee spoke to Securities Lending Times – Beware of valid but wrong SFTR reports

    12 May 2020: Ian Rennie spoke to Alice Tchernookova at Practice Insight (IFLR) – SMCR: Covid-19 could impact firms’ compliance

    6 April 2020: David Nowell spoke to Peter McGill at Global Risk Regulator – More banks likely to face regulatory sanctions as UK toughens stance on reporting

    26 March 2020: David Nowell spoke to Alice Tchernookova at Practice Insight (IFLR) – Emir reporting: new guidelines are good but need wider takeup

    26 March 2020: Jonathan Lee spoke to Jimmie Franklin at International Financial Law Review – PRIMER: Securities Financing Transactions Regulation / SFTR

    25 March 2020: David Nowell spoke to Alice Tchernookova at Practice Insight (IFLR) – How today’s coronavirus crisis will shape tomorrow’s regulatory landscape

    25 March 2020: Jonathan Lee spoke to Sam Wilkes at Risk.net – SFTR confusion over Esma’s coronavirus delay

    17 March 2020: Securities Lending Times interviews SFTR Specialist Jonathan Lee.

    9 March 2020: Dario Crispini and Patrick Ludden spoke to Luke Jeffs at FOW – Kaizen hires expert amid increased regulatory scrutiny.

    9 March 2020: Dario Crispini and Patrick Ludden spoke to Justin Lawson at Securities Lending Times – Regulatory reporting specialist joins Kaizen.

    9 March 2020: Dario Crispini and Patrick Ludden spoke to Mondovisione – Patrick Ludden is the latest senior hire to join the Kaizen team.

    28 February 2020: David Nowell spoke to Jimmie Franklin at International Financial Law Review about the EMIR refit – PRIMER: Emir refit

    19 February 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – Industry concerned by Mifir dark trading proposal

    7 February 2020: Jonathan Lee spoke to Ben St. Clair at Risk.net – Non-EU hedge funds stage surprise escape from SFTR

    3 February 2020: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – ‘No meaningful use’ for Mifid best ex reports

    16 January 2020: Jonathan Lee spoke to spoke to Alice Tchernookova at Practice Insight (IFLR) about the SFTR final guidelines released by ESMA – SFTR guidelines: too little too late.

    14 January 2020: Chris Machin spoke to Alice Tchernookova at Practice Insight (IFLR) about consolidated tape – EU financial regulation in 2020; what to expect (part III) 

    10 January 2020: Chris Machin spoke to Alice Tchernookova at Practice Insight (IFLR) about predictions on MiFID III – EU financial regulation in 2020: what to expect

    9 January 2020: Kaizen Reporting spoke to Chris Kentouris at Fin Ops – Regulatory Ops 2020: Handling Tower of Acronyms

    7 January 2020: David Nowell spoke to Rachel Wolcott at Thomson Reuters Regulatory Intelligence – Quality assurance, improved governance should top firms’ transaction reporting priorities in 2020

    2 January 2020: Dario Crispini spoke to Drew Nicol at Securities Lending Times – Kaizen Reporting adds to SFTR team

    1 January 2020: Dario Crispini spoke to Reg Tech 100 – Quality Assurance in Regulatory Reporting

    Click here to check our media coverage from 2019. 

    To speak to one of our regulatory experts, please contact Fiona Wilde, Head of Communications, on +44 (0) 203 912 3271 or media@kaizenreporting.com

  • RTS 2 Non-Equities Trades: Are you ready to publish within five minutes?

    RTS 2 Non-Equities Trades: Are you ready to publish within five minutes?

    In January, with a year to go, I reminded people in a blog that the timing for the publication of RTS 2 non-equities trades was reducing from 15 minutes to five minutes. The change in January 2021, comes three years after MiFID II’s inception. One of the regulation’s objectives was to push investment firms for further transparency through automation and electronification, specifically of the fixed income market where voice-trading still plays a major part.*

    RTS 2, Article 7 states: “…for the first three years of application of regulation No 600/2014, within 15 minutes after the execution of the relevant transaction; thereafter, within five minutes after the execution of the relevant transaction.”

    Three months to go

    Now we are in October, we find ourselves only three months away from this change in regime.  Are you ready?  Does Front Office IT have this on their book of work to implement over New Year?  Have traders been made aware of the procedural changes?  If not, you are running out of time and with multiple other regulatory moving parts, as well as the B-word to contend with, my advice is make sure this gets raised as soon as possible.

    My four main areas to prepare are:

    • Make sure your Front Office IT have this on their book of work and FIX messaging is tested
    • Ensure communication to Front Office happens well in advance, for any non-automated trading flows and to those teams that are monitoring real-time trade reporting and rejections
    • Work with your APAs if there is any uncertainty. Make sure you understand rules or logic that you have in place and keep up-to-date with the latest version of their FIX specification
    • Validate that Senior Manager Functions for SMCR are aware and happy with the changes to reporting and they have been proceduralised.

    9% of trade reports currently don’t meet the deadline

    Through Kaizen’s Accuracy Testing we have found that nine per cent of tested RTS 2 non-equities trade reports are not meeting their 15 minute real-time obligation after execution. If you’re not able to meet the 15 minute deadline, how will your internal processes meet the five minute requirement of MiFID II RTS 2, come January next year?

    This is where we can help.  Our Accuracy Testing Service for MiFID II Post Trade Transparency Reporting (PTT) for RTS 1 & 2 helps firms identify and understand errors in their reported data to ensure that you are able to meet your regulatory reporting obligations.  Please contact us for a conversation with Chris or one of our regulatory specialists.

    *RTS 1 Equities remains unchanged at 1 minute.

  • How to report UK nationals if there is a no-deal Brexit

    How to report UK nationals if there is a no-deal Brexit

    We were hoping for a different outcome but unfortunately for firms reporting to EU National Competent Authorities (NCAs), the approach to reporting UK nationals will change if there is a no-deal Brexit.

    Happily there is no change for firms reporting to the FCA. 

    Wouter van Bronswijk who leads reporting at the AFM, the Dutch regulator, confirmed at a recent Infoline Trade and Transaction Reporting Conference that based on the regulations, the UK would become a third country. This means that firms reporting to EU NCAs will have to change the way in which:

    1. They prioritise the nationality to use for individuals who have more than one nationality of which the UK is one;
    2. They change the preferred identifier to use for UK nationals.

    Determining the nationality to report

    Where an individual has multiple nationalities there is a waterfall approach to determine what nationality to include in the transaction reports. This will apply to traders and clients that are natural persons. 

    The steps are:

    • Use the first EEA country based on the country code when sorted alphabetically
    • If there are no EEA nationalities then it is the first non-EEA nationality based on a sorted country code
    • If the UK is the nationality, then the passport number is the preferred identifier and if that does not exist the CONCAT should be used.

    All those UK National Insurance numbers that firms had been diligently collecting cannot be reported to EEA NCAs post-Brexit. 

  • Systematic Internaliser (SI) regime for OTC derivatives comes into play

    Systematic Internaliser (SI) regime for OTC derivatives comes into play

    Today the Systematic Internaliser (SI) regime for OTC derivatives comes into play, over two and a half years after MiFID II’s inception. Whereas the equities SI regime was introduced a few months after go-live, and bonds in September 2018, the reference data quality for OTC derivatives was not of the standard required for Systematic Internaliser thresholds to be understood and calculated, hence the delay until now.

    Systematic Internalisers must now comply

    Previously, the main sell-side SIs had ‘opted-in’ to being an SI, without having the mandatory requirements that come with being an SI.  Now, if firms are meeting the various thresholds for trading  – Organised, Frequent, Substantial and Systematic – they have to comply with the obligations set out by MiFIR and MiFID II in relation to pre & post trade transparency, best execution and reference data. Importantly, they also have to keep their buy-side clients informed.

    Multiple asset classes

    The complexities arise with OTC derivatives and the multiple sub-asset classes and sub-classes. We are working with the industry solution for the source of Systematic Internaliser aggregated data, Smartstream RDU. Their SI registry is crucial so that we can understand the granularity of SI status, which in turn helps us to understand the reporting responsibility. This is an essential part of Kaizen’s MiFID II Post-Trade Reporting Accuracy Testing service. If you would like to check the accuracy of your Post-Trade reporting, please contact us for a conversation with one of our specialists.

  • Kaizen joins FCA, AFM at the Trade and Transaction Reporting Conference

    Kaizen joins FCA, AFM at the Trade and Transaction Reporting Conference

    Please join us at this year’s Trade and Transaction Reporting virtual conference where our CEO Dario Crispini joins a stellar line up of speakers from regulators, trade bodies and industry participants across Europe. 

    Dario joins a panel with Ana Fernandez, the manager of the Markets Reporting Team from the UK’s FCA, and Wouter van Bronswijk from the Netherlands’ AFM, to discuss one of our favourite topics – strengths and weaknesses of data and reporting under MiFID II. 

    With plenty of other topics including an update from ESMA on SFTR reporting, and preparing for transaction reporting after Brexit, it’s a great opportunity to get up to speed on all things regulatory reporting for buy-side and sell-side firms, market infrastructures and third party providers.

    When: Wednesday 23 September
    Time: 8.15am-5.20pm

    For more details and to register visit the Trade and Transaction Reporting conference website.

  • FCA release Market Watch 65

    FCA release Market Watch 65

    Another day another Market Watch newsletter.  Without a commute out to Stratford, the FCA’s Markets Reporting Team (MRT) has been busy during lockdown using that additional time to look at the quality of some of the transaction reports they’ve been receiving. They’ve issued some further reminders on areas where they are seeing reporting issues, and what control arrangements firms are required to have in place.  

    Systems and controls

    In its commentary, the MRT point out that firms need to have access to a deep understanding of the reporting requirements that is sufficient to identify errors that may not be highlighted by a reconciliation.  In my experience, most reconciliations being performed only scratch the surface and fail to reconcile back to source; which will be the trade table in each Order Management System. Even the full reconciliations we conduct at Kaizen will not identify all issues. Where a value in the source system is dutifully carried through to the transaction report, it does not prove it is correct.  Timestamps, incorrect reference data, price and price type, these are all areas where accuracy testing is required. 

    Further, as we get deeper into MiFID, both EU regulators and the FCA will expect deeper accuracy testing where all issues can be tested for.  Only by performing deep testing can management and the FCA alike take comfort that the test results provide a true picture of reporting quality.  Lighter touch testing, whilst a cheap and easy fix, will not satisfy this obligation.

    Cessation of ARM services

    As a reminder, the FCA notes that where a data reporting service provider has indicated it will cease provision of its services, it is up the affected firms to make the necessary arrangements to ensure their reporting continues unimpeded. 

    Firms that currently use NEX Regulatory Reporting will by now know they need to put alternative arrangements in place.  If you need any assistance, either in selection of an alternative provider, or in the implementation and quality control testing that would be required, we can help.

    Specific reporting issues commented upon in Market Watch 65

    Unreported transactions: it seems the FCA believes some firms are not assessing reportability properly.  This can be a problematic area and firms must be very careful when making their assessments.  Fortunately, we re-perform all reportability assessments which helps ensure completeness of reporting but also captures changes in reportability due to late changes to FIRDS. 

    Late reports: this is an interesting one because despite the best efforts of firms, there will always be some instances where transaction reports will be submitted late after the T+1 deadline has passed.  What the FCA is most concerned with, is where the systems and controls to enable timely reporting are not in place.  

    Country of branch for the buyer/seller: MRT reiterates that these fields are to be populated only for clients and with the branch or head office country code that received the order or generated an order under a discretionary mandate.

    We often see issues with this field but it is a relatively easy one to fix and will help greatly improve reporting quality. 

    Trading Venue Transaction Identification Codes (TVTICs)

    Firms are failing to report the right code consistently.  This can be caused by processing issues or a failure to convert the values received in FIX messages in line with the specific trading venue’s instructions. If you are not sure on the requirements here, please get in touch.

    Immediate underlying

    Again, MRT is at pains to remind firms that they should be evaluating reportability of a derivative instrument based on the “immediate underlier” where the derivative itself is not found on FIRDS. 

    This problem arises where a derivative has a derivative underlier i.e. there is a chain of derivatives.  In such cases the immediate underlier will be a derivative.  For example, where a CFD is traded on an equity option, the underlier is the option, NOT the equity shares.  This principle will extend to assessing the instrument’s reportability and to filling in the supporting instrument fields 42-56: they should reflect the values for the immediate underlier.

    Dealing with errors and omissions

    The FCA has a standard form that must be completed.  Whilst being quite scary for those named on the form it does assist the FCA in its general monitoring efforts and they have asked that firms submit these promptly and not to wait until after an issue has been fully resolved. 

    They also remind firms that errors and omissions will need to be remediated with back reports/replays of the impacted activity. 

    If you want to know more or need assistance on any of the above please contact us and we’d be happy to help. 

  • FCA Release Market Watch 64

    FCA Release Market Watch 64

    Today, the FCA published Market Watch 64 and it is the shortest Market Watch ever. On the face of it, it appears to have nothing new to say. However, it does contain an important warning for firms that are struggling to be ready for the Brexit changes at the end of the year:

    “..firms and Approved Reporting Mechanisms should comply with the changes to their regulatory obligations by the end of the transition period on 31 December 2020. Firms that are not able to comply fully with the regime immediately following the end of the transition period will need to be able to back-report missing, incomplete or inaccurate transaction reports as soon as possible.”

    It would be easy to forget the significant impact Brexit will have on transaction reporting, but Market Watch 64 clearly signals that this is not an option. If you are unsure how Brexit will impact your reporting obligations, why not talk to Kaizen. Please contact us for further details on Brexit reporting implementation, our quality assurance, reconciliation, governance and training services.

    Market Watch 64 Newsletter


  • Transaction Reporting How-to Guide: ‘Venue’ Field

    Transaction Reporting How-to Guide: ‘Venue’ Field

    On the face of it, the ‘Venue’ field in transaction reporting seems to be fairly straightforward – as the RTS states, it is simply the “identification of the venue where the transaction was executed.” Unfortunately, it is not quite as simple as it first seems and we detect a large number of errors with this field in our ReportShield™ Accuracy Testing.

    Why is the ‘Venue’ field so important?

    Every field is important to the regulators and Article 26 of MiFIR demands complete and accurate reporting. However, accurate population of the Venue field is particularly important for firms due to the impact it has on the population of associated fields. If it is populated incorrectly, it could result in a ‘CON 412’ error from the regulator and your report will be rejected.  It also impacts how ‘TVTIC’, ‘Trading date time’, ‘Country of branch membership’ and fields 41-56 need to be populated. So it is essential that you fully understand the intricacies of this field and don’t fall into any of the following traps.

    ‘Segment’ versus ‘Operating’ level MICs

    The Market Identifier Code (‘MIC’) used to be a straightforward standard – you had one exchange and one four character code to identify it. For example, ‘XLON’ was the sole identifier for the London Stock Exchange. However, this was far too easy and exchanges are increasingly moving to a segment level structure resulting in a MIC for each segment. For example, the London Stock Exchange has ‘XLON’ as its ‘operational level’ MIC, but also has the following ‘segment level’ MICs:

    • AIMX – London Stock Exchange, AIM MTF
    • XLOD – London Stock Exchange, Curve Global Markets
    • XLOM – London Stock Exchange, MTF,
    • XLON – London Stock Exchange

    Golden Rules:

    1. Use the segment level MIC for transactions executed on a trading venue, systematic internaliser or non-EEA trading platform.
    2. Only use the operational level MIC where the segment level MIC does not exist.

    This is so important because if you used the operational level MIC by mistake, it will sail through ARM validation, but will probably result in a CON 412 error from the regulator. This is because the ISIN you have used in field 41 doesn’t only have to be on FIRDS on the trading date – it also has to be with the correct segment level MIC. So if you have traded an AIM stock, populated the ISIN correctly but have populated the Venue field with ‘XLON’ rather than ‘AIMX’, it will be rejected.

    The ‘XOFF’ versus ‘XXXX’ conundrum

    Another common error made by firms is in the use of ‘XOFF’ instead of ‘XXXX’ and vice versa. This is understandable as they sound similar and are both used for off market trades. In an effort to be precise, some of the language in the RTS can also appear confusing. It is absolutely essential that you understand the difference between the two as it can have a major impact on whether you need to populate the instrument identifier.

    Golden Rules:

    1. Use ‘XOFF’ for instruments that are tradeable on an EEA trading venue but where the trade has been made off market (i.e. not executed on a trading venue, SI or non-EEA platform).
    2. Use ‘XXXX’ for instruments that are not tradeable on an EEA trading venue and are traded off market (i.e. not traded on a non-EEA platform).

    Exchange MIC or ‘XOFF’/’XXXX’

    Another thorny issue we’ve discovered is the use of an exchange MIC when the trade was actually made off market. The Venue field should only be populated with the exchange MIC if the transaction was executed on a Trading Venue. Section 5.4 in the ESMA Guidelines document is a little complicated, but the key statement is “Where an Investment Firm is not the direct market facing entity the Investment Firm is not regarded as executing on the Trading Venue for the purposes of transaction reporting.” So if you are making a transaction against a broker and that broker makes a trade on the London Stock Exchange to facilitate the trade, you should populate the venue field with ‘XOFF’ rather than ‘XLON’ as you are not the direct market facing entity.

    How we help

    Firstly, if you are unsure about any of the reporting standards, or just need a refresher, we would heartily recommend our core training course which will help ensure you are interpreting the MiFIR transaction reporting details correctly.

    If you have any doubt about whether you have been reporting correctly, this is what our Accuracy Testing is designed for. We can take all the transaction reports you have submitted over any given period and apply multiple tests for each data field that comprises a report. As many firms have discovered to their cost, there is no point hoping for the best when it comes to reporting. You need to have total confidence that your reporting is complete and accurate to avoid costly remediation and regulatory scrutiny. 

    • Please contact us for further details on our quality assurance, reconciliation, governance and training services.
  • ESMA releases new EMIR and MiFIR Q&As

    ESMA releases new EMIR and MiFIR Q&As

    Hallelujah, it’s positively raining regulatory reporting Q&A!

    Yesterday (8 July), ESMA published new Q&As for both EMIR and MiFIR data reporting. However, you can put away your brollies as there isn’t a great deal happening in either of them.

    EMIR – amendment to TR Question 11(b)

    The EMIR Q&A makes an amendment to TR Question 11(b) to clarify that counterparties should follow their local time and the relevant calendar of their member state to specify the “working day”  in the context of determining the deadline for reporting under EMIR. Of course this does not alter the fact that all timestamps in the EMIR trade report fields should be expressed as Coordinated Universal Time (UTC).

    MiFIR – two reporting scenarios added

    The only addition in the MiFIR Q&A is the addition of two reporting scenarios where an investment firm executes a transaction through an execution algorithm provided by another firm (Transaction Reporting Question 13). We would note that it is essential to carefully read footnote 51 in the Q&A in order to fully understand the reporting scenarios.

    If you have more questions than answers on EMIR trade reporting and MiFIR transaction reporting, our training courses can help you avoid some of the pitfalls of these complex regulatory reporting regimes. During the lockdown period, we are offering these courses remotely at a significantly reduced cost. For more details, please see our training pages. 

  • FCA publishes Market Watch 63

    FCA publishes Market Watch 63

    The FCA signals that it will not relax its demands for complete and accurate transaction reporting.

    In its latest newsletter on market conduct and transaction reporting issues, the FCA sets out its expectations of market conduct in the context of increased capital raising events and alternative working arrangements due to Covid-19. The focus of the newsletter was firmly on market abuse however there was a very clear message that transaction reporting is a key tool in its efforts to combat market abuse.

    While the FCA acknowledged the operational challenges created by the Covid-19 crisis, it also made clear its intention to continue to use its powers to request information and “may ask market participants to provide further information on their activities to explain how they are meeting their regulatory obligations”.

    Right controls around market abuse

    Market Watch 63 stresses that it is “as important as ever that the right controls around market abuse” are in place and we believe that this extends to transaction reporting. These controls are clearly detailed in Article 15 of RTS 22 and if you are not regularly performing quality assurance testing and reconciliation of FCA data against your source system records, you are not meeting these requirements.

  • WATCH: Kaizen CEO Dario Crispini talks to Matt Smith, CEO of Steel Eye

    WATCH: Kaizen CEO Dario Crispini talks to Matt Smith, CEO of Steel Eye

    Our CEO Dario Crispini recently (virtually) caught up with Matt Smith, CEO of Steel Eye, to compare notes on life in lockdown, the impact of the pandemic on global reporting obligations and how investment firms can best manage their reporting in the current circumstances.

    This video covers the following topical issues: 

    • As two CEOs of RegTech companies, how have you coped in these challenging times?
    • What does the regulatory landscape look like and how does the lockdown impact firms’ ability to manage their reporting?
    • What reporting requirements are financial firms subject to and what should firms be doing out for?
    • How important is data management for accurate reporting?
    • What are the big regulatory reporting regimes coming into effect over the next 12 months?
    • What are some of the wider compliance changes and trends?
    • How can you help firms comply smarter, especially during these times?
    • What should firms be looking out for as they return to business as usual?
    • Can regulation add value or is compliance only a cost centre?

    For a virtual discussion of your own with Dario or one of our regulatory reporting specialists, please contact us.

  • Media release: Kaizen Reporting wins Best Transaction Reporting Solution at RegTech Insight Awards

    Media release: Kaizen Reporting wins Best Transaction Reporting Solution at RegTech Insight Awards

    FOR IMMEDIATE RELEASE

    London, 20 May 2020 – Leading regulatory reporting firm Kaizen Reporting (Kaizen), developer of the multi-award-winning assurance service, ReportShield™, has won ‘Best Transaction Reporting Solution (for MiFID II/ MiFIR/ EMIR)’ at the RegTech Insight Awards 2020. Hosted and run by the A-Team Group, the awards are voted for by industry members and celebrate providers of leading RegTech solutions, services and consultancies.

    This year’s awards are designed to recognise both new and established providers that are creatively finding solutions to help with regulatory challenges and span a wide range of regulatory requirements.

    Universal testing approach

    Kaizen’s ReportShield™ is a suite of services which help financial firms meet their reporting obligations and effectively manage their reporting risks. The service for reporting regimes including MiFID II, EMIR, Dodd-Frank, SFTR and other G20 regulations, includes Kaizen’s award-winning accuracy testing, which utilises a universal testing approach to fully assess the quality of the data firms report to the regulator.

    “We are delighted that our cross-platform readership of over 20,000 senior technology officers and data specialists clearly rated Kaizen Reporting as the Best Transaction Reporting Solution (for MiFID II/MiFIR/EMIR) in a very competitive field. We congratulate them on their prestigious RegTech Insight Award win,” said Angela Wilbraham, CEO of A-Team Group.  

    Accurate data more important than ever

    Dario Crispini, CEO of Kaizen (pictured), commented: “What is special about winning this award is that it is voted for by our clients and industry members. In these very challenging times it’s essential that firms, including ours, are able to service their customers to the best of their ability so we are honoured to be selected as the company offering the ‘Best Transaction Reporting Solution’ by RegTech Insight readers and the RegTech Summit Advisory Board.”

    Dario continues, “With the recent high volumes in trading activity it is as important as ever, if not more so, that regulators receive accurate data that allows them to monitor the markets for financial stability as well as market abuse. We would like to thank RegTech Insight and everyone who voted for us for their support.”

    (ends)

    For more information, please contact James Dunseath, on +44 (0) 203 912 3271 or media@kaizenreporting.com

  • EMIR, MiFIR, SFTR Reporting Core Training – new course dates announced

    EMIR, MiFIR, SFTR Reporting Core Training – new course dates announced

    We’re pleased to announce new dates for our CPD-accredited EMIR, SFTR and MiFID/MiFIR Reporting Core Training Courses which we are delivering remotely. 

    Developed and delivered by our regulatory specialists David Nowell (EMIR and MiFIR) and Jonathan Lee (SFTR), these popular half-day courses are also at a significantly discounted price for a limited time only!

    Click on the links below for more details and to book your place.

    Training is an integral part of the systems and controls that firms need to have in place around reporting. Despite the coronavirus pandemic, regulators have made it clear that they are monitoring the quality of regulatory reports closely. 

    If you have any questions about our training courses or for enquiries about bespoke options, please email our Training Team. 

  • LISTEN: Kaizen CEO Dario Crispini on The Regis-TR RoundUp podcast

    Tune in to Dario Crispini on Episode 4 of The Regis-TR RoundUp!

    Dario covers off his early days at the UK regulator, the FSA (now FCA) and the launch of MiFID reporting. He also discusses whether the EMIR Refit can really make EMIR an effective early warning system for global financial crises, and how to prepare for the delayed SFTR roll-out and the problems it could cause for both market participants and regulators.

    The podcast also highlights the incredible efforts of Kaizen’s James Deehan in rowing 3,000 miles across the Atlantic to raise money for the Teenage Cancer Trust.

    Click on the green arrow below to listen!


  • Do not adjust your (transaction reporting) clock

    Do not adjust your (transaction reporting) clock

    This weekend, the UK clocks spring forward to British Summer Time. While you may need to adjust the clocks and watches at home, please remember that the time fields for MiFIR trade and transaction reporting and EMIR trade reporting should be populated in Coordinated Universal Time (UTC). Firms were required to report in UK local time under MiFID I but this is no longer the case for MiFIR transaction reporting.

    The regulators are not likely to have any sympathy if you make errors following these time transitions as they have warned firms of such mistakes in Market Watch 59:

    “The time when the transaction was executed should be reported in Coordinated Universal Time (UTC). We continue to see errors in transaction reports when UK clocks transition to and from British Summer Time, as well as errors driven by inaccurate clock synchronisation. Firms should have arrangements in place to ensure consistent and accurate reporting of trading date and time.”

    How Kaizen can help

    As part of our ReportShield™ quality assurance services, we can run a number of tests to detect instances where the wrong time has been populated. Our accuracy testing service can test all fields in all reports submitted over a given period to give you confidence that your reporting is complete and accurate. For more details or a discussion with one of our regulatory experts, please contact us. 

    Pub quiz trivia

    It may appear strange that the official abbreviation for Coordinated Universal Time is ‘UTC’ rather than ‘CUT’. This abbreviation arose from a desire to use the same abbreviation in all languages. Whilst the abbreviation ‘CUT’ makes sense for English speakers, French speakers advocated ‘TUC’ for ‘temps universel coordineé’. In the end, they agreed to compromise on ‘UTC’, which doesn’t make sense in either language…

    Why not join in the conversation in our Kaizen community on LinkedIn?

  • WATCH: Ian Rennie on how Kaizen helps investment firms achieve complete and accurate regulatory reporting

    WATCH: Ian Rennie on how Kaizen helps investment firms achieve complete and accurate regulatory reporting

    In this video, Kaizen’s Managing Director Ian Rennie answers the below questions:

    • What are the main issues investment firms face when it comes to trade and transaction reporting?
    • How does Kaizen solve the problem of incorrect reporting?
    • What enables Kaizen to solve the problem in a way that others can’t?

    If you need help with your regulatory reporting data quality for MiFID II, EMIR, DFA, SFTR, HKMA or any other G20 reporting regime, please get in touch.

  • Post-Brexit regulatory reporting wish list: MiFIR transaction reporting

    Post-Brexit regulatory reporting wish list: MiFIR transaction reporting

    Wouldn’t you know it; you spend over three years planning and worrying about a hard Brexit, and in the end, right at the last moment, after all the sleepless nights, it doesn’t actually happen! Instead, we now have a nice 11-month transition period. While there may be no changes to the MiFIR, EMIR and, SFTR reporting regimes until 2021, now is a good time to think about what changes you would like to see in the UK reporting regimes at the end of the transition period. While it was assumed that there might be little change in an attempt to assure equivalence, the UK Chancellor’s assertion that he is seeking “outcomes based” equivalence rather than complete alignment appears to have left the door ajar for some sensible changes to the reporting regimes. Starting with MiFIR, here are my top ten suggestions for changes to the transaction reporting regime which we believe will make reporting more proportionate for firms without degrading regulator’s ability to use the data for the intended purposes:

    1. “Country of Branch ” fields

    Perhaps one of the forgotten drivers behind MiFIR transaction reporting is the monitoring of conduct of business. There are five MiFIR “country of branch” fields which the NCAs use to share data amongst each other to help ensure that they can monitor branch activities. At Kaizen, we have discovered that firms frequently have issues populating these fields correctly. Since there will be no systematic sharing of data between the UK and the EEA, there appears to be no regulatory requirement to persist these fields.

    1. “ToTV Opinion Paper”

    ESMA has used this paper to expand the reportable instrument set to include “OTC derivatives sharing the same reference data details as the derivatives traded on a trading venue” Understanding the reportable instrument set has caused firms enough problems without adding to the burden. This is a considerable addition involving the matching of attributes against the ANNA DSB to find potential ISINs and then comparing the attributes associated with these ISINs against FIRDS to see if the instruments are reportable. I do not believe this is proportionate and it can be argued that it is not consistent with the Level 1 regulation. It has to go.

    1. Basket and Index Derivatives

    Firms executing transactions in OTC basket derivatives have to populate the underlying ISIN field with all the ISINs that are traded on an EEA trading venue. For example, if they trade a pharmaceutical basket comprising 421 stocks of which 352 are ToTV, they first need to discover which are ToTV and then populate all of them in the underlying ISIN field. If they make a mistake with any of those ISINs, it will be rejected by the regulator. This is very onerous for firms and can be of very little value to the regulators. There is no information on the weighting, so the information cannot possibly be used by the regulators on a systematic basis.

    Additionally, any changes in the basket composition are not reportable. It is also questionable whether the reporting of an index is of any real value to the regulators as it is doubtful whether they hold the constituent and weighting data. Of course, it is possible to manipulate the index markets (see Flaming Ferraris) but this is likely to stand out like a sore thumb to the participants and should be reported through a STOR. It is very difficult for firms to know whether the OTC index derivatives are reportable as it only takes one of the index constituents to be ToTV and this information is difficult to source – it certainly isn’t on FIRDS.

    1. IPOs

    Under MiFID, we used to say that everything that was knowable about an IPO was contained in the prospectus, so it would not be proportionate to require the resultant transactions to be reported. I’m not sure what’s changed to justify their inclusion for MiFIR. The task has been made more difficult as it is possible that some of the ‘counterparties’ don’t have LEIs as they are not necessarily normal market counterparties. Of course, trades cannot be reported if the counterparty doesn’t have an LEI. To make things worse, reporting firms have often discovered that the ISIN of the IPO is not on FIRDS at the time of the IPO. As some trading venues have not reported dates when an application for trading was made, some IPO trades have been continually rejected.

    1. Trading Capacity

    In the UK, we understand ‘principal’ and ‘agency’; but we don’t always understand the distinction between the new MiFIR values of ‘dealing on own account’ and ‘matched principal’. However, many firms, particularly the buy-side, have discovered that brokers confirming transactions back to them as ‘matched principal’, causes immense difficulties. Additionally, you can describe the same back-to-back principal scenario to a number of firms and I believe 70% of them will report it as two ‘DEAL’ transactions and 30% will report it as a single “MTCH” transaction. If it doesn’t matter which method is observed, why have the element of grey in the first place? Let’s get back to trading capacity we understand (and that are used in other reporting regimes).

    1. Crazy Chains – transmission of order, INTC and individual funds

    I love the Guidelines document, I really do. However, there are times when I’m reading sections 5.26 (Chains and Transmission) and 5.27 (Investment firm acting under a discretionary mandate for multiple clients) that I find it extremely difficult to carry on reading. There are a couple of inconsistencies within these Guidelines which suggests they may not work quite as the regulators envisage. It is just too convoluted and transaction reporting shouldn’t be this difficult. Again, I think it is the buy-side that may suffer most from this and maybe it is an area where the FCA may want to simplify the requirements. For example, are allocations to funds really required when the fund manager reports with the identifier of the individual decision maker within the fund management company? Does the transmission of order indicator actually add any value for the regulator?

    1. Repos & Securities financing indicator

    Exactly what is the logic for requiring a securities financing transaction, such as a repo, to be reportable under MiFIR simply because it has been excluded under SFTR? How was that leap made? If RTS 22, Article 2 sets the precedent that SFTs aren’t reportable under MiFIR (because they cannot be deemed to be abusive) why was it felt necessary to add the proviso that they should be reported if the counterparty is a member of the European System of Central Banks. Simplify the regulation and remove SFTs from MiFIR transaction reporting completely.   

    1. Swaps

    Completing the technical standards and Guidelines was clearly a mammoth task for ESMA and it is inevitable that there would be time constraints. I believe this is particularly evident when it comes to the reporting of swaps. For example, it is questionable whether requiring the price of an equity swap to reflect the interest rate is sensible, as the price of the underlying reference security would appear far more valuable to the regulators in pursuing market abuse. In fact, why require the interest rate side at all – it is not required for CFDs or spread bets, which are essentially swaps anyway. As for the “swap-in” and “swap-out” indicator – does this really bring any value when rules for determining the ‘buyer’ and ‘seller’ are already set out in the regulatory text?

    1. Reference Data Requirements

    Where a reported instrument is not ToTV and is only being reported because the underlying instrument is ToTV, up to 15 additional reference data fields need to be populated to describe the instrument to the regulator. This has proved to be particularly difficult for firms. A lot of these fields are essential for the regulator to detect market abuse – the underlying instrument ISIN is a prime example. However, it is questionable whether some of the others deliver any value. For example, does the ‘instrument full name’ add value when all the details are contained in other fields. Are some of the fields duplicated in the CFI code (e.g. ‘option type’). Does ‘notional currency’ have any relevance for non-FX derivatives?

    1. Short Sell indicator

    This is very onerous for firms to populate correctly and maybe the cost benefit analysis of this field should be reviewed. If there is a permissible value for ‘information not available’ (for clients after acting on a ‘best efforts’ basis) then you have to assume that the overall quality of this information is questionable.


    These are my ‘just for fun’ top ten as there may be perfectly valid reasons why the regulators need this information. To be honest, they’re my initial thoughts and I haven’t even mentioned other contenders such as ‘net amount’, ‘waiver indicator’ and ‘OTC post trade indicator’.

    However, there is a serious element here. If there is an opportunity for the UK FCA to tweak its reporting regimes on the basis of ‘outcomes-based equivalence’ rather than alignment, the process needs to start immediately and firms need to feed into that process. Eleven months is not a long time.

    Forthcoming blogs will detail our wish lists for the EMIR trade reporting and SFTR regimes.

    For help with your transaction reporting accuracy or to discuss your own post-Brexit transaction reporting wish list with one of our regulatory specialists, please contact us.

  • FIRDS: Are trading venues contributing to poor quality transaction reporting?

    FIRDS: Are trading venues contributing to poor quality transaction reporting?

    Perhaps the biggest irony about MiFIR transaction reporting is that reports submitted by investment firms need to be complete and accurate, but ESMA states it cannot provide any guarantee that one of the key tools firms need to do this, the ESMA FIRDS reference database, is “complete, accurate or up-to-date”. This is particularly harsh on firms as they can report with the correct ISIN to identify the financial instrument, but if that ISIN (or underlying ISIN) is not on the FIRDS database within seven calendar days, then the report will be rejected by the competent authority. The onus is then on the firm to investigate whether they should re-submit the report.

    This is unfair on firms as most of them are trying to do the right thing by only reporting transactions in instruments that are reportable, but they are frustrated with limitations of ESMA’s FIRDS database. It would be easy to blame ESMA for this, but I believe that also is unfair. The quality of FIRDS can only ever be as good as the information submitted to it and it is the EEA trading venues that are obliged to submit this data through the requirements detailed in RTS 23. The quality of FIRDS data has improved dramatically since go-live, as you would expect over the course of two years, and many trading venues may be reporting perfectly. However, other trading venues are not, and deficiencies in this reference data was highlighted in Germany’s Ministry of Finance’s position paper on MiFID and MiFIR.

    Germany’s Ministry of Finance concludes that “ further analysis is needed on the question of how to ensure the provision of accurate, reliable and timely reference data. The analysis should also explore ways to make FIRDS the golden source for reference data.” Well I’m sure we all know the obvious answer to this one – there is nothing quite like a sanction, perhaps in the form of a fine and public censure, to ensure data quality is taken more seriously. We have seen sanctions used for firms’ poor transaction reporting and how this can focus attention, so maybe trading venues need to be wary of the possibility of sanctions if they don’t improve the quality of their reference data. If you are a trading venue that has doubts about the quality of its reference data, now might be a good time to look at quality assurance solutions.

    The quality of FIRDS data also impacts the thorny issue of the ESMA opinion paper on OTC derivatives traded on a trading venue. In this paper, ESMA expands the reportable instrument set to include “OTC derivatives sharing the same reference data details as the derivatives traded on a trading venue”. This paper has caused much consternation in the industry. Whilst some firms have paid as much attention to the opinion paper as a London cyclist does to a red light, many other firms are desperately trying to do the right thing in trying to match the reference data attributes of their OTC derivatives against the attributes of derivatives on the FIRDS database to see if they are reportable. The quality of the FIRDS data, and the flexibility of FIRDS itself, often makes this a frustrating and imprecise task. This appears particularly true for FX and interest rate derivatives and prompts the question (also asked by Germany’s Ministry of Finance) of whether the concept of ‘traded on a trading venue’ should be applied to OTC derivatives. Anybody who thinks it should, needs to try assessing whether some OTC FX swaps are reportable or not. They would probably find that they first need to match attributes against the ANNA Derivatives Service Bureau to find potential ISINs and then compare the attributes associated with these ISINs against FIRDS to see if the instruments are reportable (not forgetting to check if the underlying forwards have reportable ISINs). They may well struggle with the flexibility of FIRDS in this task and may possibly be perplexed by the quality of much of the data – for example, the lack of consistency between the financial instrument long name and the attributes, particularly the expiry date. 

    Whilst the MiFIR definition of reportable instruments appears easy on paper (MiFIR Article 26(2)), there is plenty of devil in the detail and many firms struggle to fully understand them. These firms are unlikely to understand the implications of the ESMA ToTV opinion paper and it does appear to be too complex a requirement for the associated regulatory benefit. The current data quality and flexibility of FIRDS does not seem fully adequate to support this requirement. More importantly, it appears that the quality of FIRDS reference data may be causing issues with the overall quality of transaction reporting. Whilst many trading venues are on top of the task of their RTS 23 reporting, it appears that some trading venues need to up their game to avoid regulatory attention.

    If you’re worried about the quality of your reported data, this is why we here at Kaizen exist. Our accuracy testing and reference data testing services check all data fields in every trade or transaction report submitted to the regulator so you have a full picture of the quality of your reporting.  Contact us for a discussion on how we can help. Join in the conversation over on our LinkedIn.

  • Video: Dario Crispini’s regulatory reporting predictions for 2020

    Video: Dario Crispini’s regulatory reporting predictions for 2020

    • Will data quality continue to be the theme for regulatory reporting in 2020? 
    • What are the big regulatory reporting regimes coming up?
    • What issues should firms be looking out for?
    • Will we see penalties for MiFID or EMIR reporting?
    • What are the key challenges for the RegTech industry in 2020?
    • And what on earth is ‘BRiFID’?

    The answers to these questions and more in this and more in the above video from our CEO Dario Crispini.

    With thanks to the Wealth Mosaic for collaborating with us on this video. 

  • Video: David Nowell on MiFID II reporting

    Video: David Nowell on MiFID II reporting

    Kaizen’s Senior Regulatory Reporting Specialist David Nowell provides us with his view on:

    • What the regulators will be expecting now on MiFID II reporting
    • How investment firms can ensure reporting accuracy

    Read David’s blog MiFID II 2nd anniversary – ready for the terrible twos?

    Thank you to the Wealth Mosaic. 

  • One year to go:  RTS 2 non-equities reporting to reduce to five minutes

    One year to go: RTS 2 non-equities reporting to reduce to five minutes

    The countdown has now started! From this month it is now less than a year to go until investment firms’ RTS 2 non-equities post-trade transparency reporting needs to reduce from 15 minutes to five minutes. This new implementation comes in three years after the original MiFID II go-live.

    RTS 2, Article 7 states: “…for the first three years of application of Regulation No 600/2014, within 15 minutes after the execution of the relevant transaction; thereafter, within 5 minutes after the execution of the relevant transaction.”

    Whereas RTS 1 transparency has been relatively straightforward due to the electronic nature of equities trading (hence the one minute limit), the non-automated nature of voice trading, as an example, still causes problems for firms in terms of meeting the current close-to-real-time 15-minute deadline imposed by the regulation. It is commonly recognised that firms still struggle to meet publication after 15 minutes, whether that’s changing a trader’s habit, automating trading or even introducing FIX messaging protocol which  – believe it or not  – still isn’t used by all firms. So the reduction to five minutes may really impact firms and may alert the national competent authorities to focus more on these transparency deadlines.

    MiFID II’s transparency objective meant that it was bringing the non-equities trading world into the 21st century and electronifying the practice, creating a level playing field and enabling investors to make an informed decision with the knowledge of how the price was formed.

    With under a year to go, firms need to incorporate this change into their book of work technologically, procedurally and in some cases, culturally. At Kaizen, we provide accuracy testing on MiFID II post-trade transparency reporting (PTT) data to check that you are meeting these close-to-real-time requirements and that your data is correct. This includes checking whether you are reporting within the required timescales and alerting firms where they consistently do not meet the deadline after execution. 

    Contact us if you’d like some help in ensuring your PTT reporting is accurate as this will help with your preparation for the change to reporting within five minutes. 


  • Kaizen Reporting in the news 2019

    Kaizen Reporting in the news 2019

    20 December 2019: Dario Crispini spoke to Drew Nicol at Securities Lending Times – UK’s FCA predicted to ramp-up non-compliance fines in 2020

    18 December 2019: Dario Crispini spoke to Luke Jeffs at FOW – FCA to “dramatically increase” scrutiny in 2020 – expert

    28 November 2019: David Nowell spoke to Alice Tchernookova at Practice Insight (IFLR) – MiFID II’s review path ahead.

    28 November 2019: David Nowell spoke to Hugo Bromley at Practice Insight (IFLR) – Away from equities: MiFID II, Priips struggle in fixed income, derivatives

    23 October 2019: Ian Rennie spoke to Alice Tchernookova at Practice Insight (IFLR) – FCA: Buyside ‘miles behind’ on SMCR journey.

    22 October 2019: Jonathan Lee spoke to Lynn Strongin Dodds at Best Execution – The long and winding road of SFTR.

    12 September 2019: David Nowell spoke to Thomas Helm at Practice Insight (IFLR) – Special report: Transparency makes markets safer but more complex.

    4 September 2019: David Nowell spoke to James Thursfield at FOW – German consultation positions FIRDS as potential golden source.

    25 July 2019: David Nowell spoke to Alice Tchernookova at Practice Insight (IFLR) – Industry bemoans ‘excessive’ rules.

    11 July 2019: David Nowell spoke to Alice Tchernookova at Practice insight (IFLR) – Emir refit: frustration hits the industry as new rules come in.

    11 July 2019: David Nowell spoke to Gill Wadsworth at Best Execution – The Long Goodbye.

    5 July 2019: David Nowell spoke to Rachel Wolcott at Thomson Reuters – ESMA says 40% of EMIR trade reports match; sceptical reporting specialists say rate likely much lower.

    1 July 2019: David Nowell spoke to Fraser Tennant at Financier Worldwide – Transaction reporting: the importance of getting it right.

    12 June 2019: Chris Machin spoke to Louisa Chender at FOW – Consolidated tape post-Brexit could create competition, costs.

    5 June 2019: David Nowell spoke to Justin Pugsley at Global Risk Regulator – Consequences of MiFID still unfolding ahead of pending review.

    30 May 2019: David Nowell spoke to Louisa Chender at FOW – Essential Mifid II tool not yet accurate.

    14 May 2019: David Nowell spoke to David Braid at Practice Insight – Goldman/UBS fines sharpen Mifid reporting compliance.

    7 May 2019: David Nowell spoke to Thomas Helm at Practice Insight – Buyside at risk of Emir reporting fines.

    5 May 2019: Dario Crispini spoke to Nickolas Pratt at Funds Europe – Asset servicing: Avoid a transaction reporting fine.

    28 March 2019: Dario Crispini spoke to Louisa Chender at FOW – Goldman Sachs fined £34.3 million for reporting failures.

    19 March 2019: David Nowell spoke to Hayley MCdowell at The Trade – UBS fined £27.6 million for MiFID reporting failures.

    19 March 2019: Ian Rennie spoke to Louisa Chender at FOW – UBS slapped with £27.6 million fine for reporting flaws.

    14 March 2019: David Nowell spoke to Thomas Helm at Practice Insight – Mifid II: UK firms start receiving FCA letters.

    8 February 2019: Jonathan Lee spoke to Rebekah Tunstead at Bob’s Guide – Banks pressurize trading venues for SFTR filing clarity.

    1 February 2019: Dario Crispini spoke to Rachel Wolcott at Thomson Reuters – Workload to prepare transaction reporting for Brexit is equivalent to MiFID II go live.

    29 January 2019: Jonathan Lee spoke to Sharon Kimathi at Practice Insight – SFTR: banks anxious about delegated reporting.

    14 January 2019: David Nowell contributed an article for Global Risk Regulatory – Issues remain one year on from MiFIR transaction reporting going live.

    11 January 2019: Jonathan Lee spoke to Olly Jackson at International Financial Law Review – SFTR: market sill needs critical data.

    3 January 2019: David Nowell spoke to Louisa Chender at FOW – Mifid II reporting issues linger one year on.

  • You better watch out, you better not cry….

    You better watch out, you better not cry….

    The worst Christmas present I ever received was a jar of mustard. To be fair, it was a large jar and it did come from Fortnum and Mason, but it was still a jar of mustard. And I don’t like mustard. What on earth was going through their minds when they thought this dodgy coloured and foul tasting condiment would be a suitable festive gift?

    Secret Santa?

    However, there are worse Christmas presents, especially if your Secret Santa this year was the FCA and you received a letter asking you to explain numerous errors in your MiFID II transaction reports. Many firms fail to appreciate that the FCA Santa really does know if you’ve been naughty or nice with your transaction reporting. It has systems designed to find errors in transaction reports and you will not be alone if you have received a letter from the FCA (as 223 UK investment firms have so far been contacted to explain reporting errors).

    Don’t panic

    Communications from the FCA can often cause alarm within firms, but they shouldn’t necessarily induce panic. The MiFID II transaction reporting requirements are extremely complex and we have discovered errors through the quality assurance testing we have performed for every firm. No NCA can sanction every firm when they find errors in their transaction report and nor do I think they would want to. However, they cannot perform their role of monitoring for market abuse unless they receive complete and accurate transaction reports. The UK FCA has now twice signaled in Market Watch newsletters that firms are making unacceptable errors in their transaction reports and its patience must be wearing thin. It is quite possible that they may be thinking of imposing further sanctions for transaction reporting breaches and, who knows, maybe there’s one going through the enforcement process as we speak.

    Put the right controls in place

    If you receive a less than cheery Christmas missive from the FCA, it is an opportune moment to consider whether you have adequate controls over your transaction reporting processes. We believe the FCA is far more likely to take a collaborative approach with firms if they can see that the firm is trying to do the ‘right thing’ – i.e. implementing the controls detailed in Article 15 of RTS 22. In particular, performing quality assurance testing and regular reconciliations of data within source systems with the reports sent to the FCA. If these controls are not in place, you’re far more likely to find yourself on Santa’s naughty step.

    If you don’t know if your reporting’s bad or good, please speak to us at Kaizen. We have a full suite of quality assurance and reconciliation solutions that can ensure that you are good for goodness sake…

  • Video series: Dario Crispini on Kaizen’s key regulatory reporting services

    Video series: Dario Crispini on Kaizen’s key regulatory reporting services

    Kaizen Reporting’s CEO Dario Crispini talks about the regtech company’s multi-award winning regulatory reporting assurance services and the unique testing methodology behind them. 

    This is a four part introduction to Kaizen Reporting video series from CEO Dario Crispini.

    Watch the first video in the series – Why was Kaizen founded?

    Watch the third video in the series – Issues and risks of poor data quality in regulatory reporting.

    If you’re concerned about the data quality of your regulatory reporting, get in touch. 

    Huge thanks to the Wealth Mosaic whom we collaborated with on this project. 

  • No market abuse sanctions by FCA in 2018

    No market abuse sanctions by FCA in 2018

    ESMA has published its peer review on how national competent authorities handle suspicious transactions and orders reports (STORs) under the Market Abuse Regulation. It is fully compliant in four of the ESMA metrics and broadly compliant in the other two.  So congratulations FCA – pretty much top of the league in this review.

    However, what is interesting is that despite this near-perfect report card, the FCA has not imposed any measures and sanctions on firms.  Surely the true measurement has to be the number of successful market abuse cases the regulator has brought? The ESMA report has a handy table showing the number of measures and sanctions imposed for market abuse infringements and the UK figures for 2018 show no sanctions.

    Without wanting to appear like the Christmas Grinch, in our view this is a very disappointing figure. Bearing in mind that 2018 marked the introduction of a dramatically more complex transaction reporting regime which offers regulators a far richer data set to monitor market abuse more effectively, this failure to sanction would indicate to us that something isn’t right.

    Whilst many firms are making great efforts to report STORs and to submit transaction reports, the FCA can only do its job effectively if those transaction reports are complete and accurate. If you are not completely confident that your transaction reports meet this requirement, talk to us about our ReportShield™ data quality, reconciliation and training services.

    What do you think about this peer review from ESMA? Join in the conversation over on our LinkedIn.

  • Video series: Dario Crispini on why he set up Kaizen Reporting

    Video series: Dario Crispini on why he set up Kaizen Reporting

    Kaizen Reporting’s CEO Dario Crispini talks about the factors that led him to start the company, our services, and the benefits we bring to our clients, in the first video of a series introducing who we are and what we do.


    This is a four part introduction to Kaizen Reporting video series from CEO Dario Crispini.

    Watch the second video in the series – Kaizen’s key regulatory reporting services.

    Watch the third video in the series – Issues and risks of poor data quality in regulatory reporting.

    If you’re concerned about the data quality of your regulatory reporting, get in touch. 

    Huge thanks to the Wealth Mosaic whom we collaborated with on this project. 

  • Kaizen Reporting wins ‘Best New Product: Regulatory Reporting’ at the FOW International Awards

    Kaizen Reporting wins ‘Best New Product: Regulatory Reporting’ at the FOW International Awards

    FOR IMMEDIATE RELEASE

    11 December 2019, London: Leading regulatory reporting firm Kaizen Reporting (Kaizen), developer of the multi-award-winning assurance service, ReportShield™, was last night named the winner of the ‘Best New Product: Regulatory Reporting’ at the FOW International Awards.

    The FOW International Awards were judged by a panel of industry experts and recognized companies that have launched new products or made significant enhancements to existing products during the judging period.

    Since the start of the year Kaizen Reporting has introduced a number of enhancements to its ReportShield™ service.  These include: 

    • Updated its EMIR testing for the EMIR Refit/EMIR 2.0 which has a particular focus on Exchange-Traded Derivatives (ETDs)
    • Expanded the jurisdictions it covers – HKMA (Hong Kong), MAS (Singapore), FinfraG and the upcoming Securities Financing Transaction Regulation (SFTR).
    • Added an additional 400 new independent tests to its MiFIR accuracy testing service – further deepening the quality of its already unparalled testing coverage
    • Expanded its MiFIR testing suite to include RTS 23 (testing instrument data for trading venues and systematic internalisers) and Post-Trade Transparency Reporting (RTS 1 and 2)
    • Added regulatory reporting core training for EMIR, MiFIR and SFTR as a fifth component of the service.

    Dario Crispini, CEO of Kaizen Reporting, commented: “We are delighted to have been awarded the ‘Best New Product: Regulatory Reporting’ at this year’s FOW International Awards and to have received our second award from them is as many years. Regulatory reporting is an important component to the derivatives industry and addresses the challenges across compliance and regulatory risk management as regulators continue to focus on financial stability.”

    Kaizen’s ReportShield™ is a set of services that act as a shield against reporting issues, helping investment firms to meet their reporting obligations and effectively manage their reporting risks. The service includes a number of controls required for complete and accurate trade and transaction reporting including Kaizen’s flagship accuracy testing, advanced regulatory reconciliation service and testing of reference data.

    (ends)

    For media inquiries, please contact Fiona Wilde on media@kaizenreporting.com or +44 (0) 20 3912 3271.

  • The scariest regulatory reporting changes facing you this Halloween

    The scariest regulatory reporting changes facing you this Halloween

    It’s Halloween! And what better time to cover off some of the scariest regulatory reporting changes that you need to keep very very close to, following the full-moon…

    Quoting Macbeth’s three witches, “By the pricking of my thumbs, something wicked this way comes”, here are three key regulations affecting everyone in the coming months:

    In Thunder comes Brexit

    31 October was always going to be a horror Halloween show but the EU have prolonged the agony for another three months to 31 January. The good news is that most firms have prepared for the October exit but do keep an eye on any unknown regulatory changes in the coming months – or read our Brexit White Paper to help with your preparations.  

    In Lightning comes SMCR

    Ghosting quietly in, don’t forget if you’re an Core or Enhanced Firm, as categorised by the FCA, your CF Approved Persons change to SMFs under the Senior Managers and Certification Regime (SMCR) on 9 December. Encouraging a culture of taking responsibility for actions and demonstrating a clear understanding of where that responsibility lies, are the key messages. You can’t use a magic wand to sign-off on the accuracy of your regulatory reporting, a key task for your SMFs.

    In Rain comes SFTR

    As we speak on the day of the devil, SFTR is only 166 days away.  This is frighteningly close.  Are you prepared and testing in UAT for this new reporting regime coming into effect on 14 April 2020? Contacting our very own SFTR expert Jonathan Lee is much less scary than a letter from the regulator.

    When the hurly-burly’s done, when the battle’s lost and won, Kaizen is here to help with the most scary of regulatory reporting challenges. Please contact us if you’re worried about any of the above and we can turn your regulatory reporting obligations from a trick to a treat!

    Author: Chris Machinbeth

  • Join us at Infoline’s Trade and Transaction Reporting Conference in Stockholm

    Join us at Infoline’s Trade and Transaction Reporting Conference in Stockholm

    We are delighted to be able to offer 30% off tickets. Use code FKM63769KAIZEN.

    Register


    Calling all investment firms, securities firms, banks and trading venues impacted by the reporting and disclosure obligations of SFTR, MiFIR and EMIR! Please join us at this one day conference in Stockholm. Don’t miss our Senior Regulatory Reporting Specialist, Jonathan Lee, discussing SFTR Reporting best practice and how to prepare for the April 2020 go-live at 10:30am. Followed by Senior Regulatory Reporting Specialist, David Nowell, on a panel to discuss the ongoing challenges with MiFID II Transaction Reporting and EMIR Trade Reporting. 

  • Why communication and cooperation are the key to avoiding regulatory reporting fines

    Why communication and cooperation are the key to avoiding regulatory reporting fines

    Recently we saw a large inter-dealer broker fined by the FCA for ‘improper trading’. The final notice stated that the firm was “failing to conduct its business with due skill, care and diligence, failing to have adequate risk management systems and for failing to be open and cooperative with the FCA”.

    This led me to think that the same message can be used across all regulations and that this was the same communication we heard from the FCA when it handed out the two MiFID I fines earlier this year. Introducing care and diligence with added controls, governance and independent quality assurance testing is one thing; it’s then communication and cooperation with the regulator that are key.

    Be proactive, transparent and open with your NCA

    Being on the front foot with the regulator should not be deemed a negative or onerous task. It is incredibly important that all firms that have found an issue with their reporting, relay this message to their National Competent Authority (NCA) as soon as they can, through the applicable channels. The key message we see and hear from NCAs is that they always encourage firms to be proactive, transparent and open.

    Once an issue has been identified either internally or externally via a quality assurance testing service, analysis has to be completed and the relevant action decided upon.

    Alert your NCA as soon as possible

    Depending on the regulatory regime, the NCA may require a form to be completed. In the UK, for MiFIR transaction reporting an errors and omissions form* needs to be emailed to the Markets Reporting Team.  For EMIR, a breach notification form* needs to be completed.

    The likelihood is that the sooner the issues are identified and then communicated, the happier the relevant NCA will be that you are being proactive and cooperative to improve the quality of your reporting.

    At Kaizen, as well as helping firms check the accuracy of their regulatory reporting, we have former regulators as part of our team of subject matter experts. Not only does their expertise feed into our testing services, our clients also benefit from our advice through the process of communication and cooperation with your NCA.

    We’ve helped a number of firms provide confidence to the regulator through identification of issues in reporting quality but also through putting the right controls in place. Contact us if you’d like to discuss any of the issues raised in this blog.

    *Does not open in new window.

  • ESMA clarifies FX forwards transaction reporting in new MiFIR Q&A

    ESMA clarifies FX forwards transaction reporting in new MiFIR Q&A

    ESMA has provided a very useful example of how to report FX forwards in its latest Q&A on MiFIR data reporting. In particular, we would urge firms to take note on the practice of populating the ‘quantity’ and ‘price’ fields:

    • The ‘quantity’ (and ‘quantity currency’) should reflect the amount of the FX forwards in the base currency
    • The ‘price’ (and ‘price currency) should show the forward rate expressed as a price of base currency in the quoted The monetary value XML tag should be used (if reporting to an ARM in flat file, ‘price type’ is monetary value.

    The only additional changes appear to be in the table of national identifier formats. This details a change in the format of Portuguese passports issued after April 2018 and corrections to the Romanian National Identification Number and national passport formats.

    Whilst the new MiFIR Q&A signals only relatively minor changes, it clearly demonstrates the need for firms to remain on top of regulatory developments. Our regulatory reporting training courses help firms stay abreast of the reporting requirements and help identify any interpretational errors. For further details, please see our training courses.

     
  • ESMA postpones review of MiFID II RTS 2

    ESMA has written to the European Commission to postpone the review of MiFID II Regulatory Technical Standards (RTS) 2, which was due in July 2019, as outlined in Article 17 of the RTS regulatory text.

    The review is key to understanding bond transparency thresholds and liquidity assessments. Given the uncertainties around Brexit, it was felt that the analysis should be completed after the UK has left the European Union. This will now be due by 30 July 2020 and recent regulatory commentary suggests it will begin around March 2020.

    This is another rescheduling to RTS 2, as data quality already delayed the SI regime for bonds until eight months after MiFID II go-live. The SI regime for derivatives is still not due to go live (for the same reason) until ‘at some point in 2020’. This Brexit-related delay to the review will almost certainly push the derivatives SI regime to the latter end of 2020, which in turn may delay the transparency reporting requirement under RTS 2 which looks at decreasing it from 15 minutes to five minutes in January 2021.

    For regulatory reporting purposes, this brings further complexities to investment firms. Understanding of trading where the primary market liquidity is sitting, and its subsequent size and liquidity thresholds for deferral eligibility, is key. Ensuring you are reporting to the correct APA in Europe or UK brings transparency challenges too. 

    To discuss any of the issues above or to find out how our ReportShield™ services could help with your Post Trade Transparency reporting, please get in touch. 

  • In the news: David Nowell and Chris Machin speak to FOW

    In the news: David Nowell and Chris Machin speak to FOW

    Our Senior Regulatory Reporting Specialists David Nowell and Chris Machin recently sat down with James Thursfield from FOW to discuss the results of the German Ministry of Finance industry consultation. The article highlights the need for a golden source for reference data and the role of the FIRDS database.

    “The regulators are well aware of deficiencies with the FIRDS reference data and already state that it cannot be relied to be complete, accurate and up-to-date,” Nowell told FOW. 

    “Esma has always, even before go-live, stated that they would not be the Golden Source (even if de-facto they actually are) and no solution has been suggested,” Machin said.

    Read the full interview.

  • In the news: David Nowell speaks to Practice Insight on regulatory change

    In the news: David Nowell speaks to Practice Insight on regulatory change

    Senior Regulatory Reporting Specialist David Nowell spoke to Alice Tchernookova from International Financial Law Review’s publication Practice Insight about the future of regulation now that MiFID II has bedded down within the industry. 

    “We have almost reached a stage where we must ask ourselves whether being fully compliant is actually possible,” said David Nowell.

    Read the full article. 

  • MiFIR transaction reporting goalposts set to shift again

    MiFIR transaction reporting goalposts set to shift again

    Whilst it may be a bit more of a tweak than a wholesale change, firms need to be aware and plan for changes to the ESMA validations that are targeted to come into effect on 23 September this year. 

    The changes were agreed back in July 2018 but delayed by the Brexit postponement and are mainly amendments to cover mistakes in the validation previously introduced. The changes, cut and pasted from the ESMA version history, are as follows:

    • rule id 010: field 3 must not be populated. This also pertains to SIs;
    • rule id 014: add provision for the case when an LEI is in the “Lapsed” status for a certain period;
    • rule id 096: validation of field 28 against the reception timestamp;
    • rule id 117: field 37 not mandatory for SIs;
    • rule id 136: check against additional CFI codes;
    • rule id 154: check against additional CFI codes;
    • rule id 227: correction of a typo in one of the CFI codes.
    • Clarified description of rules 228 and 267.

    For me, the most important of these changes is the change to Rule 117.  From the implementation of this change, firms should no longer populate ‘Country of branch membership’ for trades against systematic internalisers. Of course, this field should never have been populated for trades against systematic internalisers in the first place as this contravenes the Regulatory Technical Standards (“This field shall only be populated for the market side of a transaction executed on a trading venue or on an organised trading platform outside of the Union.”). I think it is important to highlight that this oversight has forced firms to make an error in their transaction reports in order for them to be accepted by the NCAs.

    I don’t wish to criticise the regulators for making errors, as I believe it is inevitable that there will be some initial errors in the implementation of such a complex regulatory reporting regime – for both regulators and firms. However this issue clearly raises the question about whether the NCA would expect every firm to submit a form when they are forced to report incorrectly in order for the NCA to accept the report. There has to be a degree of common sense and this is not reflected in the wording of Market Watch 59.

    It is also fair to say the changes have not been widely publicised. ESMA has made a notification of changes but I’m sure most people, like me, will find this notification extremely difficult to understand. I’m sure people will also be confused by the validation version history that still states that the changes were “applicable from the end of 2018”. Perhaps the FCA is waiting for more confidence in the 23 September implementation date before it makes an announcement. However, whilst these changes aren’t major, firms need time to assess the changes, code and test any required system changes. September 23 already appears very close.

    Kaizen will of course be updating our ReportShield testing to include the latest validation changes in time for September 23. We provide validations as part of our accuracy testing service at no extra charge to clients – saving significant costs in avoiding outsourcing an additional validations service. Please contact us for a discussion with one of our regulatory experts to find out more.

  • WEBINAR: Transaction Reporting – Practical steps to reduce regulatory risk

    Join Kaizen and PIMFA in this free webinar where we will be discussing why the FCA is so unrelenting in its demands for complete and accurate transaction reporting and what essential steps firms need to take to stay on the right side of the regulator.

    Speakers include our very own David Nowell and PIMFA’s Senior Policy Advisor, Kevin Sloane.

    Key areas of focus include:

    • What the regulator expects from firms
    • Importance of quality assurance testing
    • What ‘reconciliation’ actually means
    • How to avoid common pitfalls
    • Latest information from the regulator

    Listen to the recording. 

    If you require more information please email learning@pimfa.co.uk.

  • FCA insight into Transaction Reporting Feedback

    At the Infoline Trade and Transaction Reporting Conference in London this week the audience were on tenterhooks for the latest update from Ana Fernandes, MRT Manager at the FCA. We thought we would share some insight from the statistics and issues she highlighted:

    Statistics

    • There are over 8.7bn records in the FCA’s Market Data Processor (MDP)
    • There are 23 submitting entities
    • Approximate 7,900 executing entities under ESMA, 3,000 of these are UK firms
    • Over 300,000 LEI’s and over 6.7m National Identifiers
    • FCA has received 1,335 notifications of errors from only 394 firms
    • 20 thematic investigations have been completed
    • 130 firms have been contacted by the FCA
    • FCA have only seen 405 requested and downloaded sample Transaction Reports in 2019

    There was a definite concern on the low numbers of submissions and an encouragement for firms to come forward asap and ‘promptly notify’ as per stated in Article 15(2) of the RTS 22.

    Issues seen by the FCA

    • GMT vs BST (a candid reminder to firms that clocks do change twice a year!)
    • Major vs Minor currencies
    • Price Zero vs NOAP
    • Buyer vs Seller
    • Misreporting of National Identifiers
    • Wrong Buy/Sell with Trading Capacity
    • Inconsistent TV TIC by Trading Venue
    • Use of default trading times

    Food for thought especially as mentioned before, by my colleague David Nowell, that these are still the same issues that firms were fined for as seen under MiFID I. These facts and issues evidence that the FCA are actively pursuing policy and detective activities in order to identify data quality issues. These are issues Kaizen testing is designed to highlight to our clients. Get in touch to discuss the accuracy of your trade and transaction reports. 

  • The effects of Brexit on MiFID II post-trade transparency reporting

    The effects of Brexit on MiFID II post-trade transparency reporting

    “There are known knowns. These are things we know that we know. There are known unknowns. That is to say, there are things that we know we don’t know. But there are also unknown unknowns. There are things we don’t know we don’t know.” – Donald Rumsfeld (Feb, 2002).

    Brexit…the ‘known unknown’ of everyone’s lives (at least for those of us in the UK) and not just in financial services but across all sectors of life.

    MiFID II has not escaped Brexit either.  Let’s call it BRiFID!  My colleague David Nowell has covered in detail the effects of Brexit on EMIR trade reporting & MiFIR transaction reporting but in this blog, I want to delve into the effects on post-trade transparency reporting. 

    Kaizen announced at the beginning of December 2018 that we were to offer post-trade transparency reporting testing following on from our established MiFID II transaction reporting testing service. The need and demand for MiFIR completeness and accuracy across regimes has become very relevant, highlighted even further by the recent penalty announcements from the UK regulator, the FCA:

    The FCA’s Final Notice on 19 March for the first of this year’s transaction reporting fines, stated:

    “Firms must take reasonable steps to ensure the accuracy and completeness of the transaction reports that they submit to the Authority. One way that firms can help to achieve this is by having controls in place to reconcile the completeness and accuracy of their transaction reporting process.”

    The most recent fines were admittedly for transaction reporting inaccuracies under MiFID I, and MiFID II sanctions are not yet known or been broadcast. But it is only a matter of time before the next firm is penalised and this could well be for post-trade reporting inaccuracies (known unknowns). Stephen Hanks, Head of Markets Policy at the FCA, mentioned at an conference on 16th April that, “poor data quality is still being sent to APAs and that the FCA will continue to work with investment firms to improve quality as a priority”.

    What Now?

    MiFID II transaction reporting has clearly taken a regulatory priority since go-live but post-trade transparency reporting, its just-as-important sibling, is just as key. The past year’s Level 3 Q&As have brought clarity to previous ambiguous regulatory text so firms should now have a greater understanding of their reporting obligation but do they have the testing and controls in place?

    Stephen Hanks stated; “There are still issues we see in reports and we are particularly disappointed to still be seeing errors in reports which would have been errors under MiFID I, never mind MiFID II.”

    Really! Why? When??

    Yes, in amongst the turmoil of BRiFID, investment firms and regulated markets have a near to real-time responsibility to make sure their RTS 1 equity-like and RTS 2 non-equity trades are reported within one minute and 15 minutes respectively (reducing to five minutes by 2021). The responsibility wording is key. Firms may think they do not have a reporting responsibility or they may have asked their brokers to report on their behalf but have firms put in place the correct control framework to prove this if the regulators come calling?  Could this highlight a firm’s unknown unknowns?

    MiFID II has now been live for almost 15 months. With Brexit there is the very real situation that post-trade transparency reporting will need to be directed to either the EU or UK APA as well as liquidity shifting away from the main markets and the impact of ESMA’s Trading Obligation views.  This is a good time to make sure you’re also compliant with post-trade transparency reporting as well as transaction reporting. 

    What next?

    If you have any doubts about whether your post-trade transparency reporting and controls are up to the required standard, we can help. We have a proven track record in helping firms tackle their regulatory reporting issues and risks head on – and helping them to avoid censure. Our ReportShield™ quality assurance services provide everything you need for reporting assurance including a bespoke control framework, quality assurance testing of all fields on all reports, reference data testing, reconciliation and completeness checks and training. Contact us to find out more. 

  • FCA publish Market Watch 59

    FCA publish Market Watch 59

    Market Watch 59 is ‘almost totally dominated by Transaction Reporting Observations’ and marks yet another strongly worded message from the Financial Conduct Authority on the importance of complete and accurate transaction reporting and how it is critical to the FCA’s work to ensure that markets function well.

    As ever, the FCA stress the importance of adequate systems and controls over transaction reporting and highlights how these requirements are clearly defined in Article 15 of RTS22. In particular, the FCA stresses the importance of reconciliation of front office trading records against data samples from the NCA. It also notes that some market participants don’t appear to be aware of the FCA’s facility to provide this data and the need for regular and thorough reconciliation.

    Valid but incorrect reports

    One of the more important messages from the FCA’s Market Watch is that:

    “Firms should not assume that a report was accurate because it was accepted by the Market Data Processor, as business validation rules are not intended to identify all errors and omissions”

    As we already know at Kaizen, there are too many ‘valid but incorrect’ transaction reports. In amongst the errors highlighted by the FCA are a number of old favourites, including the transposing of the buyer and sell:

    • Incorrect time (especially after the transition to British Summer Time!!!)
    • Price not reported in the major currency
    • Venue populated with the operating MIC where a segment level MIC is available
    • Misreporting the buyer as the seller and vice versa (oh come on!)
    • Re-use of identifiers for multiple clients
    • Incorrect client type code
    • Inconsistency between trading capacity and buyer/seller IDs

    Instrument Reference Data

    There is slightly conciliatory tone on the rejections where the instrument ID, or underlying instrument ID, is not present on FIRDS. Whilst the FCA is still keen to point out this is sometimes the firms’ fault, using the wrong Venue code for example, quite often it results from incorrect reference data submitted by the trading venues. The FCA is clearly sending a message to the trading venues and systematic internaliser that greater control is required over their RTS23 reference data submissions.

    Errors and omissions notifications forms

     The FCA’s observations end on a particularly worrying note for many firms. It reminds firms that where errors or omissions are identified in transaction reports, participants must submit a corrected report to the NCA. Alas, the FCA has noted that some firms are submitting an errors and omissions form, but not subsequently correcting the errors or correcting errors without submitting an errors and omissions form. The FCA does not appear to be happy about this!

    How Kaizen can help

    This is exactly what we here at Kaizen exist to do.  We have a proven track record in helping firms tackle their trade and transaction reporting issues and risks head on – and helping them to avoid censure whether it is for RTS23, MiFIR, EMIR, Dodd-Frank or another G20 regulation. Please contact us for a discussion with one of our regulatory experts to find out more.

  • Lack of training results in transaction reporting breaches

    Lack of training results in transaction reporting breaches

    One of the most interesting statements from the FCA Final Notices following the recent fines for MiFID transaction reporting breaches concerned the general lack of expertise around transaction reporting in the industry. The firm impacted was clearly trying to do the right thing, but was hampered by “…a scarcity across the Firm and the industry of personnel with the expertise and systems knowledge required both to implement the enhanced controls and remediate the issues identified during the course of the project”¹ 

    It is difficult to understand why this lack of expertise should still afflict such an important area of compliance. Whilst it may not appear to be the most glamourous area of regulation, the FCA has shown a continued willingness to take action against firms for breaches. Many of the errors highlighted by the FCA appear to have been simple mistakes in the interpretation of the reporting requirements and might have been avoided through a more effective training programme. It should also be remembered that these fines relate to the old MiFID transaction reporting which is relatively simple compared to the greatly increased scope and complexity of the current MiFIR transaction reporting regime.

    Help is at hand

    At Kaizen, we believe effective training is an essential element in ensuring complete and accurate transaction reporting. We offer a half day CPD-accredited training course, endorsed by the Chartered Institute for Securities and Investment (CISI), which gives candidates a core understanding of the transaction reporting requirements and the fields that comprise a transaction report. The course can be taken at Kaizen HQ or at your own offices and is accompanied by an exam which enables you to demonstrate your understanding of the reporting requirements. Similar courses are available for EMIR trade reporting and SFTR. Visit our training page for further details and to book your place on one of our upcoming scheduled dates. 

    Are you a Transaction Reporting guru? Why not take part in #TransactionReportingTuesday over on LinkedIn.

    Every Tuesday, on the Kaizen LinkedIn we will be publishing a MiFIR Transaction Reporting question from our training exam. The answer will be posted a week later along with a new question. 


    ¹ FCA Final Notice to Goldman Sachs

  • FCA MiFID reporting fine – could it have been you?

    FCA MiFID reporting fine – could it have been you?

    Many firms were wondering when the first fine for MiFIR transaction reporting breaches would be levied by the FCA, so it might have come as a surprise to see a fine for a breach under the previous MiFID transaction reporting regime. We have seen strong signals from the FCA that it is disappointed with quality of some of the transaction reports it receives and it has been tireless in explaining that complete and accurate transaction reports are essential to monitor for market abuse effectively.

    Tough line

    Despite these warnings, some might have been thinking that the FCA was too occupied with Brexit to take enforcement action for transaction reporting breaches. The latest fine, at £27.6m after a 30% early settlement discount, is over twice as large as the previous fine for MiFID transaction reporting and should leave firms in no doubt that the FCA will continue to take a hard line with reporting breaches of both the MiFID and EMIR variety.  Many may be left considering what they should be doing to make sure they’re not the next subject of enforcement action.

    What failings did the FCA identify?

    Purely in terms of numbers, between 5 November 2007 and 24 May 2017, the firm:

    1. Failed to report 3,658,423 transactions;
    2. Inaccurately reported 83,074,015 transactions, and
    3. Erroneously reported 49,152,274 transactions.

    These look like very large numbers, but they have to be taken in context: In the period in question approximately 1.8 billion transactions were reported. This implies that the FCA didn’t raise any issues for approximately 1.665 billion transaction reports, or 92.5% of the submitted reports. It would be interesting to know how many senior managers are confident their firm is reporting more than 92.5% of its transactions correctly. Of course, they should be aiming for 100% complete and accurate reporting, but it is possible that many senior managers don’t actually know their accuracy rate.

    Systems and controls

    Of course, it isn’t just a numbers game. The accompanying Final Notice highlights a lack of sufficient systems and controls. In particular, the FCA stated there was a breach of Principle P3 by:

    1. Failing to have adequate systems and controls to ensure that reference or ‘static’ data used for various mandatory fields in the transaction reports submitted to the authority were complete and accurate;
    2. Failing to have in place adequate change management controls to manage changes affecting transaction reporting processes and systems, and
    3. Failing to undertake appropriate testing to ensure the completeness and accuracy of transaction reports.

    It is particularly interesting to note the criticisms in the Final Notice of the control framework calling out that it “did not adequately test and reconcile the completeness and accuracy of all transaction reporting data from its front office systems to the ARM reporting to the Authority.”

    Lessons to be learned

    The obvious lesson is that the FCA is actively enforcing transaction reporting. If your firm does not have adequate systems and controls in place or doesn’t even know how good (or bad) its reporting is; you could be at risk.

    Interestingly, in reference to the weakness of the reconciliation and testing controls, the notice called out the “periodic, sample based” nature of them. The limitations of sample testing and the false confidence that it provides has been one of the root causes of many a fine. At Kaizen, we provide quality assurance testing on all transaction reports and our reconciliation service tests all trades in the front office systems, determines whether they should be reported, and only then reconciles against the reports submitted to the regulator. We can also advise on the control framework, test all reference data (including ISINs, counterparty LEIs and for natural persons) and provide training on the regulatory requirements.

    Firms need to react

    When issues are identified by the FCA the clock is ticking. Firms should take any issue identified by the FCA as a trigger to not only investigate the issue raised but to look across all of its reporting to make sure it is correct. Flushing out issues quickly is critical in maintaining the confidence of the FCA. The industry is littered with examples of firms that have completed reviews and improved procedures only to have issues found many months and sometimes years later.

    Senior Managers liable

    The Senior Managers and Certification Regime (SMCR) has increased the reporting risks by making senior managers personally liable for transaction reporting controls.  The SMCR is soon to extend to all core firms at the end of the year.  Firms and their senior managers need to examine the systems and controls they have over transaction reporting and ask themselves whether they truly understand whether they are meeting the FCA requirements or whether they could be potentially next in line for enforcement action.

    If you have any doubts whether your reporting and controls are up to the required standard, we can help.  We have a proven track record in helping firms tackle their transaction reporting issues and risks head on – and helping them to avoid censure.Our ReportShield™ quality assurance service provides everything you need for reporting assurance including a bespoke control framework, quality assurance testing, reference data testing, reconciliation and training.  

    Please contact us for a discussion with one of our regulatory experts to find out more.

  • White Paper – Brexit can damage your MiFIR transaction reporting and EMIR trade reporting

    White Paper – Brexit can damage your MiFIR transaction reporting and EMIR trade reporting

    UPDATED – 19 February 2019

    As we get closer to the withdrawal date, we have seen a flurry of statements from ESMA and the FCA on the impact of a hard Brexit on MiFIR and EMIR reporting obligations. As a result, we have revised our Brexit White Paper to take account of the recent statements.

    One of the most interesting developments was the statement from ESMA that EMIR trades and positions submitted to an EU trade repository by a UK counterparty would not need to be modified or updated post 29 March. The onus will be on the trade repositories to terminate these reports in the event of a hard Brexit. Before UK firms start celebrating, it should also be noted that these trades and positions could be ported to the newly established UK trade repositories and it is expected that firms will have to update and modify these trades as per usual. In effect, it is quite a seamless solution for firms and regulators alike. 

    As we’ve all discovered, Brexit is a fantastic opportunity to upset friends and family by sharing our expert views on the subject.

    Unfortunately, it will also have a profound effect on MiFIR transaction reporting and EMIR trade reporting.

    If there weren’t enough things to consider, we need to assess the impact it could have on branches, delegated reporting, outstanding trades, reportable instruments and personal data standards, just to name a few.

    Whilst it is tempting to bury our heads and wait for it all to blow over, the sad fact is that the impact on reporting could be brutal.

    We recommend that you put on your tin hats, batten down the hatches and prepare for a bumpy ride. What better way to start than reading our revised White Paper on the potential impact Brexit could have on your reporting? 

  • Alpha FMC and Kaizen to provide transaction reporting compliance assurance service

    Alpha FMC and Kaizen to provide transaction reporting compliance assurance service

    Combined proposition will assess governance and control frameworks and identify any gaps in MiFID II transaction reporting obligations.


    FOR IMMEDIATE RELEASE

    5 February 2019, London: Alpha FMC the global leader in asset and wealth management consultancy, has teamed up with multi-award-winning Kaizen Reporting, the specialist regulatory reporting firm. The collaboration will comprise a “health check” for specialist wealth managers and smaller asset managers by providing independent transaction reporting assessments. 

    The new proposition will see Kaizen’s proprietary testing technology combine with Alpha’s wide-ranging global asset and wealth management expertise to provide independent and expert assurance to wealth and asset managers that their transaction reporting arrangements meet the standards required by MiFID II.

    The combined proposition will check the accuracy of all of an institution’s reported data, assess the effectiveness of firms’ governance and control frameworks, and identify any gaps they might have in meeting the regulator’s transaction reporting obligations.

    “The proposition is an ideal solution for asset and wealth managers with lower trading volumes who require peace of mind that they are reporting accurately and correctly.” 

    The key benefits of the proposition include:

    • Full visibility of the quality of data reported to the regulator, including accuracy testing of all instruments, scenarios and data fields
    • Review of existing transaction reporting governance and oversight framework
    • Independent assessment and recommendations for regulatory compliance
    • Fast execution and outcomes

    The proposition comprises a discovery phase, using a detailed questionnaire to cover transaction reporting compliance and the process involved. This is followed by an evaluation phase involving a thorough assessment of the regulatory reporting control and governance framework.

    Reporting quality will be checked by Kaizen’s accuracy testing service which assesses all data fields on all reported transactions to provide a complete picture of reporting integrity. Recommendations will then made on whether transaction reporting controls are robust and whether the required level of testing is in place.

    Andrew Glessing, Head of Regulation, Compliance and Risk at Alpha FMC said:

    “We are delighted to work alongside Kaizen, who are the standard-setters when it comes to reporting assurance. With MiFID II requirements now a year old, this is the perfect time for specialist wealth and asset managers to take stock of their reporting quality and processes. We think this proposition fills a gap in the market by providing firms with market leading assurance tools and expert advice on their transaction reporting arrangements.”

    Dario Crispini, CEO of Kaizen, said:

    “This is an important milestone in Kaizen’s timeline. By joining forces with Alpha, we are able to offer the wealth and asset management sector a vital snapshot of the quality of its transaction reporting through an all-important health check. I am delighted we are working together.”

    “The proposition is an ideal solution for asset and wealth managers with lower trading volumes who require peace of mind that they are reporting accurately and correctly.  We recommend health checks take place periodically for ongoing visibility of reporting quality or in some circumstances, more regular testing may be required

    (ends)

    For media inquiries, please contact Fiona Wilde on media@kaizenreporting.com or +44 (0) 20 3912 3271.

  • ESMA updates Q&A on MiFIR and EMIR reporting

    ESMA seemingly delivered a double whammy on 4 February with the publication of Q&As for both MiFIR and EMIR data reporting. However, there’s nothing to get too excited about, although firms do need to understand the ‘clarification’ and adjust their reporting accordingly.

    Impact on MiFIR data reporting

    Bit of a damp squib. There is only one question that relates to transaction reporting (TVTIC on complex trades); the others all relate to RTS 23/MAR reference data reporting. The clarifications can be summarised as follows (italics indicate direct quote from the Q&A):

    How should the TVTIC (field 3 of RTS 22) be populated in transaction reports of a complex trade?

    Bit of a change here. Previously, firms were required to put the same TVTIC on each leg of the reported trades (if they were traded on a trading venue). New instruction is to use the TVTIC provided by trading venue for each leg of the complex trade (where the trading venue uses multiple TVTICs)

    How should Field 15 (Maturity date) of Table 3 of the Annex to RTS 23 and related MAR RTS and ITS be populated in case of trading in bonds after their originally intended maturity date?

    “For bonds that were not paid out on the originally intended maturity date (and therefore have not expired, because, for example, they defaulted), the maturity date should be set to 9999- 12-31 …until they are finally paid out, in which case the maturity date should be updated with the actual date of redemption”.

    How should field 15 (maturity date) and field 24 (expiry date) of Table 3 of the Annex to RTS 23 and related MAR RTS and ITS be populated, if these dates are non-trading dates, e.g. a weekend or a bank holiday?

    “The maturity date/expiry date defined by the issuer or the prospectus of the financial instrument should be used. No adjustment should be made to the next or previous working day for the purpose of instrument reference data reporting.”

    When should an instrument be terminated in FIRDS?

    “When field 12 (termination date) of Table 3 of the Annex to RTS 23 and related MAR RTS and ITS is initially left empty, the reporting entity is expected to fill it in when the instrument is going to be terminated. This also includes the cases when the given instrument has matured/expired, i.e. where fields 15 (maturity date) or 24 (expiry date) are applicable to the given instrument and are populated in the report.

    The termination date should be earlier than or equal to the maturity/expiry date in the cases where the maturity/expiry date is populated.”

    (RTS 23)What action should be taken by the operator of the trading venue or the systematic internaliser in the cases where the LEI of the issuer cannot be obtained?

    Tell the issuer that they should get an LEI (!!!).


    Impact on EMIR Data Reporting

    There are only three clarifications in the EMIR data reporting Q&A – the first two are amendments to previous trade reporting questions whilst the third is a brand new question:

    Q34 – Reporting of contracts with no maturity date (e.g. CFDs);

    ESMA simply reminds firms that they can also report new trades for instruments with no maturity date with an ‘Action Type’ of ‘P’ (“position component”) if it is to be included in a position level report on the same day. This is in line with previous comments from ESMA.

    Q38 – Trades terminated before the reporting deadline

    All trades must be reported even if they are terminated before the reporting deadline and ESMA is simply clarifying that these reports could also be made with an Action Type of ‘P’ if the trade is to be included in a position level report, on the same day.

    Q50 – Reporting of Confirmation Means

    ESMA states:

    The value ‘N’ (not confirmed) should be used either when:

    • The derivative has to be confirmed by the counterparties but has not been confirmed yet;
    • The derivative does not have to be confirmed by the counterparties because it has been traded on a trading venue and once traded all the terms of the contracts are known and agreed by the parties.

     In other cases, the counterparties should report the ‘E’ or ‘Y’ value for this field depending on the confirmation means used (electronic or non-electronic).

    I think this is the one element in the new Q&As that may surprise some firms as it clearly states that trades on a trading venue should have a value of ‘N’.

    So, not a lot really going on with the new Q&As. It is tempting to think that little news is good news. Personally, I don’t subscribe to this point of view; I think there is still plenty of grey in there that would benefit from further clarification, which is natural given the fundamental changes brought in by MiFIR. I also think there are a few elements in the Guidelines that, with hindsight, could have been better – (equity swaps is my favourite bugbear today).

    If you have a burning MiFIR or EMIR reporting question keeping you awake at night, why not contact us at Kaizen.

  • Another year of significant growth, success and development for Kaizen

    Another year of significant growth, success and development for Kaizen

    FOR IMMEDIATE RELEASE

    17 December 2018, London: Leading regulatory reporting firm Kaizen Reporting, developer of the multi-award-winning assurance service, ReportShield™, has rounded off a successful year of exciting expansion, both of its specialist team and its services, consolidating its market-leading reputation. With several influential senior hires, the launch of a tailored, expert-led regulatory reporting training service and numerous prestigious award wins, Kaizen has continued to set itself apart at the forefront of the industry.

    Kaizen began the year with a significant partnership with challenger consultancy Elixirr to deliver a complete end-to-end regulatory reporting remediation service for financial institutions, a much-needed partnership for responding to increasing levels of complexity in market regulations.

    This was followed with the hiring of two senior staff: the former chair of the ICMA taskforce on SFTR, Jonathan Lee, and the former regulator and EMIR and MiFIR expert, David Nowell. The addition of two highly-respected regulatory veterans further consolidated Kaizen’s position as market leader, bringing clients even greater assurance services for EMIR, MIFID II transaction reporting, Dodd-Frank and SFTR.

    Kaizen continued to win awards, and in December ReportShield was named ‘Best New Regulatory Reporting Product’ by the FOW International Awards. It was also one of a select group of companies chosen to exhibit at the fourth annual FIA Innovators Pavilion in Chicago, launched to showcase forward-thinking solutions for the global derivatives market. In addition, Kaizen was listed in the RegTech 100, a global directory of companies providing the most innovative solutions in regulation.

    Earlier this month Kaizen announced an expansion of its MiFIR offering, adding APA trade reporting. At the same time Chris Machin, a MiFIR trade reporting specialist, joined Kaizen to head the development of its new service.

    Dario Crispini, CEO of Kaizen, commented: “Our successes in 2018 are down to the commitment and innovation of our fantastic team here at Kaizen. We have doubled our client base and increased the staff numbers supporting our clients by a third. We have made even greater strides towards solidifying our position as the leading regulatory assurance provider. It’s not only a testament to our hard work, but also to the value of the service we are delivering to our clients.”

    “Our successes in 2018 are down to the commitment and innovation of our fantastic team here at Kaizen”

    Ian Rennie, Managing Director of Kaizen, added: “What I think has particularly differentiated this year from previous years is the expertise we have brought on board in the form of Jonathan, David and Chris. We now not only offer an unrivalled service across more regimes but also the specialist expertise from well-known players in this space, bringing even more peace of mind to our clients.”

    Dario continued, “Looking ahead to 2019, we will see regulators increasingly focus on the quality of data being reported for MiFID II, EMIR, Dodd-Frank and other G20 regulations. For MiFID II in particular, the UK regulator, the FCA, is already writing to firms to warn them about improving their data quality. We will also see the extension of the SMCR regime which will put further pressure on senior individuals within financial institutions to ensure their reporting is accurate and complete. And now that the regulatory technical standards have been approved, preparation for SFTR reporting will also increasingly demand time and focus from financial institutions. Putting the right controls in place at an early stage will result in compliant and efficient reporting from go-live”

    ReportShield is a set of services that help financial firms meet their reporting control obligations and effectively manage their reporting risks.  The service includes Kaizen’s award-winning accuracy testing which is unique in its ability to test all reported data, providing firms with full visibility of the quality of their reporting.

    (ends)

    For media inquiries, please contact Fiona Wilde at communications@kaizenreporting.com or +44 (0) 20 3912 3271.

  • Deep into the soul of regulatory reporting in 2018

    Deep into the soul of regulatory reporting in 2018

    We look back at the regulatory reporting year that was through the songs of Aretha Franklin (sorry Aretha).

    We saw yet another true legend sing her last note this year as the world stood United Together and said a fond farewell to the awe-inspiring Aretha Franklin. We apologise to any fan and most importantly to the great lady herself as we look back at the key regulatory reporting developments of 2018 through her songs and lyrics. I am afraid we have not learnt from our 2016 Bowie travesty….

    MiFIR transaction reporting go-live

    This time last year many of us were running through go-live lists rather than Santa lists and thinking, “I’m going to Drown in my own Tears“. However all that hard work did pay off and all involved deserve their very own Dr Feelgood feeling for their efforts. On the whole, firms got across the line despite the headwinds that presented themselves in the form of instrument data issues (FIRDs / DSB teething issues, understanding TOTV implications, identifying reportable indices), missing LEIs, rogue validation rules at ARMs and the regulator (to mention just a few).

    Though what January really signaled was the beginning of the journey and not the end. Firms’ efforts in the first months of the year were focused on reporting as much of their business as possible and dealing with the inevitable spike in validation breaks from the ARMs and competent authorities. Now the equally hard part of putting in controls to comply with RTS 22 Article 15, to check that what is reported is accurate and complete, before the regulator does, is the new priority.

    ESMA has been very busy

    We always say that regulatory reporting is the gift that keeps on giving, but ESMA can be a little like your eccentric Aunt Vera in delivering something you didn’t ask for and didn’t really want. Well, Vera has certainly been busy this year.  We had new iterations of the EMIR Q&A from ESMA on 12 July and 26 July. And since MiFIR reporting went live on 3 January, we had updates to the Q&A on 25 May and 26 September and some tweaks to the validation schemes as well.

    To be fair to ESMA, we haven’t had the avalanche of information overload we experienced in 2017 and the Q&A mechanism is an essential tool to help bed-down the new reporting regimes so we are Willing to Forgive. Whilst change can often be painful, you can always rely on Kaizen to ensure our ReportShield™ testing reflects the very latest gift from ESMA to keep you One Step Ahead.

    The FCA and SMCR

    When it comes to the Senior Managers and Certification Regime (SMCR) regime it is plain for all to see that the FCA is expecting firms to demonstrate some Respect. In the coming year, the regime will be extended to the core SMCR firms under which an individual within a firm will be ultimately responsible for ensuring that a firm complies with the conduct rules and expectations. Being able to evidence their firm’s reporting is accurate and complete will be a key demand from those who hold this responsibility.

    SFTR

    Having published its Final Report: Technical Standards under SFTR and certain amendments to EMIR back in March 2017, ESMA and the market anticipated that by December 2018 this would be a live reporting regime for investment firms and credit institutions (banks). All that was needed was European Commission endorsement and the legislative steps that follow….

    The European Commission had a Think and after 15 long months eventually piped up I Knew You Were Waiting in late July 2018, albeit with a long list of proposed amendments; largely semantics. Unfortunately, the Commission also decided that A Change is Gonna Come in reference to the rights that ESMA claimed to govern UTI and branch LEI standards endorsement. They left it with ESMA, Call Me.

    ESMA responded to the proposed amendments in September 2018, but unfortunately, it was not with Amazing Grace but rather a dismissive ‘Non,’ rejecting all the changes. The ball is now firmly in the European Commission’s court and as for the bickering, we’re sure It Hurts like Hell but to date, they have not yet found a Bridge Over Troubled Water and endorsed a final RTS for European Parliamentary and Council scrutiny. May the market sing Oh Happy Day when ESMA and the EC stand United Together and we get some certainty over the timing of SFTR go-live.

    Trade reporting and Jumpin’ Jack Flash

    So quite like Jumpin’ Jack Flash, trade reporting for MiFIR started on 3 January 2018 like a cross-fire hurricane with levels of uncertainty and clarity over different aspects of the regulation and the whole market frowned at the crumbs of a crust of bread at the quality of data.

    Firms howled at the morning driving rain with the barrage of Q&A updates throughout the year but as mentioned previously, this has certainly helped bring clarity to many grey areas within the regulation.  DVC, LEI and SI regime delays helped investment firms that felt drowned, washed up and left for dead by the various regulatory demands placed on them.

    What does 2019 hold for us?  The derivatives systematic internaliser regime. Could we start to see a penalty or sanction regime set out by ESMA and the NCAs which could leave investment firms crowned with a spike right through my head?  Questions still do remain though as to whether transparency and a level playing field has really been achieved…

    A view from across the Atlantic

    The CFTC has also been busy in 2018. Two White Papers published suggest that in these Ever Changing Times it is necessary to refresh the Dodd Frank(Iin) Act.

    The first paper, ‘Swaps Regulation Version 2.0’ sets out new proposals to change reporting to a T+1 model and bring in more detail to collateral data requirements. The second paper, which had us singing Border Song, sees The Weight of regulatory burden somewhat lifted for non-US entities where risk is sufficiently monitored by their home regulations.

    No official new rules or timeline has been given yet but we hope the CFTC will Get It Right when legislation is published. We’ll work with our clients to Jump To It and make the necessary preparations when the time comes.

    Brexit – I say a little prayer

    As we approach the end of the year the shadow of Brexit looms large for everyone.  We will share our thoughts on the impact on reporting early in the New Year but in the meantime, season’s greetings from all of us at Kaizen and we wish you a restful break with your family and friends. We thank you for your continued support and we look forward to helping you feel Rock Steady about your reporting quality in the New Year and beyond.

    If nothing else, we hope you have enjoyed listening to some fantastic and enduring classics…you can listen to our Spotify playlist here.

    With thanks to Kaizen Reporting’s industry leading reporting experts for their contributions. Dario Crispini, David Nowell, James Mooney, Jonathan Lee and Chris Machin.

  • How was it for you? Take our survey on the EMIR RTS changes

    How was it for you? Take our survey on the EMIR RTS changes

    Share your views 

    It’s a year since the revision to the EMIR Reporting Technical Standards (RTS) went live*. The resulting changes were fundamental including a significant increase in the number of reportable fields (from 85 to 129), significant changes to taxonomies, and additional asset class specific fields. Many participants struggled with implementation, particularly as there were competing compliance projects, including preparation for MiFID II transaction reporting, on-going at the same time.

    We’re a nosy bunch at Kaizen and we would love to hear your views on last year’s EMIR RTS changes and how valuable you feel the data is to the regulators.  Please head over to our short survey to have your say.  All responses are anonymous.

    *OK, the trade repositories implemented the changes on the Monday, but technically they were intended for implementation on 1 November 2017.


  • Stockholm conference: New regulatory insights on EMIR and MiFIR reporting

    Stockholm conference: New regulatory insights on EMIR and MiFIR reporting

    It was great to be a part of last week’s Trade and Transaction Reporting Northern Europe Conference in Stockholm and in particular, hear insights from the European Commission and the Dutch and Finnish National Competent Authorities (NCAs) on EMIR and MiFIR, as well as the latest on SFTR reporting timelines. 

    European Commission’s Fitness Check

    Gerd Heinen, Policy Officer at the European Commission, spoke about the Commission’s ‘Fitness Check’ on supervisory reporting. The objective of the Commission’s project is to “identify areas where the cost and burden of supervisory reporting can be reduced without compromising the objectives of financial stability, market integrity, and consumer protection”. I’m sure both the reporting firms and the recipient regulatory bodies would agree this is a worthy and valuable project. However, the two sides certainly didn’t agree in their responses to the Commission’s public consultation, particularly on whether the reporting requirements were fit for purpose.

    The Commission published a summary report following its consultation, which contains some fascinating statistics and cost estimates. My particular favourite is that only four per cent of respondents thought that all the existing supervisory reporting requirements were relevant for maintaining financial stability and upholding market integrity and investor protection. I also enjoyed the Commission’s observation that “out of 391 responses received, 258 came from industry stakeholders (all of which were in the same sector and from the same member state), who provided very similar responses to sections 1 and 3”.

    The Commission expects to publish its conclusions of its Fitness Check in the first half of 2019 and ‘if necessary’ follow publication with recommendations to streamline and simplify supervisory reporting.

    MiFIR data quality issues in Europe

    I equally enjoyed a joint presentation from the Dutch and Finnish National Competent Authorities (NCAs) on their observations on MiFIR transaction reporting implementation. From a Brexit perspective, it was interesting to note that just over 50% of all transaction reports received by the Dutch NCA were from UK firms routed via the UK’s FCA. The corresponding figure for the Finnish NCA was even higher at roughly 80%.

    When it came to reporting quality issues, the Dutch and Finnish regulators presented the following areas of concern:

    • Gaps in reporting
    • Rejected transactions not corrected
    • Use of CONCAT instead of higher priority identifier
    • Incorrect national identifier format
    • Wrong trading venue identifier (On market vs XOFF) – Operator MIC instead of Segment MIC
    • LEI codes
    • Timestamp granularity
    • Default trading times
    • Trading place identifier
    • Price
    • Reporting of transaction chains
    • Non-flat ‘INTC’ end of day.

    There are some similarities here with the UK FCA findings presented in their summer forum. However, it is noticeable that this work extends beyond the relatively simple ESMA defined validations and firms need to be aware that the NCAs are now extending their quality assessment to ‘business validations’ such as ‘flat INTC accounts’ as well.

    At Kaizen, we believe you need to be a few steps ahead of the NCA in discovering errors in your transaction reports.  Even if reports pass through the ARM and NCA validation checks, it doesn’t mean that the data contained within them is correct. Our accuracy testing service carries out over 1000 tests on every transaction report to detect errors and give full transparency of the quality of your reporting so you don’t fall foul of the regulator. 

    For more information on Kaizen’s accuracy testing and how we can help solve your MiFIR (and EMIR) reporting challenges, please contact us.

  • Book now! Kaizen launches regulatory reporting training service led by industry expert David Nowell

    Book now! Kaizen launches regulatory reporting training service led by industry expert David Nowell

    FOR IMMEDIATE RELEASE

    23  October 2018, London: Leading regulatory technology firm Kaizen Reporting today announced that it is launching a training service led by the company’s new Senior Regulatory Reporting Specialist, David Nowell. The training will initially focus on MiFIR transaction reporting before expanding to include EMIR trade reporting and the upcoming Securities Financing Transaction Regulation (SFTR).

    A former regulator, Nowell has 30 years’ financial services experience. Having previously worked as a transaction reporting technical specialist at the UK FSA, as head of transaction reporting for a tier-1 investment firm and head of compliance for an Approved Reporting Mechanism and Trade Repository, David has a thorough understanding of both the importance and the challenges in meeting the regulatory reporting requirements. He also has extensive experience of client training on both MiFIR transaction reporting and EMIR trade reporting.

    Dario Crispini, CEO of Kaizen, commented: “David is widely seen as a leading authority in the industry. The FCA frequently warns about the risk to institutions of inadequately trained regulatory reporting teams and in many of its warning notices cites a lack of training as a factor in its decision to censure a firm for incorrect reporting.  Expanding our services to include training makes sense for us, and we are looking forward to helping our clients improve their knowledge in this space.”

    David Nowell, Senior Regulatory Reporting Specialist at Kaizen, commented: “Training is an integral part of the systems and controls that firms need in place to be reporting accurately. It’s impossible to get your regulatory reporting correct unless you understand the legislation from the Level 1 text down to the regulatory technical standards, guidelines, Q&A and validations. Our new courses are designed to help get our clients up to speed quickly, allowing them to understand what needs to be done to report correctly as soon as possible.”

    David adds, “Ensuring your staff are properly trained on the reporting regulations can save costs in the long run as it will increase a firm’s chances of avoiding regulatory sanctions for incomplete or inaccurate reports and the additional expense of costly back reporting exercises.”

    The training service includes four-hour classroom-style workshops as well as in-house sessions for financial institutions. 

    (Ends) 

    For more information please visit our training page or for inquiries about the service please email training@kaizenreporting.com

    For media inquiries, please contact Fiona Wilde at media@kaizenreporting.com or +44 (0) 20 3912 3271.

  • Join us in Stockholm for the Trade and Transaction Reporting Conference

    Join us in Stockholm for the Trade and Transaction Reporting Conference

    We are very pleased to be taking part in the Infoline Trade and Transaction Reporting Northern Europe Conference on 17 October in Stockholm. The conference is aimed at investment and securities firms, banks and trading venues impacted by the reporting and disclosure obligations of EMIR, MiFID II,and SFTR.   

    On the agenda are our very own Senior Regulatory Reporting Specialists David Nowell and Jonathan Lee who will give practical insight on EMIR and MiFIR reporting data quality (David) and taking the pain away from SFTR transaction reporting implementation (Jonathan).

    We’d be delighted to see you there and would love to pass on a 30% saving on your conference pass (please quote FKM63655KR). 

    Event details:

    For more information, please don’t hesitate to contact us.

  • Tales from the crypt – the great cryptocurrency derivatives EMIR reportability debate

    Tales from the crypt – the great cryptocurrency derivatives EMIR reportability debate

    Cryptocurrencies are often seen as a great way to get rich quick, or poor quicker. To be honest, if I wanted to lose a shed load of money, I’d much rather nip down the bookies and put it all on Tripod Lad to win the 3:30 at Kempton Park. Whilst it might fall at the first fence, at least I would have some idea about the mechanics preventing it reaching the winning post. However, my approach to losing money is looking increasingly old school. It appears that there’s nobody left on the planet who doesn’t know somebody holding a fraction of a bitcoin in the hope that it will miraculously increase in value enough to put their grandkids through university.

    So, how worrying is the rise of the derivatives on cryptocurrencies? Well, we’ve certainly seen extreme volatility in this asset class, commonly attributed to investor behaviours of herding and regret-aversion. Does this create systemic risk? Well, it’s tempting to believe this asset class isn’t mature enough yet to represent a risk to the entire financial system. However, the launch of exchange traded derivatives on cryptocurrencies has led to involvement of increasing numbers of systemically important financial institutions in this asset class. The CFTC Chairman J. Christopher Giancarlo has warned whilst cryptocurrency derivatives are a relatively small market in terms of systemic risk, it is one that the CFTC needs to watch carefully.

    So, we hope this is a development the EEA regulators are also watching carefully. Surely this is one of the good things about EMIR trade reporting – ESMA and other EEA regulators will have had 6 years of analysing cryptocurrency derivatives to assess whether they could have the potential to grow and become a new threat to financial stability. Or have they? Possibly not, as there is a great deal of confusion in the industry as to whether cryptocurrency derivative instruments are actually reportable at all under EMIR. Whilst some firms have decided to trade report them to trade repositories, others have not. The confusion stems from the definition of reportable derivatives. EMIR takes this definition from MiFID and the FCA has explained that whilst cryptocurrency derivatives are “capable” of being financial instruments under MiFID II, it does not consider cryptocurrencies to be currencies or commodities under MiFID II. This is unfortunate as it leaves firms with the added dilemma that if these derivatives are EMIR trade reportable, exactly how should they be reported. Those firms that have chosen to report have taken the decision to report as commodity derivatives; mainly because the ESMA validation for currency derivatives requires an official ISO currency code and cryptocurrencies do not have one.  However, it is debatable whether reporting cryptocurrencies as commodities will deliver much value to the regulators as they will not be recognisable as cryptocurrencies from the report. Maybe the perfect opportunity to address this issue would have been through the fundamental changes to the reporting technical standards implemented in October 2017.

    The reporting of cryptocurrency derivatives may be one of the “known unknowns” in EMIR reporting. However, there are many known reporting errors in EMIR trade reporting that make it through the ESMA validation scheme. Just because a trade repository has accepted a report doesn’t mean it is error free. Some firms consider EMIR trade reporting to be a “fire and forget” reporting regime apparently forgetting the obligation for “complete and accurate” reporting so long as “T+1” is achieved. However, ESMA’s 2017 Annual Report and 2018 Work Programme makes it abundantly clear that the quality of data reported to TRs is not good enough and needs to be improved.

    How good is your EMIR trade reporting? Our ReportShield™ quality assurance service delivers an independent and comprehensive analysis of the accuracy and completeness of your EMIR trade reports. For a consultation with one of our experts, please contact us.

  • In the news: David Nowell on the FCA’s ‘first warning’ to industry on transaction reporting improvement

    In the news: David Nowell on the FCA’s ‘first warning’ to industry on transaction reporting improvement

    Kaizen’s senior regulatory reporting specialist David Nowell spoke with Thomson Reuters Accelus about the recent forums where the FCA’s markets reporting team set out the common mistakes that firms had made on reports and urged them to focus on accuracy and completeness. 

    David’s recent blog covered the mistakes in detail, and when speaking to Thomson Reuters he said, “The temptation with MiFID II transaction reporting is to get across the line. With EMIR some firms took the fire and forget approach to reporting. With MiFIR, the recent transaction reporting forums should have woken up firms to the fact that improving their reporting is an ongoing job.” 

    If firms fail to correct the mistakes, eventually there will be fines. 

    David said, “Firms should be in no doubt of what needs to be done to achieve complete and accurate reporting. A firm may get away with a private warning, but it will be asked to back report and engage in remediation. Even then, the firm might not find everything that’s wrong with its reporting and will incur the cost of re-reporting again.”

    Read the full article: First warning: UK FCA sets out expectations for MiFID II transaction reporting improvement (a subscription-only site). 

    • Kaizen’s award-winning ReportShield™ quality assurance service checks transaction reporting data for accuracy, completeness and timeliness. What sets ReportShield™ apart is that it tests every single data field so you get a complete picture of what’s wrong and right with your reporting. 
    • ReportShield™ includes accuracy testing, advanced reconciliation, reference data testing and a control framework – everything you need to be compliant with your regulatory reporting obligations. 
  • The FCA’s mid-year report on MiFID II transaction reporting

    The FCA’s mid-year report on MiFID II transaction reporting

    School’s out for summer and financial firms are being handed their report card by the FCA. Is it an A for effort and a D for quality?

    The FCA’s MRT has hosted a transaction reporting forum where they focused on data quality and completeness for MiFID II. The forum slides have been published and they contain some fascinating data on the extent and quality of data submitted in the first six months of the new reporting regime. During this period, the FCA ingested nearly 3.5 billion transaction reports, but also had to reject a large number of reports. The FCA produced the following list of its top ten rejections:

    1. Instrument is not valid in reference data on transaction date (CON-412)
    2. Underlying instrument is not valid in reference data on transaction date (CON-472)
    3. Country of branch membership is missing (CON-370)
    4. Commodity derivative indicator is missing (CON-640)
    5. Instrument classification identifier is incorrect (CON-430)
    6. No underlying reported for swap transaction (with direction indication CON-473)
    7. Net amount is missing (CON-351)
    8. Transaction report with the same transaction reference number has already been sent for the firm and not cancelled (CON-023)
    9. Transaction for cancellation cannot be found (CON-024)
    10. Transaction has already been cancelled (CON-025)

    The top two rejection reasons both concern instrument validation and I don’t think these will be a surprise to anybody. It’s difficult to know who is responsible for these rejections as the reference data the FCA uses (the ESMA ‘FIRDS’) is not perfect and should not be considered a “golden source” – in Market Watch 54, the FCA reported that “ESMA states that it cannot take any responsibility for this information [FIRDS] being complete, accurate or up to date”. Firms need to report instruments that are reportable (!) but sadly FIRDS may still not be a perfect source to test against this obligation and instrument reference data remains a key concern for reporting firms.

    Whilst firms are at fault for the majority of these rejections, it’s perhaps unfair to blame them exclusively for all the rejections caused by points three through to seven. We know firms have received rejections for missing ‘country of branch membership’ when the ‘venue’ field has been populated with a systematic internaliser (which would appear to be inconsistent with the ESMA validation rule). Some of the other rejections are dependent upon the CFI (instrument classification) being correct in FIRDS and FIRDS hasn’t always been up to the task. Some participants have also questioned whether some of the ESMA validations have been designed correctly. For example, ‘Net amount’ is required for all cash bond transactions, but this validation is determined by CFI code starting with the characters ‘DB’ which unfortunately captures instruments such as ETCs (exchange traded commodities like iShares Physical Gold ETC) which have a debt structure but aren’t the type of instruments that logically have an associated ‘net amount’ value. Similarly, some participants have questioned the relevance of the underlying direction indictor for CDSs and whether the validation is consistent with the example detailed in ESMA’s Guidelines document.

    The FCA continues to provide excellent feedback on reporting issues and the importance of providing complete and accurate transaction reports. However, it would be a mistake for firms to assume that their reports are adequate just because they pass validation and are accepted by the FCA. Validations do not check whether the actual data contained within the reports is correct, something that our quality assurance testing is able to do. The accepted reports are just the tip of the iceberg and it is the issues that lie undetected underneath the water that we are able to identify with our testing.

    Read: Mark Steward, the FCA’s Director of Enforcement and Market Oversight’s speech on MiFID II and the fight against financial crime.

    Further reading: Ian Rennie on the issues we’ve seen so far in our MiFID II testing. 

  • Tell me LEIs

    Tell me LEIs

    The six-month grace period granted by ESMA for reporting firms to obtain Legal Entity Identifiers (LEIs) ended earlier this month. At her recent speech in Paris, ESMA’s executive director, Verena Ross, marked that the ‘No-LEI-no-trade’ rule now forces entities trading in EU markets to have an LEI. This allows the regulator to know exactly who is trading and enables market data to be aggregated in a more accurate manner. Verena Ross also recommended that regulators across the globe follow suit and make similar mandates.

    Someone from the HKMA must have been listening, because on the same day as the speech they announced their intention to extend regulation on the use of LEIs. From April 1st 2019, reporting entities, HKTR members, CCPs and clearing service providers must report all new trades with LEIs. Parties that do not identify themselves in the ‘Reporting for’ field and updates to existing trades will not require LEIs just yet. Similar to ESMA’s grace period, reporting entities are expected to have a process in place to request their clients obtain an LEI.

    Our research shows that of the 250 or so HKTR members, 90% of them already have LEIs. Alongside this, DTCC noted in their feedback to the proposal that some 4,200 HK based entities already have LEIs. It’s possible that MiFID II has already broken the back of the burden of obtaining LEIs in other jurisdictions.

    LEIs are becoming the industry’s gold standard for trade party identification and they are evolving too. Last year GLEIF introduced level 2 data that gave birth to LEI parent reference data being embedded in the LEI.

    In the future, we hope that LEIs will continue to evolve and that other entity static data can be hardcoded into their DNA. Features like CFTC US person status or Canadian Local Counterparty Status would do the industry a huge favour in terms of getting their reference data correct.

    Reference data errors account for 50 per cent of errors found in our testing of regulatory reports. Our ReportShield™ reference data testing checks both counterparty and instrument reference data for accuracy and completeness including real-time check of LEIs.  Contact us for a discussion on improving the quality of your reference data.

  • MiFID II reporting: what we’re seeing six months in

    MiFID II reporting: what we’re seeing six months in

    Six months in, MiFID II is still leaving practitioners and regulators alike scratching their heads with a number of seemingly intractable problems. The reporting of derivatives in particular is causing difficulty as firms continue to struggle with reporting eligibility concerns, the misreporting of certain fields and validation issues. Firms have sometimes been unable to get a copy of what they reported to their regulator or approved reporting mechanism (ARM). Taken together, this reduces the efficacy of transaction reporting, says our managing director Ian Rennie.

    Reporting eligibility

    The trials of applying the concept of “traded on a trading venue” (TOTV) are well documented. Although ESMA’s opinion (issued on 17 May 2017) sought to establish a clear meaning of TOTV, concerns persist. There are still teething problems with the infant Derivatives Service Bureau (DSB) service particularly with the interaction of the DSB’s instrument normalisation and the reporting requirements.

    Aside from TOTV there are problems with applying the reportability criteria to transactions involving indices. Identifying accurately which indices contain MiFID instruments is problematic. One obvious example is Boeing which is dual listed as LON: BOE and NYSE: BA. There is, however, no regulatory requirement on index providers to make public the constituents of any index, which are dynamic in nature; moving in and out on a regular basis.  As a result, smaller firms may find it prohibitive to source the appropriate and relevant data to identify reportable index derivatives.

    Incorrect fields being reported and risk of detection

    There have also been instances of inaccurate or superfluous fields being reported. The commodity indicator flag is being populated on non-commodity instruments. Similarly, instrument fields are being populated unnecessarily when the transaction in question is reported with a valid Financial Instruments Reference Data System (FIRDs) International Securities Identification Number (ISIN). Volatile attributes were a late addition to the reporting obligations and overall the industry is still looking to implement this change.

    The UK Financial Conduct Authority (FCA)’s investment in its Market Data Processor (MDP) platform has been significant and gives the regulator a greater capacity to detect circumstances where two parties to a transaction have reported divergent values for the same transaction. This is particularly the case in instances where transactions are traded on a venue and now, as mandated, firms must persist the trading venue ID for the transaction. The FCA can use that ID to pair transactions and then match fields to highlight any discrepancies, which it can then automatically fire out to both firms.

    Obtaining data from competent authorities and ARMs

    Regulatory Technical Standard 22, Article 15, obliges firms to reconcile and test between their internal systems and data provided by competent authorities. Failing the provision of the data by the relevant national competent authority (NCA), firms should use data from their ARM or, as a last resort, use the transaction reports submitted by the firm to their NCA.

    The FCA appears to be a frontrunner, through its MDP system, in providing data back to the firms it regulates. Commitment by other NCAs to provide back to firms their data is not clear and should be closely monitored. That said, the current FCA extract service is not fit-for-purpose; even where firms obtain FCA data through the MDP portal they are unable to reconcile back safely to their own source systems.

    As mentioned above, RTS 22, article 15 points firms to obtain data extracts from their ARMs if not available from the competent authorities. Approved reporting mechanisms have had teething problems as well in their ability to provide data back to firms. In some instances, firms have been limited by the number of transactions they can obtain and there have been problems with the methods available for the data transfer. All ARMs have made significant progress in the area, which is most welcome.

    Efficacy of reporting and communication from the NCAs

    The primary objective of MiFID II reporting is to aid NCAs in the detection of market abuse. Any issues that prevent the correct application of the reporting criteria, reporting inaccuracies or unneeded fields or roadblocks facing firms’ efforts to conduct assurance activities, therefore, will reduce the efficacy of the reporting regime, as will inappropriate requirements.

    One simple example that illustrates this is the reporting of pricing of equity swaps when compared with contracts for difference (CFDs). For equity swaps ESMA’s guidelines require the financing charge to be reported — a piece of information that appears wholly irrelevant to market abuse — while for CFDs, which are economically the same instrument, the price of the underlying is reported.

    In summary, both firms and the regulator still need to do plenty of work to get MiFID II reporting into shape. This is likely to be a long and difficult road.

    Our ReportShield™ quality assurance service gives financial firms peace of mind in the accuracy, completeness and overall quality of MiFID II reporting data. If you would like an assessment of the quality of your MiFID reporting six months in, please contact us.

    A variation of this article was published by Thomson Reuters Accelus, a subscription-only site, on 12 July 2018.

  • MiFID II Q&A update: New guidance on complex trades and national ID validations

    We are five full months into MiFID II. Competent Authorities are still experiencing teething issues with the instrument data, validations, response messages and providing reporting firms with extracts of their submitted reports. Firms are increasingly moving their focus from addressing validation issues and handling of response files to looking at the accuracy of their reporting. All parties should be working on the most pressing issues following the 80/20 rule.

    “Firms are increasingly moving their focus from addressing validation issues and handling of response files to looking at the accuracy of their reporting.”

    Working on validations to get all the transaction reports accepted by the regulator may not be the most pressing issue.  Firms can still be reporting 100% of their records inaccurately. It is therefore important that attention is turned away from validations to accuracy testing and identifying the valid but wrong population.

    Whilst there are many areas of reporting uncertainty, ESMA has decided to focus its guidance on strategy trades. Strategy trades are relatively rare in the reporting world and affect only a very small proportion of total reportable activity. 

    This post summarises the new guidance from ESMA.

    Complex Trade ID

    A strategy trade is a trade which is composed of more than one financial instrument or legs, where the execution of the trades are contingent on each other and a single price is given for the strategy contract as a whole. 

    When transaction reporting strategy trades, the Complex Trade ID (field 40), must be populated with a code that links each of the legs. This code must be unique to each strategy trade for the reporting firm. ESMA’s latest update to its Transaction Reporting Q&A on Friday (25 May) provides more guidance on how and when the Complex Trade ID should be populated. 

    The aim of the Complex Trade ID is to notify the users of the transaction report that the instrument reported is part of a broader strategy trade and to enable the user to identify any related transactions.  In the guidance they make it clear that:

    • The price reported is the price of the strategy as a whole not the price of the individual leg being reported.
    • The Trading Venue Transaction Identification Code (TVTIC) should be populated for each reported leg of the strategy. Presumably, this would only apply where the strategy itself was executed on a trading venue and the legs execute as part of that strategy. There is more complexity here and more scenarios which the Q&A does not address.  
    • The Complex Trade ID field must be populated even where only one leg of the strategy trade is reportable. It is still a strategy trade and the price must reflect this.
    • Where the strategy itself is allocated an ISIN you still report the individual legs and not the strategy as a whole.
    • In terms of reference data to be reported for strategy trades, the Q&A makes clear that the reference data for the legs must be submitted, not the reference data for a “strategy instrument”.

    National ID validations

    The only other update in the Q&A relates to the validations published for the national identifiers. We have commented in a previous post as to the complexity the approach gives rise to. This is the second update to these validations that have been published.  The latest is:

    • Czech Republic: “It should be noted that the special character “/” is just a separator and should be omitted in transaction reports.”

    Presumably there have been problems with firms including “/” in their identifiers.

    Kaizen’s accuracy testing checks all MiFID II data fields to ensure your reporting is correct. To find out more about how we can help you avoid the ‘valid but wrong’ problem, please get in touch. 

  • In the news:  Dario Crispini on post-2008 world and how MiFID has altered the landscape

    In the news: Dario Crispini on post-2008 world and how MiFID has altered the landscape

    Kaizen’s CEO Dario Crispini spoke to Best Execution’s Lynn Strongin-Dodds about MiFID a decade on.

    At the time MiFID was introduced Dario was the head of the then FSA’s Transaction Monitoring Unit and managed the regulator’s transition to MiFID reporting including introducing the approach to fines for incorrect transaction reporting. 

    Here’s an exert from the article:

    Long before the financial crisis wreaked havoc on stock markets and investment banks, MiFID I was being hatched in the hallowed halls of the European Commission. It was officially launched in 2007 with the aim to shake up the status quo in the equities landscape. However, as events the following year proved, much more work was needed to be done to corral the worst of the excesses and improve transparency.

    The dispersion of liquidity has been another major challenge. “The removal of the concentration rules under MiFID I was a good thing, in terms of competition, but one of the unintended consequences was the fragmentation of the liquidity,” says Dario Crispini, founder and CEO at Kaizen Reporting and former manager of the transaction monitoring unit of the Financial Service Authority between 2001 and 2010. “As the market evolved, this led to more complex trading strategies and high frequency traders and algorithmic trading which caused distortions.”

    You can read the full article here. 


  • Media release: Kaizen and Elixirr partner to bring new level of transaction reporting compliance

    Media release: Kaizen and Elixirr partner to bring new level of transaction reporting compliance

    Kaizen and Elixirr, the challenger consultancy, have announced a new partnership, which will deliver a complete end-to-end regulatory reporting remediation service for financial institutions. We will collaboratively offer clients greatly-improved assurance testing, governance and support on their trade and transaction reporting remediation projects.

    This is a significant milestone in responding to the increasing levels and complexity of regulation faced by the industry. Kaizen is unique in its approach to compliance assurance, checking every single item of transaction data for accuracy and completeness, while Elixirr provides practical and hands on support to resolve the reporting issues highlighted by the Kaizen assurance assessment.

    Data quality has been a continual problem under the original MiFID reporting regime[1] but the increased complexity of EMIR and MiFID II reporting obligations means that this will be even harder to achieve. At the same time, regulators’ capacity to identify issues has widened, and the UK’s Senior Managers’ Regime puts additional pressure on individual managers within firms to ensure they are reporting correctly.

    Firms which do not fully address reporting issues are at risk of multi-million pound fines, reputational damage, and the cost of internally remediating the problem, which is often significant. In an industry first, Kaizen’s technology solution, combined with Elixirr’s remediation skills, will identify reporting issues quickly and ensure they are resolved and replayed, in a cost-effective, seamless way. 

    Barry Lewis, Partner at Elixirr who led the formation of the partnership, says “Kaizen have developed a service that is invaluable to the financial services industry, so we’re delighted to partner with them in such a value-added offering. This partnership means we can combine robust data quality assurance tools with the analysis and remediation expertise of our team, and help our joint clients respond even more effectively to the increasing needs for reporting compliance.”

    Dario Crispini, Kaizen CEO , says, “I see the partnership as an important step forward in compliance evolution. By combining the skillset and expertise of the two companies we are able to provide clients with greatly enhanced confidence and accuracy when reporting to regulators. Elixirr has a strong reputation, attention to detail and unwavering passion to really help firms succeed and we trust them to provide the best remediation solutions for the companies we work with. The market is already responding well, and I have full confidence that this partnership will quickly benefit our clients and go from strength to strength in the months and years to come.”

    Recently awarded the Queen’s Award for Enterprise in innovation, one of the UK’s highest business accolades, Kaizen has combined data science with leading regulatory expertise to develop ReportShieldTM, a quality assurance service that provides firms with a complete set of controls to ensure the accuracy, timeliness and completeness of their reporting data.  ReportShield tests all of a firm’s records, avoiding the shortcomings of other approaches which test only small data samples.

    Elixirr has a proven track record of working with financial services firms internationally to help them identify issues and achieve full and sustainable reporting compliance.

    -ENDS-

    For media inquiries, please contact Fiona Wilde, Head of Communications and Marketing on 07834 731 602 or media@kaizenreporting.com.

    [1] Kaizen’s analysis of transaction reporting fines issued by the FCA found that 65% of transactions were incorrect, and that firms were unaware of these inaccuracies. See our infographic here. 

  • In the news: Dario Crispini talks LEIs with Funds Europe

    In the news: Dario Crispini talks LEIs with Funds Europe

    Our CEO Dario Crispini spoke to Nicholas Pratt at Funds Europe about some of the challenges of the introduction of Legal Entity Identifiers (LEIs) which are an important component of MiFID II.

    Extract: 

    Each fund managed in Europe has to have a registered LEI and the ESMA has imposed a ‘no LEI, no trade’ rule to underline the importance of the initiative.

    Currently there are 1.1 million LEIs in issue. However, many people think that’s some way off the desired total.

    “I would expect there needs to be a lot more LEIs registered to cover the market,” says Dario Crispini, chief executive of Kaizen Reporting, who has previously worked for the Financial Conduct Authority in the UK.

    Read the full story here. 

  • Listen: Ian Rennie speaks on MiFID II and Senior Managers Regime

    Listen: Ian Rennie speaks on MiFID II and Senior Managers Regime

    Ian Rennie spoke at City & Financial’s Implementation of the Extension of The Senior Managers and Certification Regime conference. He spoke about the new Senior Managers Regime (SMR) requirements under MiFID II, where that fits into the regulatory landscape and the steps that can be taken to be compliant with MiFID II and SMR. 

    Have a listen below.


  • ESMA’s LEI solution is a Grandma-like gift

    ESMA’s LEI solution is a Grandma-like gift

    Thank you Santa, you have delivered the first wish on our Christmas list –  a solution for firms with clients without LEIs!

    Well…kind of.  ESMA has blinked first but late in its long standing game of Chicken with the industry and today announced it has relaxed its approach on the LEI requirements for reporting entities and issuer of financial instruments.  There was very little wriggle room for ESMA as it has no powers to amend the regulation and instead has had to relax one of the validations and pass on significant operational difficulties to firms and trading venues.

    ESMA recognises industry concerns

    In its statement, ESMA recognises three key concerns of the industry. First, that firms will not succeed in getting LEIs for all of their clients prior to 3 January 2018. At the same time, it acknowledges that these clients will still approach firms to trade with them post 3 January regardless of not having an LEI.  Finally, trading venues will face similar problems with non-EU issuers who will not have obtained LEI.  There is a fourth issue of handling corporate actions for clients without LEIs.  These are issues that Kaizen reflected previously in our blogs and publications and ESMA has now been persuaded by the consequences of the LEI obligations. In short, the LEI mandate would result in a scenario where clients without an LEI have no option but to trade with a US located bank or venue resulting in a material outflow of business from the EU financial system.

    A Christmas gift but not for life…

    ESMA’s proposal is a temporary but messy solution so as not to breach the regulations. For a period of six  months from 3 January, investment firms and trading venues can continue to provide trading services to clients without an LEI that would trigger a transaction reporting obligation. But only if two obligations are met:

    • The investment firm obtains the necessary documentation from the client to apply for an LEI on the client’s behalf
    • The trading venue reports its own LEI instead of the  LEI code of non-EU issuers whilst reaching out to them to get one

    Investment firms will have to apply immediately for the issuance of an LEI on behalf of the client and then submit all required reports for that client once the LEI has been issued.  ESMA and the NCAs accept that this solution will cause a delay in reports being made and they will actively monitor the timeliness of late reports.  At the same time, they will amend their validation rules to allow the acceptance of transaction reports where LEI issuance date is after the transaction reporting execution date.  But the FCA have already communicated that they will not be able to make this change for the 3rd January!

    ESMA and your Grandma

    Like Christmas presents from your Grandma, ESMA’s LEI ‘present’ is well meaning but does not quite hit the spot.  Worse of all, it doesn’t come with a receipt that will allow you to exchange for a better gift. The effect upon firms is a messy one:

    • Outreach: Firms will have to, at short notice, reach out to clients to obtain the required data to register them for an LEI and what happens if the client doesn’t want to play?
    • Register and pay for LEIs: Put in place a process at short notice to process LEI requests
    • First Mover Disadvantage: Those firms who respond first will end up paying for LEIs that then also benefit their competitors
    • LEI Duplication: Although the GLIEF system is meant to prevent duplication of LEI issuance, it will likely face its greatest test as multiple firms apply on behalf of clients
    • Excluding Reports: Firms will have to put in place processes to identify and exclude transactions without LEIs and then report once the LEIs issued
    • NCAs not ready: The FCA have already said they will not be able to make the validation changes in time, meaning that they will reject reports even if they follow process outlined by ESMA
    • ARMs and firms not ready: ARM validations and for some firms their own internal validation processes will have to be altered to allow the historic reports to be submitted with newly minted LEIs.

    So –  not quite the present we all wished for and we may well be left scratching our heads in January wondering how to put it together and make it work.  Fingers crossed we have better luck on our other nine items on our Christmas wish list…

  • MiFID II Q&A updates – an early Christmas present from ESMA

    MiFID II Q&A updates – an early Christmas present from ESMA

    ESMA has, this week, published updates to three of their Q&As on MiFID II which you need to be aware of for your MiFID II programmes as we approach go-live. 

    For transaction reporting, the latest update reiterates how you determine reportability for some specific instruments.  We believe that key amongst these is ESMA’s confirmation that units in collective undertakings and ETFs need only be assessed on the instrument itself and not on their underlying holdings. This point has been outstanding since the original data reporting consultation paper. 

    There are also other updates to Q&As including transparency topics and Market structure topics.

  • Dear Santa…a MiFID II Christmas wish list

    Dear Santa…a MiFID II Christmas wish list

    Dear Santa

    I have been very good this year. I planned my MiFID II transaction reporting project early. I read Levels 1, 2 & 3 (well maybe not all of level 3…). I put enough money in the budget, identified my risks and spoke to my peers.  In short I think I have done everything possible but I still think I might be in a little bit of trouble. So this year for Christmas I have one or two wishes that I hope you can grant so I can start the new year with a cheery grin as big as yours.

    Could you and Ruldolph please drop into my stocking this year:

    1. An LEI for all my clients who are refusing to get one even though I have offered to help many times in doing so.  I do want to keep talking to them next year!
    2. Help trading venues send the fields they need to for me to make my report.
    3. May my ARM be able to onward report to the FCA without any issues.
    4. A bright and sparkling new reconciliation that reconciles all my trades and not just the ones I sent
    5. Change ESMA’s mind and let them agree that the FIRDs list is a golden source of data
    6. Please just make ‘shortselling’ either go away or send me a new magical toy that will calculate it every day and correct it even  after I need to include a trade that was not captured the previous day
    7. Some really clever testing that identifies any of my mistakes so I can tell my Senior Manager Regime (SMR) manager all is well and he/she won’t lose their house
    8. Make all corporate actions involuntary even though they aren’t (our secret, Santa)
    9. Now I have lots of friends from different countries and I would like just one way of identifying them not several.
    10. An Xbox with the latest version of Overwatch

    Now Santa I hope you don’t think me too greedy, but compared to my friends in America and Hong Kong I think I might be in more need for Christmas presents than them.

    I’ll leave a mince pie for you and some carrots for Rudolph . Even if you can send me a few of the items I have asked for, I will be happy and I promise I’ll ask a lot less for next year.

    Love from…
    Little Johnny

    P.S If you can’t do 4 and 7 then please drop this letter over to those lovely people at Kaizen Reporting, I am sure they will be able to help!

  • In the news: Kaizen speaks to CNBC about what to expect from MiFID II

    In the news: Kaizen speaks to CNBC about what to expect from MiFID II

    Kaizen’s Managing Director Ian Rennie was live on CNBC this morning where he gave a rundown of what to expect from MiFID II when it goes live in just a few weeks.

    Watch the interview here. 

  • Media release: Kaizen announces an excellent 2017, with new clients, offices and award wins

    Media release: Kaizen announces an excellent 2017, with new clients, offices and award wins

    For immediate release – Thursday 14 December 2017

    Kaizen Reporting, the leading provider of regulatory reporting quality assurance, has had another very successful year. Strong demand for Kaizen’s automated testing services has seen it double its client base and number of employees, which necessitated a move to new offices. Kaizen has also extended its services to cover more G20 jurisdictions and regulations including EMIR 2.0 and the upcoming MiFID II. Kaizen was recognised for its pioneering approach to quality assurance with the Queen’s Award for Enterprise, one of the UK’s highest business accolades.

    Dario Crispini, Kaizen CEO, says, “2017 has been a fantastic year for Kaizen and I think we will look back on this year as our ‘breakthrough’ year. Demand for our services has really taken off.  Our revenues have grown by nearly 150% and we have signed a large number of new clients including four tier 1 banks and several of the world’s biggest asset managers, hedge funds and brokers; we also made some significant new hires. 2018 is looking to be just as successful with new services, partnerships and growth already in the pipeline.”

    As well as winning the Queen’s Award earlier this year, Kaizen’s flagship ReportShield™ service also won Best Compliance and Regulatory Solution at October’s Fund Services Awards.

    Crispini added, “The awards we’ve received have been the icing on the cake this year and we see them as further acknowledgement of the impact our services are having on the industry.  Regulatory reporting is getting more complex and challenging for firms, but we take that burden away from our clients and give them confidence in their reporting.”

    ReportShield™ provides firms with an automated set of controls that give full transparency of reportable data, detecting even minor errors. This gives financial firms the ability to identify and manage their regulatory reporting risks, building real confidence in their reporting – and most importantly, avoiding regulatory censure. 

    Dario continues, “Looking ahead to 2018, the MiFID II pain will continue and we expect firms to turn their attention to the deployment of appropriate controls for MiFID II. At the same time EMIR and DFA reporting quality, resulting in remediation of reporting issues, will become more important, along with the challenges of SFTR implementation and the impact of the Senior Manager’s Regime on reporting.”

    ***ends***

    For media inquiries, please contact Fiona Wilde, Head of Communications and Marketing on 07834 731 602 or media@kaizenreporting.com

  • Listen now: Webinar – Senior Managers Regime responsibilities under MiFID II

    Listen now: Webinar – Senior Managers Regime responsibilities under MiFID II

    UPDATED Monday 18 December

    The Senior Managers Regime (SMR) requires a named person in each financial firm to demonstrate that they are complying with their regulatory obligations.  Listen here for our webinar which looked at the SMR in the context of the upcoming MiFID II reporting obligations which go live on 3 January 2018. 

    Kaizen’s Dario Crispini and Ian Rennie joined UK Finance Capital Markets Director Robert Driver to outline what firms should be doing to inform and protect senior managers to demonstrate effective controls under MiFID II.

    Key topics in the webinar included: 

    1. What are some of the key questions that could be asked of you by your senior executive who is responsible for transaction reporting under the SMR
    2. Where MiFIR fits into the regulatory landscape and what it is attempting to achieve
    3. The consequences of poor data quality and what controls you need to put in place to be compliant with Article 15 of RTS 22.
    4. Current industry reporting issues regarding MiFIR
    5. Steps you can take now to ensure compliance with MiFID II and the SMR.

    Date: Wednesday 13 December 2017
    Time: 3pm (GMT) for one hour

    Listen here

    Kaizen’s award-winning quality assurance service ReportShield™ gives you everything you need to be compliant with transaction reporting requirements under MiFID II.  Find out more about our testing and controls. 

  • Q – Who should read the latest MiFIR Q&A?

    Q – Who should read the latest MiFIR Q&A?

    A – Those involved in: portfolio management outsourcing, IPOs, corporate actions and trading of swaps which contain an index.

    ESMA has published its latest version of its Questions and Answers on MiFIR with updates exclusively on the topic of firms’ transaction reporting obligations under MiFIR article 26 and ESMA RTS 22. There are four questions raised, each marked with the update date of 14 November 2017.  Here we briefly explore the key points of each question and answer.

    Q7: How should transactions be transaction reported where portfolio management has been outsourced? (page 33)

    ESMA provides a new detailed scenario and answer to the question in the form of diagrams, example reports and narrative explanation. In this scenario, where firm (B) is outsourcing the portfolio management to another firm (Z), who is making the investment decisions on behalf of firm (B), ESMA confirms that firm B needs to report the algo or person who is primarily responsible for the decision to delegate.

    Q8: What are the reporting obligations for a primary issuance?

    ESMA has confirmed that all members of a syndicate need to report all execution legs by the ‘coordinating bank’ (CB) and the ‘billing and delivery bank(s) (B&D).  A CB is defined as a bank that will buy from the issuer/seller and sell to another bank or banks in the syndicate. A B&D bank will then sell to the clients, noting that a CB can also act as a BD. In relation to the time that needs to be reported, this should be the date time at which the pricing and the allocations are finalised between issuer and the syndicate, normally the first listing. ESMA has provided worked out examples for other fields.

    Q9: When are corporate events reportable?

    The industry is going to have to pick through the answers to question 9. ESMA reiterates that corporate actions are reportable where the investor has an opportunity to make an investment decision. It then goes on to recognise in practice that many corporate actions are as a result of mandatory events that bring them within the exclusions under 2(5)(i) of Article 26. This still leaves an element of interpretation on behalf of firms to identify these exclusions.  There is clear guidance on corporate events resulting from a default option and where an investor has given standing instruction.  For both categories a report is required.

    ESMA also confirms that it is the transaction resulting from the event that should be reported and provides a worked example. There are other points to review but in short and at first glance, this guidance reiterates that firms will need to put in place measures to identify reportable corporate actions.

    Q10: Are both legs of a swap reportable, when one leg contains an index such as LIBOR or EURIBOR?

    I think the answer simply says ‘look at example 106 in section 5:35.7.1’ but uses many more words than that to say this!

    The main purpose of this blog was to draw your attention to the latest Q&A and to highlight some of the key points. In terms of readiness for 3 January, I think the most significant impact will be the reporting of corporate actions and firms’ ability and capacity to separate those that are reportable from those that are not.

  • FCA to focus on reporting data quality in 2018

    FCA to focus on reporting data quality in 2018

    The Kaizen team’s previous visit to The Royal Garden Hotel in Kensington was just a few weeks ago when we picked up the Best Compliance & Regulatory Solution award at the Fund Services Awards.  We found ourselves at the hotel again at City & Financial’s one-day conference last week to get a flavour of how ready the industry is for the go-live of MiFID II in the new year. Kaizen’s Ian Rennie is pictured and spoke about how Senior Managers can ensure they’re compliant with MiFID II under the Senior Manager’s Regime. 

    All eyes on reporting data

    The keynote address came from the Financial Conduct Authority’s (FCA) Ana Fernandes and she made one thing very clear: The FCA expects firms to be ready come January 3rd 2018.  Excuses about the complexity of the new regime will be no use to anybody, especially given the amount of time firms have had to prepare for it, she said.  Ana also made the point that a firm’s reporting requirement does not simply end after successful data submission. Constant monitoring is expected post-reporting and any corrections that need to be made should be done quickly. There is going to be a lot of eyes on this data and firms will be called out on anything that looks suspicious.

    LEIs are a key focus for regulator

    Ana went on to explain that one third of the fields in MiFID II are related to counterparty information and that this is a key area that the FCA is focusing on. They want to know exactly whose investments will have a negative knock-on effect in the market.  Of course with this, the mandate of the LEI is justified in the eyes of the regulator.  If firms are still disputing this decision at this stage and have not looked into the deeper complexities of the regulation, they have a lot to be worried about.

    Data quality must be good at source

    The comments on the importance of LEIs were echoed by the next speaker, Francis Gross, Senior Advisor at the Directorate of General Statistics at the European Central Bank. His main focus was on increased harmonisation and standardisation of data and believes that in order to identify market abuse before it is too late, data quality must be good at the source.  He compared financial services data unfavourably to that of retail, saying, “if shops had same data quality as financial services then shop shelves would be bare and there would be queues in the street’.  The reality is that there is no time to cleanse it at the regulators’ end given the quantity of data they receive every day.  

    It’s all about data accuracy

    My take home point of the whole conference was that gone are the days where firms only need to worry about under or over reporting of data.  2018 will bring a shift of focus to the accuracy and completeness of data reported.  Both EMIR RTS 2.0 and MiFID II bring more rigid definitions of data that needs to be reported and firms need to have controls in place to prove they are reporting correctly and completely, something Kaizen is helping its clients with as they prepare for MiFID II.  

    Please contact us if you would like to discuss any points raised in this blog or discuss your preparations for MiFID II transaction reporting.  

  • CFTC Fines Top Tier Bank for Legal Entity Identifier (LEI) violations

    CFTC Fines Top Tier Bank for Legal Entity Identifier (LEI) violations

    It sounds like MiFID II’s mantra of ‘No LEI, No Trade’ has travelled across the Atlantic and resonated with the CFTC. 

    Last week it was announced that a tier one bank has been fined $US 550,000 for failing to update its counterparty LEI information.  Whilst the CFTC’s regulation is not as strict as its European cousin’s, it does expect that LEI information is provided when it becomes available. 

    Although it’s not one of the largest fines they have ever issued it does give us a new insight to the sort of checks they are performing.

    Specifically, the CFTC’s investigation found that a design flaw in the bank’s architecture failed to update the regulator when an LEI became available for a counterparty and all other aspects of the contract remained the same.  Full details of the penalty can be found on the CFTC website. 

    On first thought it may sound like updating the counterparty identifier is a simple change to implement but dig a little deeper and you can see how it is an easy pitfall to find yourself in.   A small firm that does not have an LEI will not be the reporting party when they are facing a tier one bank.  Realistically, they will be paying little or no attention to their derivatives reporting and have little incentive to notify the bank when they acquire an LEI.  The bank could easily have hundreds of similar small firm clients and tens of thousands of transactions to report each day.  Unless a dedicated process exists to check for an updated LEI, it is a simple thing to miss, especially when none of the economics of the contract change.

    Is your counterparty LEI information being reported correctly? Kaizen’s ReportShield™ accuracy testing and reference data testing identifies all counterparty errors so they can be remedied quickly and easily.  Please get in touch to discuss your LEI or MiFID II reporting challenges.

  • Transparency is still an issue 10 years post financial crisis

    Transparency is still an issue 10 years post financial crisis

    “If these things were so large, how come everyone missed them?”
    The Queen – 5 November 2008

    It’s ten years this month since the financial crisis began and we’re reminded that it was Her Majesty The Queen who spoke for the nation when she asked why it had taken so many financial experts by surprise.

    Her Majesty asked the question at a visit to the London School of Economics a few months after the collapse of Lehman Brothers.  The reply?  “At every stage, someone was relying on somebody else and everyone thought they were doing the right thing.”

    Could it happen again?

    August 9 2007 is largely known for being ‘the day the world changed’ when BNP Paribas froze three of their funds, indicating they had no way of valuing the assets inside them.  The run on British bank Northern Rock began a month later.  One year later in September 2008, Lehman Brothers filed for bankruptcy, prompting worldwide panic.

    Now, ten years on, could it happen again?  Have efforts to prevent another financial crash been successful?  The Governor of the Bank of England Mark Carney thinks so.  Last month he said that the things that caused the last financial crisis had been fixed.  Carney believes that the reforms agreed by the G20 have created a safer, simpler and fairer financial system.  

    Part of this reform agenda was a substantial increase in reporting requirements which are meant to bring greater transparency and allow regulators to be able to spot the build-up of systemic risk.  But persistent data quality issues continue to thwart making good on this objective.

    Data quality is the big issue

    Why?  The regulations that have arisen out of the ashes of the financial crisis including EMIR, Dodd Frank Act and the soon to be live MiFID II are meant to put in place reporting regimes that give regulators all the information they need to identify the build-up of systemic risk and detect market abuse.  The idea being that if there is to be a next time, regulators can’t stand behind the reason that they had limited visibility.  However, the increase in breadth and depth of information required has led to a corresponding and manifest increase in complexity which has led in turn to a decrease in data quality – which, if left undetected, can have serious and dire consequences for firms and regulators alike.

    We’ve highlighted before the problems that banks are having with their regulatory reporting quality – the very reason Kaizen is kept in business!  Last year the FCA found 65,000 data quality breaches in a week when testing only four of the MiFID transaction reportable fields.  Our own analysis has found at least 65% of transactions are being reported incorrectly with firms completely unaware of the inaccuracies of their data.  And this is in a mature regime which is comparatively simple compared to MiFID II, EMIR and DFA. 

    Stuck between a rock and a hard place

    If regulators, having asked for a substantial increase in reported data, are then unable to identify the build up of systemic risk, this will ring hollow in the corridors of power of the G20 governments.  Under this pressure regulators will have increasingly low tolerance with firms who persist with reports that have significant data quality issues.  

    For the industry to be able to add ‘improved transparency’ to Carney’s list of positive changes since the financial crash, there needs to be a sustained and comprehensive improvement in the quality of the data that firms report to regulators.

    Regulators cannot afford to allow data quality issues to persist.  They will take the necessary actions and we can expect increased censure and fines to follow as required.

    What next?

    In this context and environment it is critical for firms to be able to identify and quantify data quality issues in their reporting, which is exactly what Kaizen does for our clients and how we explained what we do to the Queen in our recent conversation with her at Buckingham Palace!  

    In all seriousness, please contact us if you have concerns about the quality of your regulatory reporting or would like confirmation of its accuracy and completeness.  We are here to help. 

  • MiFID II guidelines update uneventful

    MiFID II guidelines update uneventful

    There is very little of note in ESMA’s update to its MiFID II guidelines on transaction reporting announced on Tuesday 8 August.  Most of the changes are to reflect the current references for regulations and a few corrections of CFI codes used in the examples. 

    Of note are the following:

    • Execution within the firm field

    Where an investment firm is instructed on where to execute a trade, the client is instructing the execution.  The original text stated you populated the “Execution within the firm field” with “Client”.  This has now been changed to “NORE” which we think means “No reference”. 

    (See 5.12: Block 5: Execution within the firm field)

    • Reporting as DEA provider

    A more significant update, is in respect of DEA trading where you are the DEA provider.  Previously, the guidelines indicated that the execution within the firm field should be populated with an Algo identifier for the order management system that routed the order to the trading venue.  This has now been changed to “NORE”. 

    (See 5.25: Direct Electronic Access (DEA)

    • Read ESMA’s full notice
    • Download the new guidelines
    • Download a tracked changes version of the new guidelines.
  • Transaction reporting tops concerns at MiFID II conference

    Transaction reporting was chief amongst concerns at today’s UK Finance MiFID II implementation conference, where Stephen Hanks from the FCA was keynote speaker.

    At one of the first conferences since the BBA merged with other financial trade associations, Stephen Hanks spoke widely on the expected MiFID II implementation issues, focusing on four main areas of interest:

    • The publication and content of the FCA policy document published 3 July
    • Recent European Commission and ESMA activity
    • Transaction reporting issues
    • Some shared thoughts on how the FCA intends to act over next six months.

    Policy document is technical not guidance

    The publication of the 1000-page policy document had been accompanied by a loud sigh of relief within the FCA but left financial journalists scratching their heads on where to start! Stephen explained that documentation’s primary purpose should be seen as a technical exercise of translating EU legislation, of both the MiFID and non-MiFID variety, into the FCA handbook. There is no significant inclusion of guidance in the document as the FCA wishes to deliver this through their participation in ESMA’s efforts.

    That said, Chapter 2 of the handbook outlines where the FCA is adding additional requirements over and above the EU legislation. The four main areas outlined by Stephen were:

    • Policy and taping of corporate financials and discretionary managers
    • Divergence with ESMA over the appropriate test
    • Research
    • Client classification.

    FCA to provide clarity on issues before 3 January 2018

    On the topic of the appropriate test, Stephen explained that the FCA has decided to ignore ESMA; a decision not taken lightly. Rather it is a decision taken based on the specific prevalence of UCITs and Investment trusts in the UK compared to the rest of Europe  and as such, the FCA will continue to follow to advice previously provided by ESMA’s predecessor, CESR in 2010.

    Over the coming months the FCA, with the European Commission (EC) and ESMA will be focusing on a number of issues to try and provide required clarity before go live on 3rd January 2018. On both share and derivative equivalence, expect further consultation between NCAs, ESMA, EC and the industry and subsequent publications of Q&As. . The topic of commodity limits is taking up considerable time and effort at the FCA with a focus on arriving at the appropriate level of limits. The FCA is placing reliance of ESMA guidelines on how entities should determine trading venue status but are taking  wide and varied soundings from UK firms on whether they should be treated as a trading venue  or a brokerage model.

    FCA has significantly enhanced ability to detect data issues

    Stephen made special reference to transaction reporting highlighting that Zen’s replacement Market Data Processor (MDP) went live with industry testing on the 3rd July with ARMs, to be followed swiftly with APAs and trading venues. He described transaction reporting as a “particular challenge” and recognised that there will “be serious challenges” but made it clear that the “FCA wanted to work with the industry”. That said he explained that MDP will have in-built business testing, similar to that run by Kaizen, to detect data quality issues. In short the FCA ability and capacity to identify data quality issues will be significantly enhanced with the introduction of functionality provided by MDP.

    During the 200 days left to go for MiFID II go-live the message from the FCA was to take all reasonable steps to comply with the obligations, that the FCA recognised the material increase in complexity that MiFID II brings and that these two points will shape the supervisory environment in 2018. If firms do have significant or expect to have significant issues they should be flagged to the regulator as soon as possible and before go-live.

  • MiFID II: Industry pushes back on ‘no LEI: no trade, no admission’

    MiFID II: Industry pushes back on ‘no LEI: no trade, no admission’

    Kaizen’s CEO Dario Crispini and Managing Director Ian Rennie spoke with Thomson Reuters Accelus about efforts by the financial services industry to persuade ESMA to soften its approach on the use of LEIs under MiFID II. 

    Firms are disputing two issues – the ‘no LEI, no trade’ rule spelled out in RTS 22 (which mandates the use of LEIs for corporate and other counterparties) and ‘no LEI, no admission’ rule in RTS 23. Firms are looking for leeway from ESMA to allow the use of other identifiers, at least initially. 

    On the ‘no LEI, no trade’ rule, without an LEI, the transaction report will fail the validation test and be rejected by the ARM or national competent authority. 

    “The validation means that if there is a corporate entity as counterparty or a decision maker on a trade, if they don’t have a LEI, then the firm can’t report the trade. There will be circumstances where someone does a trade and then they find out they don’t have a LEI. What do they then do? It’s not possible to get the report to the regulator with the wrong identifier. It makes sense to try to move away from that strict validation. That will require quite a bit of movement from ESMA,” Dario told Regulatory Intelligence. 

    “My understanding is all firms are trying to meet the requirement and deal with the rump of their counterparties and issuers as they go live. Everyone is geared up for ‘no LEI, no trade’ but are, at the same time, explaining the potential unintended consequences to their competent authorities,” said Ian.

    The full article is available from Thomson Reuters Accelus, a subscription-only site.


  • Webinar: Do you have the right systems and controls in place?

    Webinar: Do you have the right systems and controls in place?

    Join us and our partner UnaVista for a webinar: MiFIR – the right systems and controls

    Date: Wednesday 28 June 2017
    Time: 10am (EDT) 3pm (GMT) 4pm (CEST)

    Kaizen’s Founder Dario Crispini was the head of the FCA’s Transaction Monitoring Unit when MiFID I was introduced.  

    On this webinar, Dario will discuss lessons learned from control failings under MiFID I, the consequences of not getting the control environment right, and the new requirements for systems and controls under MiFIR.  

    Dario will also outline the latest comments by the regulator on MiFiR, a taste of which can be found in our latest blog. 

    The webinar is part of a series on MiFIR run by our partner UnaVista, who will outline key tools and capabilities such as accuracy testing, reference data, reconciliations, validations, management information, workflow and exception management etc that firms need to consider ahead of MiFIR.

    Register here

    Kaizen’s award-winning quality assurance service ReportShield™ gives you everything you need to be compliant with transaction reporting requirements under MiFIR.  Find out more about our testing and controls. 

  • Top ten takeaways from the BBA’s transaction reporting forum

    Top ten takeaways from the BBA’s transaction reporting forum

    The head of the FCA’s Transaction Monitoring Unit, Ana Fernandes, gave a clear indication of the FCA’s position on MiFID II reporting at the BBA’s Transaction Reporting Forum this morning. 

    Here are our top ten takeaways from the event:

    1.  “The devil is in the detail” – Ana acknowledged the tension between being prescriptive with detailed rules vs providing general principles for firms to adhere to. 
    2. “MiFID II is an enhanced regime,” not a new regime.  The FCA and the industry are leveraging 20 years or more of transaction reporting experience. Our take on that is expectations for good quality data will be higher than for a new reporting regime.
    3. MDP applications need to be submitted as soon as possible.  The FCA isn’t seeing “as much traction as expected”.  If you delay too much, don’t expect the FCA to turn it around and they won’t differentiate between the types of entities onboarding whether it is ARMs, trading venues or directly submitting firms.
    4. The FCA is ready to commence industry testing on 3rd July but not all reference data will be available due to dependencies on FIRDS.  Any test cases firms are planning will therefore need to take this into consideration.
    5. The FCA is still not seeing many queries from firms and they would expect more.
    6. Traded on a Trading Venue (TOTV) didn’t get much attention other than to say that the FCA expects the scope will apply to a small proportion of instruments once the trading obligation for derivatives is in force.  We will be publishing a blog shortly with our views on TOTV.
    7. New Q&As are being finalised by ESMA covering amongst other things:
      • Increases and decreases in notional
      • Reference data
      • Corporate actions
      • ISINs.
    8. The FCA will be conducting business validations as well as technical validations.  The technical validations have been published but she did give some indication that the business validations will cover quality tests including matching between reports across firms and other data such as order book data and trade reports.  The FCA expects firms to do the same as part of their data quality efforts.
    9. Where issues are identified, notifications to the FCA should take place in the same manner as today. 
    10. Leniency – on prompting from the floor regarding leniency in the early days post go-live, Ana stated that the FCA will consider each case on its merits. 

    It is clear the importance of effective data quality tools especially reconciliations is paramount in the mind of the regulator.  Ana was clear the FCA expects firms to have reconciliations in place at go-live.  Kaizen will be offering cross-entity reconciliations where there’s agreement between parties to help firms meet this requirement.  Do get in touch if you’d like to discuss this or any of your MiFID II reporting requirements further. 

  • Kaizen Reporting’s ReportShield™ testing wins Queen’s Award for innovation!

    Kaizen Reporting’s ReportShield™ testing wins Queen’s Award for innovation!

    Regulatory technology firm, Kaizen Reporting is delighted to announce that it has won a Queen’s Award for Enterprise, the highest accolade in UK business.

    Kaizen’s award comes in the innovation category for the prestigious business awards which are announced today by the Business Secretary Greg Clark.

    Kaizen won the award for its ReportShield quality assurance service which tests 100% of regulatory reports. This is in contrast to traditional methods which only test small data samples.  The in-depth testing gives Kaizen’s clients full sight of any errors within their reporting data so they can be corrected.

    Changing the way reporting is done

    Kaizen CEO and Founder, Dario Crispini, said, “Winning a Queen’s Award for innovation is a huge honour and recognition of the way Kaizen’s ReportShield testing is changing the way reporting is delivered throughout the industry.”

    Regulatory trade and transaction reporting has become absolutely vital since the financial crisis in 2007. Regulators rely on regulatory reporting to detect insider dealing, rogue trading and the build-up of systemic risk (one of the primary causes of the crisis).

    However regulatory reporting is becoming increasingly complex and financial firms have struggled to get it right.  This has resulted, in some cases, in regulatory fines running into millions of pounds and costly bills to retrospectively fix the errors.

    Improving the quality of regulatory reporting

    In response to this, Dario, a former regulator, and Ian Rennie, industry expert, set up Kaizen Reporting in 2013 to help improve the quality of firms’ regulatory reporting.   

    By combining their regulatory knowledge with data science, Kaizen developed ReportShield, an automated testing service that fully assesses the quality of regulatory reporting data.

    Dario continues, “Incorrect regulatory reporting is a major industry problem that Kaizen wants to help solve. ReportShield is helping both sides of the industry – firms can be confident of their reporting integrity and avoid fines, and the regulator receives good quality transaction reports, ensuring market transparency.”

    Dario added, “I’d like to personally thank the Kaizen team for their dedication and expertise in developing ReportShield, and also our clients and partners for their support over the past three years.” 

    Winners of the Queen’s Award are invited to attend a reception at Buckingham Palace later in the year.

    ends

    About the Queen’s Awards

    Established in 1965, the Queen’s Awards for Enterprise are for outstanding achievement by UK businesses in the categories of innovation, international trade and sustainable development. Awards for innovation are given to businesses that can demonstrate that their innovative products or services are commercially successful.

    For media inquiries, please contact Fiona Wilde, Head of Communications and Marketing on 07834 731 602 or fiona.wilde@kaizenreporting.com.

  • Workshop: MiFID II Guidelines and common scenarios 2

    Workshop: MiFID II Guidelines and common scenarios 2

    Our MiFID II trading scenarios workshop is back following a sold-out course at the BBA in February. 

    Delivered by our CEO, former regulator Dario Crispini and Senior Advisor Ian Rennie, this one-day course explores the challenges that the final transaction reporting guidance and its corresponding scenarios present. Building upon the learning from our Understanding your Obligations workshop, this one-day workshop will delve into the detail of the reporting guidance and how this applies in various scenarios to ensure the highest level of compliance with MiFID II obligations.

    There will be an opportunity for delegates to submit their own reporting scenarios beforehand to work through on the day, as well as covering off some of the most common scenarios.

    Kaizen’s CEO Dario Crispini, says, “ESMA has made it clear that it expects the quality of MiFID II/MIFIR reporting to be high from go-live in January 2018.  It is essential that investment firms understand the guidelines and factor their direction into the design, build and control of their transaction reporting solution”.

    This workshop is open only to financial regulated firms.

    Date: 8 May 2017
    Venue: British Banker’s Association,Pinners Hall, 105-108 Old Broad Street, London, EC2N1EX

    Find out more/book here.

  • Q: Which ‘reporting crocodile’ will be nearest the canoe in 2017?

    Q: Which ‘reporting crocodile’ will be nearest the canoe in 2017?

    A: MiFID II, and it’s only 358 days away…

    In our last blog we looked back on the reporting events and challenges that shaped 2016 through the hits of Bowie; but as we begin 2017 we find ourselves asking, ‘where are we now?’ (last Bowie reference…promise!). In short, there are many reporting regimes that are contenders to win the accolade of the ‘reporting crocodile’ nearest the canoe for UK firms in 2017. However, the characteristics and specific demands that MiFID II requires of firms, establishes it as the most demanding and challenging regulatory reporting ask of 2017. The clock is ticking and as at the time of writing, we have 358 days until go-live!

    The other crocodiles circling the canoe

    For those of you who came back into the office to deal with the aftermath of your firm’s Bank of Israel Reporting go live, 3 January 2018 may seem a long way off. Equally if you are responding to the CFTC review of your DFA reporting through the NFA and their 4s letters or an official examination by them, again MiFID II seems a distant problem to contend with. Worse still, your firm may be facing regulatory censure on longstanding commitments such as MiFID I or, as we are seeing increasingly, fines from the CFTC in relation to accuracy of reports under the DFA regime. Then there is pressure from ESMA and competent authorities to improve the quality of EMIR reports. In addition to the EMIR Review and MiFID II, European firms need to contend with consultations on SFTR.  For those who have US and HK obligations there are the new SEC and HKMA obligations due throughout the first three quarters of the year.

    These ‘crocodiles’ are not just circling but hitting the canoe at the same time and of course, you cannot pick and choose which ones to deal with; all need to be grappled with. But what makes MiFID II stand out as the crocodile you need to deal with most?

    What are the characteristics of MiFID II that require special attention?

    In a nutshell – in many respects, MiFID II confers materially different obligations on firms and runs a much greater risk of regulatory censure following go-live compared to other G20 reporting obligations. There are three characteristics which mark out MiFID II for special attention:

    First, the sheer number of fields, many different from what has been asked of before. E.g. Trader ID, algo ID, short-selling field, pre-trade waivers, and precise execution time to the millisecond and beyond!

    Second, MiFID II builds upon an existing regime where competent authorities, most notably the FCA, have developed expertise in detecting data quality issues and have a regime in place to issue sanctions. Ana Fernandes of the FCA made it clear at the recent FCA TMU Transaction Reporting Forum, that expectations will remain high and the ability of the TMU to detect errors will be improved come 3 January 2018.

    Third, the sheer complexity of the MiFIR requirements dwarfs that of competing regimes. Whether it is determining what transactions need to be reported, what business events need to be excluded, notwithstanding ‘no LEI no trade’, the short-selling calculation, or how to put in place the mandated regulatory controls, the level of complexity is materially different than what has been expected before.

    Next, we explore some of these complexities and discuss what firms need to be doing now to ensure successful delivery this time next year.

    Your MiFID II to do list

    It’s the New Year and what better time to draft your ‘MiFID II Transaction Reporting to do list’?  Better still, we’ve done it for you…

    1. Reporting Solution – Build or Buy?

    Key to meeting the complex obligations of MiFID II is putting in place the appropriate reporting solution.  There is no fixed answer on whether to buy or build as it depends completely on your firm’s size, previous investment in meeting reporting obligations, and expected reporting volumes.

    At one end of the spectrum there are the large tier 1 banks who have been investing heavily in their reporting solutions over the last six years. In this case, it is most likely that there will be an extension of recent builds to cater for MiFID II requirements. A word of warning, IT architects and IT leads that expect a similar build to EMIR should think again, see below for examples of why.

    At the other end of the spectrum, are firms who have previously had little or no reporting obligations who are only now looking to make the decision on whether to build or buy. On balance, due to the complexity involved and time remaining, buying a solution and adapting it to your needs is probably the least risky option and you should choose a provider with a track record of providing reporting solutions that are ready to roll off the production line.

    2. Determine what trades are reportable, based upon instrument being traded

    At first glance it appears straightforward how to determine what instruments needs to be reported. Firms will be able to rely, to a certain degree, on the list that ESMA is mandated to provide under RTS 23. But even here there are significant implementation and operational issues with this list. For example, if it is not produced or there are issues with it then firms still have the obligation to report correctly, irrespective of the provision of the list.

    It become more complicated when you have to identify instruments which reference those traded or admitted to trading on trading venues.  How will firms identify and report the below examples?

    • Third country futures that reference instruments admitted or requested for trading on trading venue (RM, MTF or OTF)
    • OTC derivatives and 3rd country ETDs that reference instruments admitted or requested for trading on trading venue (RM, MTF or OTF)
    • How to identify, at the time of trade, the index constituents.

    Due to these inherent problems; determining which instruments are reportable becomes a materially more complex proposition compared to MiFID I, EMIR and DFA. Firms need to be working now with their counterparts, vendors and participate in discussions with their Trade Associations to put in place workable solutions.

    3. Establish what activity requires reporting

    Having figured out what instruments need reporting firms need to turn their attention to determining what activity is reportable. In short, take a look at RTS 22, Article 2 and the 14 different sets of activities that need to be excluded. The fact that many of these business activity exclusions have not been seen in EMIR, demonstrates again the material difference in the type of reporting solution required for MiFID II compared to previous reporting regimes. Firms will have to look at their trade data and ensure their reporting solutions are able to identify activity that should be excluded, as MiFIR does not allow for over-reporting.

    4. No LEI – No Trade

    Both the FCA and ESMA in recent public meetings have reiterated the point that firms must not trade with entities that do not have a LEI. This has been reiterated in the first MiFID II Q&A published by ESMA. There is considerable work for client onboarding teams and relationship managers to reach out to clients without LEIs and ensure compliance by 3 January 2018. Good luck!

    5. Short-sell calculation

    We will not discuss here the merits or otherwise of the short-selling requirement for transaction reporting (ok well, a little passing reference…suffice to say the value of this field is a best questionable.) Transactions in cash equities and government securities will require a calculation to identify transactions that take the firm short at any given point. Making an accurate calculation that takes into account late trade bookings and busts will be problematic and firms should not underestimate the time and cost that will be needed to ensure compliance.

    6. Under RTS 22, Article 15, ESMA high priests did say upon to firms, ‘thou shall test and reconcile one’s transaction reports….’

    Ok, maybe not as dramatically as that but ESMA now makes the obligation to test and reconcile mandatory under MiFIR. The important point to note is that controls are often the first casualty of delivery, as go-live approaches. For MiFID II this is not an option; firms need to ensure effective testing and reconciliations are in place at go-live. Failure to do so will be a breach. Looking to third party providers who have mutualised the costs of testing and reconciliations may make sense to ensure comprehensive and effective controls are in place prior to go live in 358 days time.

    There are many more items to add to the MiFID II Transaction Reporting to-do list.  Of course in the current environment there is no choice between which regimes you implement. That said, the complexity and the introduction of new demands on firms by MiFID II means it should be treated as the largest crocodile nearest the canoe when firms are planning their 2017 regulatory reporting delivery.

  • Workshop: MiFID II Guidelines and Common Scenarios

    Workshop: MiFID II Guidelines and Common Scenarios

    FULLY BOOKED.

    We’ve joined forces with the BBA again to deliver a new training workshop, this time focused on MiFiD II training scenarios.

    This workshop will explore the challenges that the final transaction reporting guidance and its corresponding scenarios present. Building upon the learning from the Understanding your Obligations workshop, this one-day training session will delve into the detail of the reporting guidance and how this applies in various scenarios to ensure the highest level of compliance with MiFID II obligations.

    There will be an opportunity for delegates to submit their own reporting scenarios beforehand to work through on the day, as well as covering off some of the most common scenarios.

    ESMA has made it clear that it expects the quality of MiFID II/MIFIR reporting to be high from go-live in January 2018.  It is essential that investment firms understand the guidelines and factor their direction into the design, build and control of their transaction reporting solution.

    This workshop is open only to financial regulated firms.

    Date: 2nd February 2017
    Venue: London Institute of Banking & Finance, 8th Floor, Peninsular House, 36 Monument Street, London, EC3R8LI

    Book and find out more.


  • 2016: The reporting (Jean) Genie is well and truly out of the bottle

    2016: The reporting (Jean) Genie is well and truly out of the bottle

    David Bowie was many things to many people but a transaction reporting aficionado he was not. That said, in the year that saw the great man leave on his own “Space Oddity“, we use some of his most loved hits and lyrics to help us look back at reporting in 2016 …. and only hope he is not looking down to see us take such a liberty! David, we’re truly sorry…

    The reporting “Labyrinth” – new obligations

    Every year since the 2009 G20 Pittsburgh summit, which gave birth to the G20 reporting commitments, the industry has had to plan for and comply with new regulatory reporting obligations across the globe and 2016 has not been any different. Added to the “Labyrinth” of existing regulatory obligations, we have seen Canadian G20 reporting go live in July, the introduction of branch reporting in Hong Kong, and closer to home we have seen changes to EMIR reporting brought about by the introduction of clearing obligations. To cap the year off, firms will need their own “Heroes” working during the holiday season to make sure they can go live with Bank of Israel reporting on 1 January 2017!

    “Ch-ch-ch-ch changes”

    In regulatory reporting that has only recently gone live, 2016 has seen “Changes” or consultations on changes to their obligations. In accordance with Article 85(1) EMIR, the European Commission launched a review of the legislation on 21 May 2015 and published its final report on 23 November 2016.  As a result, the Commission has committed to a legislative review of EMIR in 2017 which will include an attempt to streamline trade reporting requirements.  In the US, we have seen no action relief expirations for CFTC DFA (Dodd Frank Act) reporting and the advent of SEC reporting drawing closer. The election of Donald Trump aligned with a Republican majority in the US Congress could mean substantial changes with the repeal of certain sections of the DFA in 2017 a distinct possibility.

    “Ashes to Ashes” for MiFID I transaction reporting

    As transaction reporting under MiFID I enters its final year, throughout 2016 firms have found themselves “Under Pressure”, trying to prepare for the much more demanding and complex ask of MiFID II.  Both buy side and sell side firms have been grappling with their understanding of the obligations imposed by MiFIR Article 26, the supporting RTS 22 and final guidelines.  The final guidelines document published in October represents a substantial investment by ESMA and the competent authorities.  Ana Fernandes of the FCA’s Transaction Monitoring Unit stood in public and compared the physical size of TRUP to the MiFIR guidelines. Her conclusion –  they have invested significant time and effort in the drafting of the regulations and supporting guidelines and their expectations of the standard of reporting is higher than that of  regimes that have recently gone live.  Throughout 2016 firms have been busy digesting what is required of them to comply with MiFIR transaction reporting obligations, realising it is significantly more complex than either EMIR or DFA.  In short, the significant increase in complexity of MiFIR reporting combined with the greater scrutiny of regulators means MiFIR could prove all-consuming for firms in 2017.

    Data Quality? Everything is not “Hunky Dory”

    As the year ended, the industry received messages both from the FCA and ESMA about the quality of the data that is being reported to them. Ana Fernandes and Olga Petrenko both struck the same chord at last month’s Transaction Reporting Conference at the BBA when they called out the poor quality of data still being reported.  Ana outlined that reporting under MiFID I, now live for nine years, still has significant errors – something that we highlighted when we analysed transaction reporting fines earlier this year.  Olga explained that ESMA is still receiving complaints from other bodies such as central banks about the quality of the data they are receiving from the reports made under EMIR.  Consequently, ESMA will have the improvement of data quality as its primary objective of 2017.  Both bodies are investing heavily to develop the capacity to identify data quality issues where they will increasingly compare reports, use independent sources of data, and introducing ‘business’ validations to identify errors and hold firms accountable in meeting their obligations.

    If these years are to be the “Golden Years” of reporting and less a “labyrinth” of competing demands, then the industry needs to invest heavily in accurate advice and appropriate solutions throughout 2017 so the quality of the data they report meets the increasing expectations of the regulators.

    There’s a lot to do as we head into 2017 but to soften the blow perhaps have a listen to Bowie over the festive season.

    Thank you for your support in 2016 and we wish you a restful break with your friends and family.

    Seasons greetings from us all at Kaizen.

  • Camels are horses: the problem of identifiers under MiFID II

    Camels are horses: the problem of identifiers under MiFID II

    This article was first published by Thomson Reuters Accelus (a subscription only service) on 21 November 2016. 

    We seem to be surrounded by questions of identity these days; a problem that was recognised and typified by the story of Theseus’s ship by the early Greeks. When Theseus and his young crew returned to Athens from Crete they did so in a ship with 30 oars. The ship was preserved by the Athenians down the ages by renewing the timbers as they decayed. Is this renewed ship, where none of the original timbers actually made the journey from Crete, still Theseus’s ship or has it become something different?

    Today we face this question of identity in a slightly different form in terms of nationality. Whether we are European or British, British or Scottish, and what determines nationality in any case. The topic “Mistaken identities” is the title of this year’s Reith Lectures by Professor Kwame Anthony Appiah. In his lectures, he looks at what gives people their national identity, a question firms will be faced with when trying to categorise their clients.

    In the regulatory sphere as well, questions of identity appear in several forms.  The Know Your Client (KYC) and Politically Exposed Persons (PEP) mean firms need to know that the person they are looking to deal with is who they say they are.  In reporting, firms need to identify who we are trading with; both individuals and companies. We also have to identify the traders within the firms themselves, and we need a way to identify the products being traded.

    This piece will focus on the question of nationality and the use of identifiers for individuals and companies under MiFID II and some of the challenges that this will bring. We will deal with identifiers for instruments at another time.

    MiFID II transaction reporting requirements seek to provide regulators with greater visibility of who is trading and who is making the investment decisions. This contrasts with MiFID where financial firms can often be identified with a global identifier (BIC or FRN codes) whilst other companies, partnerships and individuals are identified at a firm level using each firm’s internal identifiers. The lack of global identifiers makes it much more difficult for regulators to see what is going on across the market.

    Identifying individuals under MiFID II

    Under MiFID II ESMA has opted to use a suite of identifiers for individuals where the identifier to be used is to be based on the individual’s nationality. To my mind, it is unfortunate that they took a fragmented approach because it introduces an additional problem of what type of identifier to use, making reporting much harder. I presume this was a 28-country committee decision. As they say, a camel is a horse designed by committee!

    The requirements for identifying individuals are specified in the Regulatory Technical Standards (RTS) 22 and a table of the required identifiers by nationality is illustrated in annex II of the RTS. The annex tells you which identifier should be used for each nationality. The table in annex II tells you what to use once you know the nationality of your client or trader.

    Six of the countries opted to use the CONCAT approach as their only identifier. Other countries have elected to use national identifiers, passport numbers or tax numbers.

    What is CONCAT?

    As the name suggests CONCAT is a method to generate an identifier for individuals based on the compression or concatenation of four data elements:

    1. Country code (2 characters: ISO 3166-1)
    2. First name (first 5 characters padded with # where required)
    3. Surname (first 5 characters padded with # where required)
    4. Date of birth (YYYY-MM-DD)

    The CONCAT is comprised of these elements in the order shown.

    There is an argument that the four elements lack an important feature of an identifier, that of uniqueness. The cost of clashes, where two individuals are allocated the same CONCAT code, will be dependent on the frequency with which clashes occur.

    The process doesn’t end there. Before creating the CONCAT, the names need to be subject to a transliteration process to convert them into a common Latin alphabet by removing punctuation marks: apostrophes, hyphens, accents, and umlauts. Titles should also be removed as well as prefixes such as “Van” or “De” or “De la”. I am sure there will be questions where individuals treat the prefixes as part of a single surname: or example, where Delarue is used by the individual rather than De La Rue.

    What is the client’s nationality?

    “Firms must ask both new and existing clients whether they have multiple nationalities and to notify their firm if they acquire or lose a nationality.”

    Returning to the philosophical and social question of identity and nationhood: what is your client’s nationality? Rather than getting everyone embroiled in conjectures, ESMA has happily provided a waterfall approach to be used where individuals have multiple nationalities:

    1. For EEA countries use the first country ISO country code when it is sorted alphabetically
    2. Where there are EEA and non-EEA countries, the EEA countries take precedence.
    3. Non-EEA countries use the first country ISO country code when it is sorted alphabetically

    That means firms must ask both new and existing clients whether they have multiple nationalities and to notify their firm if they acquire or lose a nationality.

    Even then, we need to know each client’s list of nationalities which might not be so easy to determine. In my case, which I am sure is not unusual, I was born in Guernsey but have Italian and Irish parents which may complicate things. I am living in the UK but I have never been through any citizenship process. So in all honesty, I’m not sure what my nationality is.

    If I am a UK national, I would be identified using my national insurance number according to the table in RTS 22. But is it so simple?  I think I may have been registered as an Italian citizen and allocated a codice fiscal or Italian tax code.  So perhaps I would be classified as Italian, but I also used to have an Irish passport and I now travel on a Guernsey passport. So what nationalities do I have? I  have been told that anyone who has Irish parentage is eligible for an Irish passport. The problem is I am not actually sure what nationalities I have. As a client completing a form where I am requested to state all my nationalities I would have to do a significant amount of research just to determine how to fill in the form.

    To help address this, it might be an idea to provide industry guidance for the public on how to determine your nationality. ESMA has not, however, provided any guidance regarding what constitutes nationality for transaction reporting purposes. Does citizenship, tax residence, domicile, place of birth, a passport, all qualify? We need to know the answer to be able to arrive at the appropriate identifier to put in the transaction report.

    So taking my example, and assuming I am a national of the respective countries, you would get a table along the lines of something like this:

    Nationality

    Country code (ISO 3166)

    Identifier to use per annex II RTS 22

    Priority

    Basis

    British

    GB

    National Insurance number

    1

    First EU country alphabetically based on country code

    Guernsey

    GY

    Passport

    4

    Not an EU state.  EU states take precedence.

    Irish

    IE

    CONCAT

    2

    Second EU country alphabetically based on country code

    Italian

    IT

    Codice fiscale

    3

    Third EU country alphabetically based on country code


    In a post-Brexit world, the identifier to be used would change because the UK would switch from being an EU state to a non-EU state. Whilst my nationalities haven’t changed, the status of the UK has.  Reapplying the logic to compute the appropriate identifier to use would produce the following:

    Post-Brexit implications
    If there are any EU nationalities, they take precedence over non-EU nationalities. The first EU nationality of the country code when sorted alphabetically is used in that scenario. In this case it would be GB.  Looking at the table in RTS 22 annex II then shows that the UK requires a national insurance number, as its primary identifier.

    Nationality

    Country code (ISO 3166)

    Identifier to use per annex II RTS 22

    Priority

    (post Brexit)

    Basis

    British

    GB

    National Insurance number

    3

    Not an EU state.  EU states take precedence.

    Guernsey

    GY

    Passport

    4

    Not an EU state.  EU states take precedence.

    Irish

    IE

    CONCAT

    1

    First EU country alphabetically based on country code

    Italian

    IT

    Codice fiscale

    2

    Second EU country alphabetically based on country code


    The table above shows that this is not going to be a simple process. It however, will go beyond just clients.

    Beyond clients

    Within the MiFID II transaction report there are a number of fields which may require an individual to be identified. Not all of these will be clients.

    Field no.

    Field name

    Type of individual

    7

    Buyer identification code

    Client

    12

    Buyer decision maker code

    Client or representative

    16

    Seller identification code

    Client

    21

    Seller decision maker code

    Client or representative

    57

    Investment decision within firm

    Trader

    59

    Execution within firm

    Trader


    Where there is some sort of power of representation in place, that party will also need to be allocated an identifier using the same process if they are to place trades on behalf of the account. Traders within the firm are also caught.

    Identifying businesses under MiFID II

    A much simpler identifier is in place for businesses. MiFID II requires all parties operating a business to be identified with a Legal Entity Identifier (“LEI” code). I say “operating a business” and not “companies” because any party eligible for an LEI under the LEI allocation rules must be identified with an LEI. Under these rules an individual operating a business as a sole trade or as a local is eligible for an LEI.

    “The regulations require firms to have an LEI in their possession before entering into a trade with a client or counterparty or on behalf of their client.”

    No LEI no trade

    This gives rise to the ‘no LEI, no trade’ rule. At present, the regulations require firms to have an LEI in their possession before entering into a trade with a client or counterparty or on behalf of their client. This can be extended to the decision maker fields for representatives under a mandate or power of attorney.

    A legal firm operating for an account will need to register for an LEI. Registration can be made on behalf of a third party or client where they give authority and the information needed to do so. Costs are currently around £100 per LEI and £55 for renewals – required after two years depending on the number of LEIs being registered.

    LEI status

    There are several statuses that an LEI can have. Reporting firms must use an “active” LEI in the executing entity field which are: “Issued”, “Pending transfer” or “Pending archival”. For clients and representatives, they must have registered for an LEI which can be one of the following statuses: “Issued”, “Lapsed”, “Pending transfer” or “Pending archival”.

    Branches

    Branches should be identified with the LEI of their head office, certainly until such time that the proposed branch level LEIs are issued.

    What should firms be doing now?

    Firstly, firms need to test their existing client and counterparty static data (including representatives) to check they have correctly captured LEIs that are already in issue. Then they need to conduct a reach-out exercise encouraging them to obtain an LEI. If you have a lot of clients, you may not want to shoulder the cost of registering an LEI for them. This however could be deemed to be an inducement and may be considered contrary to the inducement rules set out in MiFID II so firms should tread carefully.

    For individuals, a reach-out exercise is needed to collate nationalities and associated identifiers, then the appropriate identifier needs to be determined.

    Mapping client and counterparty accounts to the LEI dataset is a complex activity. At Kaizen, we have been working on LEIs for more than two years, developing solutions that address the challenges associated with mapping identifiers for both individuals and businesses. The LEI dataset itself is not without its problems as it uses multiple alphabets and contains duplicate records and entities with common legal names within its dataset. Building this assessment capability in-house will be an expensive and time-consuming exercise. In addition, this will need to be carried out on a recurring basis as new LEIs are being registered daily.

    As with all regulations, the philosophical and the practical collide, leaving firms with the challenge of accommodating the two.

     
  • The good, the bad and the new: Final MiFID II transaction reporting guidelines

    The good, the bad and the new: Final MiFID II transaction reporting guidelines

    It was a big day in the world of regulatory reporting on Monday (10 October) with the publication of what is expected to be the final version of ESMA Guidelines for MiFID II transaction reporting.

    These guidelines are very important because they establish an obligation on financial market participants who “shall make every effort to comply with those guidelines and recommendations.”[ref]Article 16(3)of Regulation (EU) no 1095/2010 of the European Parliament and of the Council[/ref] Failure to comply with the guidelines will be considered a breach of the transaction reporting requirements.

    The guidelines are extensive so we’ve carried out an initial review of the 280-odd pages and a quick comparison to the previous version focusing on the transaction reporting requirements.

    Our take? Well, the good news is that ESMA has answered a lot of questions. The not-so-good news is that many questions still remain unanswered.  The bad news is that the guidelines have thrown up some new questions.

    Here are our immediate observations (there will be more to come once we’ve had more time to plough through and analyse all the changes).

    Identifying natural persons

    There have been some changes to identifiers for individuals which we think will be welcomed by the industry:

    1. Person identifiers: no longer requires firms to monitor for the expiry of identification documents such as passports.
    2. Clarification of how to determine nationality of individuals with multiple non EEA nationalities is by the first country code when sorted alphabetically.
    3. Introduction of an exhaustive list of name prefixes where these are to be removed when constructing the CONCAT identifier.
    4. Name and surname fields are now to allow the original country spelling so transliteration is not required for these fields.

    Who is the decision maker?

    This is the key question that competent authorities need to answer when undertaking surveillance for market abuse. As such, this is key information in the transaction report and ESMA has provided further clarifications and examples in the scenarios for the various decision maker fields including reporting chains which will prove very useful when mapping out the reporting logic.

    Reporting trades against fund managers has been clarified

    ESMA clarifies that they are looking for the decision maker. Therefore, where there is a transaction on the instruction of the fund manager, the fund manager will be the buyer and the decision maker field is left blank as it is one and the same party.

    Where execution is determined outside of the reporting firm then the “execution within firm” field should be populated with “CLIENT”. Similarly, where executions are filled by an order management system then this should be identified with an Algo identifier.

    Venue identifier

    The original guidance and RTS 22 indicated that all trading that was not directly on venue activity would be reported as XOFF. Unfortunately, the latest guidance suggests a move back to the MiFID I approach where the venue MIC code must be used when a trade is executed under the rules of a venue.

    “The buying and selling interest of two parties is not brought together by the Trading Venue either on a discretionary or non-discretionary basis, but the transaction is nonetheless subject to the rules of that Trading Venue and is executed in compliance with those rules.”

    ESMA confusingly goes on to say,

    “Where an Investment Firm is not the direct market facing entity the Investment Firm is not regarded as executing on the Trading Venue for the purposes of transaction reporting.”

    This seems to contradict the prior statement. The examples provided, however, do make clear that where the parties to a transaction agree that it is executed under the rules of an exchange or trading venue then the venue field should be populated with the MIC code of that exchange or trading venue.

    Short-selling flag

    Only real change here is that aggregated client orders do not require a short-selling flag to be populated as it relates to multiple clients. Transaction reports that show individual client-side activity will need to be populated based on the each client’s overall position in the traded security.

    ESMA has also clarified in the examples that the short-selling flag is only required for uncovered short sales of shares and sovereign debt instruments per articles 12, 13 and 17 of the short selling regulations.

    Cancellation of transaction reports

    ESMA has clarified that only the “key” fields 1, 2, 4 and 6 are to be submitted in the cancellation report. Inclusion of additional field information will result in a rejection of the cancellation report.

    Identification of the underlying instrument

    Surprisingly, ESMA has asked that where there is a derivative on a derivative (an option on a future on an equity, for example) the direct underlying should be identified i.e. the future rather than the equity.

    This raises the question of reportability. Are they suggesting that underlying refers to only one level down and when assessing reportability, there is no longer a look through to the ultimate underlying? For example, an option on an ADR on BT shares would not be reportable because the look through only goes down one level to the ADR? While when assessing the ADR you would look through one level to find BT shares and conclude the ADR itself is reportable? In the case where the immediate underlying is a future on a third country exchange that doesn’t use ISIN to identify its products means that the underlier field cannot be populated again – does this suggest that ESMA now considers such instruments as not reportable?

    Equity swaps and instruments reported with two separate transactions reports

    There has been an amendment to the approach ESMA wants to see for instruments which have multiple legs such as equity swaps. ESMA has compressed the two legs of an equity swap into a single transaction report using + and – to flag the buyer and seller of the legs. Previously in the consultation paper ESMA expected two transaction reports which were to be linked using the complex trade ID field.

    Similarly, for equity swaps the ISIN code for each equity leg is included in underlying instrument field with a + for the buyer (receives the performance) and – for the seller (on the equity leg that where they pay the performance).

    Similarly, where a benchmark is exchanged for equity performance the benchmark is identified in the “Underlying index name” field with a + or -.

    Other things of note:

    • Transfers are further defined in the text.
    • Changes in ownership structure are reportable.
    • Units of funds are not financial instruments and therefore not reportable.
    • Transactions for the creation and redemption of funds are only excluded where they are directly with the fund administrator. This was in the prior version of the guidance but it is now much clearer.
    • Identifying buyer or seller for trusts has been amended to be consistent with the approach taken for firms.

    What’s not addressed
    Outsourcing – do you need to be an ARM?

    There is an open question being debated by lots of different interested parties. The suggestion by ESMA had been that where a firm uses a central reporting hub to generate the transaction reports for all the reporting entities in its group that firm would have to register as an Approved Reporting Mechanism or ARM. Similarly, parties that stood between the reporting firm and the ARM providing reporting services would also be required to become an ARM.

    The guidelines clarify that

    “No requirement for a receiving firm to become an ARM. There was request for confirmation that a receiving firm reporting details transmitted by a transmitting firm did not need to become an ARM. ESMA confirms that that is not an outsourcing arrangement as the receiving firm is making its own report and it is not required to become an ARM. A statement on this has been included in the relevant section of the Guidelines.”

    From this it does imply that any form of outsourcing type arrangement involving your transaction reporting activity may require the supplier of the service seeks ARM status. This is not black and white and my suspicion is that this issue is still under discussion behind the closed doors at ESMA. What they have been able to do is rule out a scenario for receiving firms in the reporting chain to be ARMs.

    My view is that extension of the ARM regime beyond entities seeking to submit transaction reports directly to a competent authority on behalf of third parties will be unworkable.

    To conclude

    The above is by no means an exhaustive list – as always, the devil will be in the detail. Firms should be looking to see if their request for additional scenarios (as requested in the consultation paper) has been appropriately addressed.

    Do share with us here at Kaizen your initial reaction to the guidelines and anything further you’ve discovered so far. As mentioned, we will post a more thorough analysis once we’ve had more time to digest.

    Happy reading!

  • FCA provides timeline for MiFID II testing services

    FCA provides timeline for MiFID II testing services

    The FCA has published details of how interested parties can register to connect to their MiFID II data submission service and has also announced that they will provide testing facilities six months ahead of MiFID II go-live.

    The Market Data Processor (MDP) service replaces the current transaction reporting system Zen and will be operated and supported by a third party, Sopra Steria. The MDP also provides the mechanism for other Data Reporting Service Providers (ARMs, APAs and CTPs), trading venues and systematic internalisers to submit the instrument reference data required under RTS 23 and trade data required by ESMA to calculate the double volume cap as per RTS 3.

    Some parties such as our partner UnaVista are developing services to support MiFID II including an instrument static submission service so parties won’t have to register and pay the connection and annual fees to use the MDP service directly. In addition to a substantial cost saving, it has the benefit of validating the data before submitting it to the FCA.

    The MDP service specifications will be available to registering parties from the end of September and from Q4 for commodity position reports. A test environment will be available from 1 July 2017 allowing connecting entities and those further down the chain a good deal of time to undertake comprehensive testing prior to the MiFID II go-live date of 3 January 2018.

    Sopra Steria will also be managing the data extract service. This is the mechanism by which samples of submitted transaction reports can obtained for testing the veracity and completeness of the submissions. This process is expected to be conducted by all reporting firms as part the controls required to comply with RTS 22 Article 15 paragraph 3.

    Useful link: MiFID II Regulatory Technical Standards.

  • Kaizen and BBA MiFID II webinar and workshops

    Kaizen and BBA MiFID II webinar and workshops

    Updated 10 October 2016

    We’re delighted to have joined forces with the BBA to support firms with their transaction reporting preparations for MiFIR/MiFID II.

    Despite the post-Brexit uncertainty, the FCA has made it clear that when it comes to MiFID II, firms should not take their foot off the pedal. With only 15 months away from go-live, we’ve developed a webinar and series of workshops to help those involved in implementing these complex new reporting requirements.

    Webinar: MiFID II in the new political and economic landscape

    11.00am, Thursday 29 September 2016

    Please join Kaizen’s CEO Dario Crispini and Senior Advisor Ian Rennie, BBA Policy Director Robert Driver, and Credit Suisse’s Matthew Vincent as they cover:

    • What to expect next from the regulator
    • Where should you be with your preparations, planning and delivery of MiFID II transaction reporting
    • Key industry concerns such as regime cutover, instrument reference data, short selling and LEIs
    • The steps you can take now to get on the front foot with MiFID II reporting
    • Your questions and answers on transaction reporting under MiFID II.
    SOLD OUT Workshop: Transaction Reporting under MiFID II – Understanding your obligations

    9am-5pm Monday 10 October 2016
    Find out more and register

    This workshop led by Ian Rennie and Dario Crispini will delve into the detail of the obligations to give participants a clear understanding of all the changes and requirements, including:

    • Reporting scope – what is in, what is out
    • Entities subject to the reporting obligation
    • Likely impact on portfolio managers
    • Key challenges and risk reporting firms will face
    • Key changes your organisation will have to make for transaction reporting.

    We are planning further workshops in the near future.

    If you have any questions about the webinar or training sessions, please contact Philip Allen, Director of Learning at the BBA on 0207 216 8843 or philip.allen@bba.org.uk


  • FCA publishes second MiFID II consultation paper

    FCA publishes second MiFID II consultation paper

    The FCA has published its second consultation paper (CP 16/19) on the implementation of MiFID II.

    This consultation paper covers a range of issues including position limits and reporting for commodity derivatives, systems and controls requirements for firms providing MiFID investment services and client asset protections.

    The FCA’s CEO Andrew Bailey, reiterated the importance of firms continuing on with their MiFID II preparations despite the outcome of the EU referendum.

    “MiFID II contains important measures to enhance investor protection and bolster financial stability. It reflects recent themes of UK conduct regulation, such as improved controls on the manufacturing and distribution of financial products, and it implements the international commitments the UK entered into to reform derivatives markets following the financial crisis. As we said in our statement following the EU referendum, firms must continue to abide by their obligations under UK law, including those derived from EU law and continue with implementation plans for legislation that is still to come into effect,” he said in a statement.

    The FCA published its first consultation paper on MiFID II on 15 December 2015 (CP15/43) and there will be a further consultation paper later this year.

    The closing date for responses to consultation paper CP16/19 is 28 October 2016.

    MiFID II comes into effect on 3 January 2018.

  • Will Brexit lead to a TRexit?

    Will Brexit lead to a TRexit?

    I spent some time last weekend catching up on the arguments for and against a Brexit. It got me thinking about the implications for reporting for firms in the UK. Now that the UK has voted to leave, will it have a major impact reporting-wise? Will obligations significantly reduce? I’ve come to the conclusion that in the main, I think Brexit will have very little impact on regulatory reporting. Here’s why:

    A transparent market is the ultimate aim

    Having seen the regulatory process and the development of transaction reporting legislation from inside the (then) FSA, my thinking is this: the UK needs clean markets to attract capital. To that end, the FCA has been at the forefront in establishing the transaction reporting regime in Europe as well as its shape under MiFID II. Clean capital markets will be even more important to the UK under a Brexit scenario so I fully expect that the UK would maintain a near identical transaction reporting regime. This could even include negotiating the ongoing exchange of transaction reports with our European neighbours under the existing MiFID model assuming that MiFID II is not adopted in full as a member of the EEA.

    Passporting

    Where an impact is more likely is for firms passporting into Europe today and they will be anxious about the future of their licence. Dependent on the outcome of negotiations on transaction reporting exchange, passported firms may have to report to their local competent authority (as today under MiFID I) and may lose the benefits of centralised reporting set out under MiFID II.

    Similarly, incoming branches to the UK may end up with a double reporting obligation to the UK and to their home competent authority. This would be more of a challenge were reporting obligations to differ between the UK and Europe but if they remain harmonised it reduces to a routing rather than a reporting problem. These risks I feel, will be addressed with a practical solution. After all, transaction reporting exchange is in place to provide that holistic view of activity on our markets. Without an agreed exchange, the FCA is likely to require market operators to report for members who do not have a UK transaction reporting obligation and similarly from the EU’s perspective.

    What about EMIR?

    For EMIR it is a similar story. EMIR needs to be global, not just European, if the data is to be useful for identifying emergent risks to the financial system: its primary aim. ESMA is currently working with Trade Repositories to standardise how information is made available to the array of regulators that have access rights to this information. Creating a UK specific regime, however well designed, would be an unwelcome complication for firms and Trade Repositories.

    Dual-sided vs single-sided

    Recent EMIR discussions have been around dual-sided vs single-sided reporting. My view is very pro dual-sided between financial counterparties as this goes a long way to promoting reporting quality. That said, for those non-financial counterparties delegating reporting to their broker, there is very little benefit for reporting quality of dual-sided reporting so this could easily be dropped. Similarly, many of the larger firms have created centralised reporting solutions and would not welcome divergence from the EU requirements, creating yet another distinct reporting obligation.

    So all in all, due to the added complications, and the UK having been a chief instigator in tougher reporting measures, I expect that the reporting world will continue very much in the same vein despite the UK voting to leave the EU.

  • Why data quality is key to regulatory reporting compliance

    Why data quality is key to regulatory reporting compliance

    The FCA has used its latest MarketWatch newsletter to remind firms of their transaction reporting obligations, the persistent poor quality of their reporting, and that the FCA have mechanisms in place to detect errors which may result in stringent actions such as fines.

    While this message isn’t new, the FCA has also published a table showing approximately 650,000 data quality breaches across the industry over a one-week period where the FCA’s Transaction Monitoring Unit (TMU) tested only four of the transaction reportable fields. It will be a disappointment to the FCA that in each instance the errors are ones previously made by firms sanctioned for incorrect transaction reporting as well as errors highlighted in previous Market Watch newsletters. These include things such as late reporting of transactions, incorrect MIC codes, wrong execution times, wrong quantity or missing unit price.

    Just the tip of the iceberg

    The one-week snapshot by the FCA does not reveal the true size of the problem.  We took a closer look and analysed in detail the findings of the publicly available fines issued to firms for incorrect transaction reporting since 2009.  Our findings are displayed in the graphic above.

    1. Tip of the iceberg: Maybe not the perfect analogy, but for those firms fined and where information is publicly available, we found only 35% of the firm’s reportable transactions were reported accurately and completely. That is to say, passed ARM validation and the data was correct.
    2. Base of the iceberg: That leaves 65% of the firms’ reportable transactions being reported incorrectly or not at all. In all cases, firms did not have appropriate controls in place to identify and test the correctness of their reports. In short, they were unaware that the majority of their reports were incorrect.

    Only 7% of the transactions were not attempted to be reported or were duplicates.  All of the remainder were breaches where the report passed validation but the data was incorrect. In other words, they were ‘valid but wrong’.

    Transaction reports must be tested at source

    What this tells us is that firms need testing at source not just ARM validation. Even after eight years of MiFID transaction reporting, numerous warnings and increasing fines from the FCA, significant numbers of transactions are being reported incorrectly with firms unaware of their inaccuracies. In addition, firms are deriving false confidence from passing the validations provided by ARMs and the FCA.

    Importance of getting reporting right

    In Market Watch 50, the FCA TMU makes it clear that they see failure to produce current MiFID reports of good quality as an indication on how well a firm can meet its future and more complex obligations under MiFID II/R and in part, compliance with the recently introduced Senior Managers Regime.

    It says: “The ability of firms to submit accurate and complete transaction reports is essential if they are to be in a strong position to meet the more complex requirements of MiFIDII/R.” It also reminds firms: “If we continue to find firms that fail to identify or mitigate risks associated with market abuse then we will take stringent action against those firms. These actions could include penalties such as fines.”

    This echoes the warnings raised by the FCA in all of the public fines for transaction reporting. The obligation to make complete and accurate reporting is also unambiguously clear through the FCA Handbook (SUP 17) and the Transaction Reporting User Pack (TRUP 3.1).

    Detecting market abuse

    In Market Watch 50, the FCA also reminds the industry of how important a tool transaction reporting is to allow them to detect market abuse.  Poor quality data directly affects the ability of the FCA, European competent authorities and other regulatory bodies such as the Bank of England to detect market abuse or carry out their supervisory responsibilities.

    Where to from here?

    The picture illustrated by the fines for transaction reporting is one where a large majority of reported transactions have passed high levels of validation but the data is still inaccurate. Failure by firms to report correctly is a major industry problem. Firms need to change their approach to protect themselves under the current MiFID regime and the upcoming MiFID II/R in 2018.


    Kaizen’s ReportShield™ accuracy testing checks transaction reporting data at source and identifies transactions successfully submitted to ARMs and the FCA but still wrong.  An independent, managed service, ReportShield is already being used by a number of firms to provide reporting assurance and deliver confidence to management and the regulator. The service significantly reduces risk to firms, offers protection to managers who have SMR responsibilities, and is delivered at a significantly lower cost than testing in-house.

  • Collateral transfers are to be explicitly excluded from MiFID II transaction reporting

    Collateral transfers are to be explicitly excluded from MiFID II transaction reporting

    ESMA has published a final report on RTS 22 which seeks to amend the original drafting to explicitly exclude collateral transfers.

    The potential introduction of collateral transfers as reportable transactions was of significant concern to the industry so this development will be warmly welcomed.

  • UnaVista partners with Kaizen Reporting to offer quality assurance solution

    UnaVista partners with Kaizen Reporting to offer quality assurance solution

    “Clients will now have access to our market leading reporting service, with comprehensive systems and controls such as our reconciliation, accredited training courses and Kaizen’s unique ReportShield technology.”–Mark Husler, CEO of UnaVista

    • Since 2009, 180 million transactions identified in FCA enforcement notices under MiFID regulation with valid but incorrect data
    • Quality assurance testing is regulatory requirement for MiFID II
    • UnaVista clients benefit from free trial of service

    London Stock Exchange Group announced today that UnaVista, its global regulatory reporting platform, has partnered with leading regulatory reporting testing and compliance firm, Kaizen Reporting. The partnership will give UnaVista clients access to Kaizen Reporting’s ReportShield™ service, which offers quality assurance testing of MiFID transaction reports at a field level, as well as governance training and consultancy.

    UnaVista’s market leading Approved Reporting Mechanism (ARM) already provides clients with advanced validation checks to ensure submitted data is valid. Kaizen Reporting’s ReportShield testing service, combined with UnaVista’s Reconciliation service, will allow firms to test the quality of their source data for valid but incorrect information. Firms can then correct the errors in their systems and reduce the risk of future misreporting irregularities.

    MiFID, and the upcoming MiFID II regulation, stipulate that firms must conduct rigorous testing and front to back reconciliations to ensure the accuracy and completeness of their regulatory reports*. In their enforcement notices, the FCA has identified 180 million transactions that have been submitted since 2009 with valid but incorrect data. As this figure only includes firms that have been subject to sanction, the real industry figure is considered to be much higher.

    The FCA have also cited that weaknesses in systems and internal controls relating to transaction reporting as one of the main reasons that firms were penalised for their MiFID Transaction Reporting.

    UnaVista and Kaizen’s combined service will assist firms by enabling high quality, comprehensive testing and reconciliations in a cost effective manner. The service will initially be launched for MiFID reporting and will be rolled out across other reporting regimes, including EMIR, Dodd-Frank, other G20 reporting regimes and MiFID II when it goes live.

    Mark Husler, CEO of UnaVista said:

    “This partnership with Kaizen allows us to provide clients with the full suite of services they require for compliance with EMIR, MiFID and upcoming MiFIR regulation. Clients will now have access to our market leading reporting service, with comprehensive systems and controls such as our reconciliation, accredited training courses and Kaizen’s unique ReportShield technology.”

    Dario Crispini, CEO of Kaizen Reporting said:

    “We are delighted to be partnering with the market leading MiFID reporting service, UnaVista. Incorrect reporting is a major industry problem and we want to help firms get it right.  By deploying an innovative new approach to testing data, Kaizen’s ReportShield testing service is able to provide full visibility of all reporting activities so that errors can be identified and fixed quickly.  This gives firms’ senior management the confidence they need that they are compliant with regulators’ expectations.”

    Notes to editors:
    *Section 10 of FCA’s Transaction Reporting User Pack (TRUP) 3.1
    http://www.fca.org.uk/static/documents/finalised-guidance/fg15-03.pdf (pages 53-55)

  • Updates From The Deutsche Boerse Buy-Side Working Group

    Updates From The Deutsche Boerse Buy-Side Working Group

    Stephen Hanks from the FCA provided some interesting feedback about MIFID II progress at the Deutsche Boerse Buy-Side Working Group (April 21) which we were speaking at and attending. We wanted to share some of the key points we learned at the event.

    Broad points of interest:

    • The finalised delegated acts for MiFID II should be published next week (week commencing 25 April) closely followed the week after with MIFIR delegated acts.
    • The FCA advised that with regards to the waiver volume caps, the debate continues around the appropriate calculation approach. This highlights the ongoing industry concerns regarding these caps being exceeded and all activity in a security being fully lit. As discussed at the working group, it is too early to assess the impact this could potentially have.
    • Questions also remain about principle trading by an institution operating an MTF and what the firm operating the MTF could put through the platform.
    • The FCA also suggested that EU level discussions implied that systematic internalisers would not be able to use matched principal activity as their primary trading model on the SI platform as such activity is considered to fall outside the purpose of the SI regime. The FCA advised that questions also around price improvement under the SI regime should also be dealt with in the delegated acts to be published in the next couple of weeks.

    From a transparency perspective the FCA provided the following comments:

    • Regarding the establishment of a CTP for equity securities, no indications of interest have been received by authorities from potential service providers.
    • For non-equity securities there will now be a phased approach for SSTI.
    • The FCA confirmed that size thresholds for bonds and the present 100k euro threshold was also being looked at by ESMA.
    • As per recent statements, ESMA will also be producing new advice for non-equity transparency.

    From a transaction reporting perspective:

    • ESMA is also reviewing the definition of an ARM and what activities would trigger the requirement to register as an ARM. Debate has been raised as a result of there being unregulated intermediaries conducting key activities between the regulated firm and its ARM. This would mean that regulators would only have locus over a portion of the process and not all of it.
    • The FCA advised that although there are questions around the benefits of including ‘short selling’ flags in the transaction report, this will remain a requirement.

    The main take away here is clearly the timing around the publication of the finalised acts. This will firm up requirements being created under the legislation. Those managing the MiFID II projects have been waiting for the acts to be finalised to progress the work required which is significant for all financial firms. The acts are also bound to raise further discussion points and once published, will provide the platform for progressing with the Level 3 work.

  • Continued uncertainty around future transparency under MiFID II

    Continued uncertainty around future transparency under MiFID II

    The European Commission’s late pushback on MiFID II will cause the industry further headaches and has not surprisingly frustrated ESMA.

    Last week, the Commission rejected three of the 28 MiFID II technical standards asking ESMA to take another look at them.

    ESMA has responded in three open letters, saying it will get to work straight away but has made it clear that the Commission has not followed procedure and should’ve got back to it by the end of December, not nearly three months later.

    One of the issues the Commission has asked for a rethink on are ESMA’s proposals for bringing more transparency to the bond markets – something we here at Kaizen are particularly interested in.

    Damage to liquidity

    The Commission’s concerns around bond market transparency are consistent with the views of the industry. The minutes of the FCA’s recent trade association roundtable highlighted not just worries from a bond market perspective but whether appropriate and equal consideration is being applied to the other asset classes coming into scope for transparency under MiFID II such as derivatives. The new regulation is clearly attempting to remove the opaque nature of these sectors. However arguments continue that the MiFID II RTS as currently drafted would potentially damage liquidity and would in fact be harmful to liquidity providers. The Commission has clearly acknowledged these concerns and ESMA is now revising its approach.

    Further challenges for implementation

    Although a rethink on MiFID II transparency may initially appear positive, for the industry as a whole it creates further problems. Without clarity on these standards, firms will have to make broad assumptions around the current guidance as they progress with MiFID II implementation. It is unclear how long it will take ESMA to review, but the European Parliament has been clear that further delays beyond 3rd Jan 2018 are not an option and the deadline must be met.

    Considerable challenges

    ESMA’s response not surprisingly has highlighted the ongoing frustrations that exist in this extremely delicate and challenging area.

    ESMA’s letter reveals that the Commission views the current transparency proposals on calculating liquidity inappropriate and that more frequent, timely calculations are required. It is understandable given that within the new market sectors liquidity fluctuates dramatically over short periods and a liquid security can rapidly move to being illiquid. ESMA has already faces considerable challenges sourcing the data to calibrate the regime as the MiFID only gives them the power to obtain transparency data post MiFID go-live.  In recognition of this conundrum the draft text proposes all FX derivatives be classified as illiquid for the transparency reporting obligations until such time as ESMA is able to source and assess more meaningful data.

    Developments here will need to be closely monitored as small changes in the regulations have the ability to create a major impact on MiFID II projects.

  • Five things we learned from the FCA’s MiFID II venue roundtable

    Five things we learned from the FCA’s MiFID II venue roundtable

    FCA’s MiFID II trading roundtable have been published. What did we learn?

    • ESMA Level 3 Q&As will not be published until the implementing measures are finalised. Given what now appears to be an inevitable delay of 12 months, the guidance could be significantly delayed as questions remain outstanding in several key areas such as transparency for non-equity securities.
    • The FCA advised that their own second MIFID II consultation paper was likely to be published in the middle of 2016. Again the exact timing of this depends upon the progress with the implementation measures.
    • Venues continue to stress concerns about the new obligations.  For example, where the entity utilising their services is not obliged to report and therefore creates an obligation upon the venue to report the activity executed to meet reporting obligations.  Further clarification is still required here however clearly this creates a significant onus upon the venues that does not exist today. The FCA did confirm as per their guidance that a venue would be expected to report such activity to their home member state.
    • The effective processing of transparency waivers is also a significant concern to venues. The FCA confirmed that interfaces are in place between it and ESMA which allow for batch processing to assist with the timely processing of waiver applications. Waivers will need to be in place for each venue for market participants to utilise the appropriate exemptions and deferrals from publication requirements.
    • Under AOB the FCA was questioned on the approach towards direct market access (DEA) by 3rd country clients (non-EEA). The FCA advised there are a couple of key considerations here. It confirmed questions have been raised with the European Commission about exemptions in Article 2.1 (d)  for those dealing on own account with DEA access based outside EU. With regards to firms based outside the EEA providing DEA access, the FCA confirmed that the consultation paper followed the Treasury implementation legislation which did not permit firms based outside the EEA from providing access to EEA trading venues.
  • MiFID II fee proposals – how will they impact you?

    MiFID II fee proposals – how will they impact you?

    Feedback on the FCA’s fee proposals to recover the costs of submitting data under MiFID II is expected to be released shortly.

    The consultation began in November and finished early last month.  The proposals may have slipped notice however the fees will need to be included in the budgeting process going forward and may significantly impact smaller commodity derivative trading firms and firms that are (or are considering) becoming operators of a trading venue.  The proposals are summarised below and will be of interest for firms that will operate an MTF, OTF or a regulated market under MiFID II as well as firms executing commodity derivatives or acting as a systematic internaliser.

    More transactions, higher fees

    Whilst the costs are not excessive, if firms submit reports directly to the FCA the costs are likely to be prohibitive for smaller firms pointing to the need for intermediaries such as Approved Reporting Mechanisms (ARMs) to aggregate submissions, particularly for commodity position reporting.  The consultation paper doesn’t provide any hint as to the ongoing maintenance and administration costs to run the service but this is likely to be substantial.  The consultation proposes that these costs are raised from the ‘relevant firms that benefit from effective market reporting’.  It is not clear what they mean by this but I suspect they are referring to a per report fee that will be levied on the firms for which the report has been made.  So that means the more transactions, the higher the fees.

    Data Reporting Service Providers

    MiFID II creates a new type of entity called the Data Reporting Service Provider (DRSP).  This category encompasses ARMS, Approved Publication Arrangements (APAs) and Consolidated Tape Providers (CTPs).  Each of these entities require authorisation by a competent authority under the DRSP regulations but in addition, as they have to submit data to the competent authorities, they need to connect to the competent authority’s systems.

    To capture this data the FCA is looking to appoint a Market Data Processor (MDP) who will manage the connectivity and processing of the above data.  The costs of the MDP, authorisations and ongoing supervisory activities have to be recovered.  The FCA’s fee consultation paper sets out their proposals in this regard.

    FCA application fees

    There is a separate fee structure proposed for DRSPs (ARMs, APAs and CTPs) as they are regulated outside of FSMA (The Financial Services and Markets Act).  The DRSP fees will not apply to entities that are “incoming” DRSPs.  Incoming DRSPs are ARMs, APAs and CTPs that are authorised in another EU jurisdiction.  Incoming DRSPs will have to contribute to the costs of connecting to the FCA’s systems but will not face application fees.

    Investment firms providing DRSP services will incur the DRSP fees in addition to their FSMA fees.  Such applications will not be treated as variation of their existing permissions but as full applications as it is under a separate regime.

    FCA periodic fees

    Periodic fees have been proposed as a new G25 fee block for DRSPs.  Rates will be confirmed once the FCA’s costs are better known.  The periodic fees apply for the first quarter pre MiFID go-live as a flat rate fee of £20-30k for each authorised DRSP.  Where the DRSP is authorised for more than one category, e.g. as an ARM and an APA, the proposal is an additional 50% of the periodic fee for each additional DRSP category.

    The tables below set out the proposed fee structure.  If the fees collected fall below the costs incurred overall by the FCA then the difference will be collected via periodic fees.

    FCA DRSP fees

    [supsystic-tables id=’2′]

    FCA data submitter on-boarding fees.

    Only one connectivity/on-boarding fee would be applicable for the MDP.  So if a firm is connected for transaction report submissions they would not have any additional on-boarding fee for other data types.

    [supsystic-tables id=’3′]

    FCA ongoing transactional fees

    It is not clear how the regulator’s ongoing costs of operating the reporting system will be recovered but we anticipate that there will be a fee per transaction report made.  This could be levied directly on the parties submitting to the FCA, principally the ARMs and trading venues and if so, these parties are likely to pass through these costs to their clients, the reporting firms.

    *subject to change

  • MiFID II delay confirmed but there’s no time to waste

    MiFID II delay confirmed but there’s no time to waste

    The European Commission has confirmed the MiFID II implementation deadline has been extended by a year to 3 January 2018.

    While this isn’t in any way surprising, the clarity is welcome news for the industry after ESMA initially proposed a delay in November. The Commission says the delay is to ‘take into account of theexceptional technical implementation challenges faced by regulators and market participants.’

    Twenty-two months is still a very short time for firms to complete all the changes required for MiFID II.  Given the significant size and scope of the new reporting requirements – affecting a much larger group of market participants – those affected should take action now if they haven’t already done so to get themselves ready. 

    A year’s delay may seem like a long time but firms should not take their foot off the pedal.  The reprieve to 2018 means it is likely that regulators will have less tolerance for those who do not meet the new reporting requirements from the get-go.  In addition, those who leave it to the last minute may find themselves with much higher implementation costs.

    We can help firms prepare for the new transaction reporting requirements required under MiFID II from getting your transaction reporting in order through to bespoke training on the new requirements.

    Contact us to find out how we can give you MiFID II peace of mind.

  • It’s crystal ball time – regulatory reporting in 2016

    It’s crystal ball time – regulatory reporting in 2016

    As the memories of performances of A Christmas Carol fade, the ghosts of Christmas past, present and future are a useful analogy to convey the challenges firms will encounter in meeting their regulatory reporting obligations in 2016.

    From the past, MiFID reporting of the 2007 vintage still provides a real and present risk to firms. The present, in the form of EMIR and DFA reporting, will undergo changes to requirements. Looking to the future there are a number new obligations that are due (REMIT, Money Markets) and significantly, the highly likely delay of MiFIR/MIFID II to 2018. A common theme running through all obligations is the increasing levels of scrutiny from regulators and therefore of firms’ senior management.

    Past

    Despite all the focus and costs expended upon the new reporting obligations globally, still the most material risk to firms in getting their reporting wrong is UK transaction reporting required under MiFID since 2007. Last year we saw fines break new records, reaching GBP£13m and it is not inconceivable that in 2016 firms may receive higher fines. It is crucial that firms do not take their eyes off the ball so that they continue to adhere to legacy reporting requirements.

    Present

    The introduction of EMIR and DFA obligations over last few years is still fresh in the minds of regulators, trade repositories and firms. In 2015 EMIR reporting has seen significant change with ESMA mandating trade repositories to introduce much higher levels of validation on firms’ submissions. In the year ahead we expect to learn of further significant changes to EMIR reporting obligations as a result of both the consultation of 2015 and knock-on effects of EMIR clearing. For those firms who have a DFA reporting obligation, the later part of 2016 will see changes to CFTC Part 45 rules as part of the rewrite. Firms will need to plan for changes to obligations that have only very recently been introduced.

    Future

    Wherever you look, there are new reporting obligations with compliance dates in 2016. In the energy markets, REMIT OTC obligations are due in the second quarter. In the third quarter Switzerland is set to introduce its version of EMIR. Despite the advent of trade repositories, the central banks are requiring their own reports. In the second and third quarters of this year, the Bank of England and the European Central Bank are requiring money market reports. MiFIR/MIFID II is the one omission from the list, due to the highly likely scenario that it will be delayed from January 2017 to January 2018. Despite this delay preparation for the MiFIR requirements for transaction, trade reporting and instrument data reporting will dominate the change agenda for 2016/17.

    Common theme – increased scrutiny

    Regardless of whether the reporting obligation is a legacy requirement, recently introduced, or with a compliance date in 2016/17, the expectations and scrutiny of regulators is only on an increased trajectory. As such, expect increased fines for those more mature reporting regimes (MiFID). For more recent regimes, fines (DFA) have already been issued or greater scrutiny from regulatory bodies is becoming evident (EMIR). Future reporting regimes will be expected to hit the ground running with high quality reports expected from the get-go. The importance of ensuring correct reporting has never been as important to firms and the financial system as a whole.

  • ESMA gets in just before Santa to consult on clocks, data, records and reporting under MIFID II

    ESMA gets in just before Santa to consult on clocks, data, records and reporting under MIFID II

    ESMA’s consultation paper on some MIFIR/MIFID II guidelines were delivered, as promised, before Rudolph had his harness fitted. Well… just about.

    Those still at their desks on 23 December were left scratching the heads on whether they had been naughty or nice as they began to pore over 269 pages of guidelines on transaction reporting, reference data, order keeping and clock synchronization. 

    You may be relieved to hear that we will not be going through all 269 pages in detail in this blog (and there’ll be no more Santa related puns). Instead we look to set this document in context, explore its usefulness, its purpose, and briefly summarise the structure and content.

    Context

    The publication of the consultation paper continues the exercise of adding further granularity to the obligations required under MIFID II/MIFIR and then built upon under ESMA Regulatory Technical Standards (RTS) 22, 23, 24 and 25.  On page 7 of the consultation paper ESMA explains that:

    “…this guidance complements the technical standards and will be essential for the consistent implementation of the new MiFIR rules.”

    Are they useful?

    Considering the already published details under the directive, regulation, and RTS, it is valid to ask whether further granularity and detail is required. It’s worth considering the guidance provided by ESMA to market participants who have to meet EMIR reporting obligations. Under EMIR, guidance was provided in a piecemeal ad-hoc fashion. Guidelines were not drafted and published for consultation, clarifications were instead conveyed via a ‘Question and Answers’ document. For those who have Dodd Frank Reporting (DFA) obligations (under Chapter 17 part 43, 45 and 46) no further guidance other than the regulation was provided. So seen in this light – having well thought out, structured, and consulted upon guidelines should give firms a greater chance of delivering increased quality and consistency of reporting.

    Regulators’ expectations

    The regulators who drafted this consultation document have the experience of reporting under MIFID and as a result, the standards of the RTS and now these guidelines are more informed, detailed, and consistent than compared to EMIR.  Therefore there will be a greater expectation that the quality of MiFIR reporting will be high from the beginning. To increase the likelihood of the guidelines being successful ESMA will consider all comments received by 23 March 2016. Having guidelines that have been written by regulators with previous experience and consulted upon with market participants – combined with a potential year’s delay to MIFID II – gives the best chance of correct reporting than any of the recently introduced reporting obligations such as EMIR and DFA.

    Structure and content

    The guidelines’ length of 269 pages may make it feel impenetrable and inaccessible but on close inspection this is not the case. While there are four issues covered in this document – transaction reporting, reference data, order record keeping and clock synchronization – here we just review the transaction reporting section, which takes up 193 of the 264 pages and is made up of four parts.

    • Part I: General Principles
      Includes guidance on the how, what, when, where to send reports and exclusions.
    • Part II: Blocks (not to be confused with block trades!)
      A block is a collection of fields, which relate to a particular topic and there are 12 blocks in total. For example, block 1 deals with buyer/seller identification, block 4 deals with execution time within the firm and block 10 branches.
    • Part III: Scenarios
      Outlines different trading scenarios that a reporting party may encounter. For example, transmissions of orders, grouped orders, provision of direct electronic access.
    • Part IV: Instruments
      Offers clarity on what instrument data is required to be populated on reports. Focusing primarily on derivatives, this section prescribes when an ISIN is applicable versus when characteristics of the instrument are required.

    In each of the four sections ESMA attempts to provide clear notes on guidance backed up by an example and then an outline of what is expected to be included in the report. It is worth noting that two thirds of the nearly 200 pages on transaction reporting are made up of examples of how the report should be reported.

    Welcome step, but…

    The guidelines and the opportunity for the industry to provide feedback is a very welcome step. Taken together with the MiFID II/R RTS and the now likely year delay, the industry has the materials at its disposal for introducing high quality reporting on go-live. Though I do have a note of caution for firms: ESMA and the competent authorities’ expectations will be high and individuals under the senior managers regime (coming into effect in quarter 1 next year) will be held to account for any failings.

    Over the coming weeks and months we will explore in more detail the effects and implications of guidelines so keep an eye out and feel free to raise questions or comments either to me (dario.crispini@kaizenreporting.com)or via Linkedin or Twitter. Happy New Year from all of us at Kaizen!

  • Is indirect clearing any clearer?

    Is indirect clearing any clearer?

    ESMA has published its latest consultation on Indirect Clearing Arrangements under both EMIR and MIFIR. The consultation paper covers both ETD and OTC derivatives and is designed to ensure consistency between the two regimes.

    The paper looks at “longer chains” and states that:

    “The requirements applicable to a direct client would need to be extended to all the intermediaries between the clearing member and the counterparty at the end of the chain. This means in particular that the provisions related to default management apply throughout the chain, including the requirement to protect through contractual arrangements, to the extent possible, what is owed to the indirect client in relation to the indirect clearing services from the insolvency of any of the intermediary clients providing clearing services.”

    For more information please refer to the Consultation Paper.

  • Finally it’s out, proposed 12 month delay to MiFID II

    Finally it’s out, proposed 12 month delay to MiFID II

    The industry has been mooting a delay to MiFID II for some time now and there were elliptical comments by the FCA and ESMA representatives at the recent FCA conference hinting at an appetite for a delay.  Now, a one year delay was proposed at a hearing of the European Commission’s Committee on Economic and Monetary Affairs yesterday.

    In a statement, MEP Markus Ferber, Rapporteur for MiFID II, blamed ESMA and the European Commission for “dawdling time and again…………responsible for the delays are solely ESMA and the Commission.”

    In a speech by Steve Maijoor to EU institutions published today he raises the need for legislative measures to delay MiFID II principally due to the amount of preparatory work required for building both the rules and IT required for its implementation.

    For a delay, an amendment to the level 1 text will have to be agreed. With today’s announcements that looks extremely likely however it has to be stressed that the European Commission has said only that they are thinking about a delay.

    An additional 12 months would be a boon to firms struggling with implementation.  A delay will mean that there is more time for middleware and service providers to develop their offerings allowing firms to have more clarity on their implementation options.

    A delay may very well result in higher project costs for firms as the projects are extended out but overall they will be better placed to make their preparations.  That said, there will be little appetite for late or poor implementation by firms particularly when it comes to transaction reporting quality.  An extra year would mean that firms now have everything they wanted for the implementation so regulators will expect them to get it right.

  • MiFID II implementation roundtable

    MiFID II implementation roundtable

    For those tracking MiFID implementation activities, the FCA have posted their minutes from the October MiFID II Implementation Roundtable with trade associations.

    The minutes largely cover communication plans including the provision of webinars and other supporting materials to help with the implementation and interpretive challenges that exist.  A couple of areas they covered of interest is the use of endorsed industry guidance which the FCA wants to move away from. However they did say they would be happy to review material produced by the trade associations which is encouraging.  They also cover feedback on its recent MiFID II conference.  See our earlier blog.

  • Good and bad news for transaction reporting under RTS 22

    Good and bad news for transaction reporting under RTS 22

    Fewer reportable fields doesn’t necessarily mean less work.  In this blog, we look at the key changes in RTS 22 from the original  MIFID II consultation proposals and provide some conclusions on the overall impact.

    We carried out a detailed analysis of the reporting fields in the revised draft regulatory technical standards (RTS) released by ESMA.  RTS 22 is the section which sets out the transaction reporting obligations and reportable fields.  The analysis takes the fields in the original consultation paper and compares them to the equivalent versions of the fields in the final report.  In many cases this is a one to one mapping after accounting for some changes in the terminology used.  If you want to take a look or to use the table of fields for your own analysis we have published this as an excel document.

    So what did we find? Taken at face value the number of fields have been reduced from 81 to 65 fields.  A reduction of 16 fields, which is seemingly good news.  However this apparent reduction masks an increase in the information that reporting firms will have to capture and submit – not such good news.

    New fields: Our analysis shows there are 10 new fields which have been added.  The overall reduction in the number of fields results from 13 control fields (code type e.g. LEI vs national identifier) being removed.  We expect that seven of these will be included within the ISO 20022 reporting schema and therefore firms will have to continue to report them.  The remainder are no longer necessary for fields where only one code type is permitted for reporting which again will be enforced through the reporting schema.

    Fully removed fields: Nine fields in total were removed.  “Postcode” and “country of residence” fields have been removed for several identifier fields as has the “consideration” field and the “option exercise” field  is no longer a reportable activity.

    Compressed into another field: Three fields have been compressed into other existing fields, so in essence the information is still to be reported.  The three counterpart fields remain.

    Unchanged: A total of 52 fields remain unchanged in terms of field name.  There are some wording changes embedded which will need further analysis as these will have implications for reporting.

    You can also find our full analysis of the tables below which have the original data fields and revised data fields side by side so you can conduct your own analysis.

    [supsystic-tables id=’6′]

    The 10 new reporting fields:

    Providing these additional fields will in some cases be easy, such as field 5 stating whether you are a MiFID firm or not, whilst others will be very challenging, such as field 40 “complex trade ID” and “instrument full name”.  This latter field is likely to be supported by further guidance given it will be used to identify all derivatives which are not allocated an ISIN code.

    [supsystic-tables id=’5′]

  • Just a second…?

    Just a second…?

    MiFID II introduces the requirement to synchronise the business clocks of trading firms and their customers so that timestamps recorded are standardised across the industry. The idea is that regulators will be able to monitor for market abuse more accurately. Trading systems will need to synchronise themselves to a common source of time. But how will they do this? And what are the implications?

    On the back of the FCA’s MiFID II conference this week we were with the National Physical Laboratory (NPL) to find out. Their workshop, “UTC traceability for the global financial sector, realisation of a unified common clock” attempted to answer some of these questions. Taking the front seat was MiFID II’s RTS 25, which outlines the draft regulatory technical standards on clock synchronisation. The direct impact of this piece of regulation was apparent from the range of professionals from all aspects of the industry including financial firms, exchanges, consultants and scientific organisations.  Most notable was the presence of ESMA and the Bureau International des Poids et Mesures (BIPM) as both have a heavy hand to play in RTS 25. We suggest firms take a look at Table 2 in the Annex of RTS 25 which sets out the level of granularity applicable to their trading activities. It is important that firms are clear on what is expected of them and should be in advanced discussions around the technology to be adopted to meet the new regulatory obligations.

    Here are the key points we took away from the conference:

    1. The industry was concerned about deploying GPS as a means to synchronising their business clocks. It was felt that although it meets the regulators’ authorisation of “satellite systems” as a credited tool, it does not provide traceability back to UTC.  This was further supported by BIPM who claimed that due to the irregular leap second lag incurred through GPS signals, the only credible solution was a direct feed from a National Measurement Institute (NMI). ESMA was clear that both options remain and stood firm, stating that they must be realistic in what they ask from firms and not show any bias to any provider.
    2. The industry feels this needs to be part of the Level 3 discussions but it seems very unlikely that GPSs will be scrapped. We advise all firms to gear up based on the Level 2 RTS 25.
    3. The industry also showed concern around implementing the required technology and sought r advice from the regulator. However, ESMA’s view was very clear in stating it is up to the firm to implement what is required.
    4. ESMA highlighted the importance of firms reviewing their transparency systems on an ongoing basis once deployed. The type of review required is not clarified within the RTS, however we would recommend both internal and third party checks to ensure obligations are met.
    5. FIX is planning to update all versions of its protocol (back to FIX 4.2) to capture the accuracy of seconds in timestamps to 6, 9 or 12 decimal places.
    6. BATS Chi-X Europe is considering providing NPL time source feeds to its clients via a PTP feed if there is considerable demand.

    All in all, the industry is aware of the challenge in implementing this step and the effects it will have on their infrastructures. However, having the same “watch” is very much welcomed by all concerned, agreeing it will lead to better data publication and reporting, thus a more transparent industry as a whole.

    What do you think?  We would welcome feedback or comments about the issues raised in this blog and more broadly, about the MiFID II draft technical standards.

    We’ll be releasing further blogs around the finer details of MiFID II so stay tuned!

    In addition to our testing services, we are offering training courses for firms to help them prepare for the reporting elements of MiFID II. Please contact us to find out more. 

    Read our earlier blog on our reaction to the release of the draft RTSs.

  • 10 things we learned at the FCA’s MiFID II conference

    10 things we learned at the FCA’s MiFID II conference

    Like many of our clients MiFID II is uppermost of our minds at the moment. And on Monday we were discussing all things MiFID II at the FCA’s MiFID II Wholesale Firms Conference in London. Likely to be the first of many conferences about the new regulation, this was probably the earliest event possible given the regulatory technical standards (RTSs) were only released on 28 September.

    Our advice to firms?  Don’t delay: Get your heads around the new rules and get into the detail quickly.

    Here are our key take aways from the conference:

    Regulatory Process

    1. The UK is now working towards transposing the MiFID text into UK law and this must be completed by 3 July 2016 while the European Commission now has three months to consider the published regulatory and technical standards. The FCA’s view is that it is unlikely that the Commission will impose any changes and this position will be affirmed by Q1 2016.  The FCA will publish further consultation papers and these are likely to be split with a consultation paper in December 2015 and an additional one in early 2016.

    2. Regarding the timeline, the FCA acknowledged this is challenging for the industry and regulators alike. However delays to MiFID II are only possible if the Commission considers this is appropriate and it is not within the college of regulators’ powers to impose.  That said, we do think there will be a request for either a partial or full delay given the truncated timetable for what will be a lengthy legislative process.

    3. Organisations not currently within the scope of MiFID I may potentially fall into MiFID II particularly around the commodities space.  These firms will need to quickly plan how they will manage this authorisation process and should submit applications to the FCA by 3 July 2016.   Applications submitted post 3 July will be processed by the FCA on a best efforts basis but there will be no guarantee that applications will be completed before MiFID II goes live in January 2017.  Something that could be very detrimental to business.  A similar story applies to firms that will have to apply for trading venue status OTF or MTF, high frequency trading firms, or as a systematic internaliser.  All activity within firms will need to be assessed to confirm whether authorisation will be required and many platforms are expected to be captured such as broker crossing mechanisms which will come under the new OTF regime.

    Transparency

    4. Following a review by ESMA, the FCA confirmed that agreement had been reached on the approach to be adopted towards the calculation of liquidity and the transparency obligations that would therefore be imposed in respect of non-equity securities.

    5. ESMA, following extensive consultation with industry participants and having reviewed considerable datasets, proposes the liquidity calculation will be applied on an Instrument by Instrument Approach (IBIA).  The FCA believes this will mean real-time transparency reporting obligations for 4% of bonds with a significant portion of these being from sovereign debt.

    6. With regards to deferred publication regime, delays will be possible between two days and up to four weeks from the point of execution.  Venues will also be able to apply for pre-trade transparency ‘waivers’ where the execution is above standard market size. The FCA asked that venues apply for such waivers as soon as possible given that approval is required ahead of trading activity if reliance is to be placed upon any such waivers.

    Commodities

    7. Position limits will be imposed in the commodities sector. The limits will have a cap of between 5-35% of the deliverable supply. Such limits also extend to firms’ open interest positions which imply a potential delivery at such a level. Similarly, the FCA also confirmed that thresholds will be applied to speculative trading in such instruments, and firms exceeding the threshold would require authorisation under MiFID II.

    8. Position limits represent significant challenges for groups with multiple entities trading commodities as the limits are applied both across the group and to each entity so one entity in the group could be within the limits, while across the group the combined total exceeds the position limits. This type of calculation is also to be applied when evaluating whether a firm’s commodity trading activity is ancillary to its main activities or not.  Such calculations look at both the individual entity’s positions and the net positions across a consolidated group.

    9. Position reporting by venues is also a requirement under the new regulations.  The FCA is fully aware of the challenges that the requirements place, not least the need to identify clients down to the ‘end client’.

    10. In transaction reporting, the RTSs are pretty clear but one area we sought clarity on was the new complex trade ID field.  This field seeks to link trades that are part of a wider trading strategy.  Ana Fernandes from the Transaction Monitoring Unit gave a very clear exposition of the aims and drivers behind RTS 22 and confirmed that the aim was to capture true strategies and the intention was not to cover hedging activity or even matched principal activity (riskless principal). However Article 12 wording still points to these transactions being captured.  It is also worth noting that in the RTS ISINs are the only identifier for trading venue instruments.  We expect that was a shock for the likes of Eurex and ICE as the consultation proposal was for Aii codes as well as ISINs.

    What we liked:  In the last session, a panel of regulators including ESMA, BaFin and AMF were quizzed by Nick Bailey of the FCA.  We saw this as very positive in that it shows the regulators are talking to each other; indeed they said that such collusion would be in breach of the competition laws were they operating as firms.

    Once the regulators have had more time to digest the detail of the 900+ pages of RTSs we hope to see more of these events with greater detail and elaboration of the implications for firms and their trading activities.

    In addition to our testing services, we are offering training courses for firms on the reporting elements of MiFID II. If you are interested please contact us. 


  • ESMA writes the control section of your transaction reporting BRD…

    ESMA writes the control section of your transaction reporting BRD…

    ESMA has published its eagerly awaited regulatory technical standards (RTS) for MiFID II for consideration by the European Commission.

    Chapter 7, Market Data Reporting (RTS 22) outlines the obligations for transaction reporting. And for those responsible for drafting their firm’s control section of the Business Requirements Document (BRD) Article 15 of RTS 22 makes their job very easy! Recent regulation, whether it be the Dodd Frank Act (DFA) in the US or EMIR in Europe, has become increasingly prescriptive of the controls expected of participating firms. Article 15 takes this prescriptive nature into a different league, placing testing and reconciliations front and centre.

    MiFIR (Article 26(7)) requires firms to verify the completeness, accuracy and timeliness of the transaction reports they submit. RTS 22 expands on this and explains that complete and accurate reporting data is essential to market surveillance and outlines how that is to be achieved.

    Under the first section of Article 15 there are the usual requirements relating to the security and functionality of data and measures to enable timely resumption of reporting when reporting systems go down and measures to identify errors and omissions.  More specifically there is requirement on firms to have mechanisms to avoid duplicate reporting and under reporting.

    Whereas over-reporting is tolerated under current obligations, reporting transactions where there is no obligation is not permitted and Article 15 says firms will need to have mechanisms in place to identify over-reporting.  Over-reporting is the submission of a transaction report where it is not required under the reporting rules.  This can be reporting a trade on an instrument that is not reportable or reporting a transaction on a non-reportable event such as dividend reinvestment.

    When firms become aware of any of these types of errors or omissions they need to be reported to the relevant competent authority. To that end ESMA mandates not only reconciliations but specifies the data sources and fields to be included; reconciliations should be between front office trading records and information contained in transaction reports and checks should be in place to prove the timeliness of reports and the accuracy and completeness of all the individual data fields.

    In tandem with regular reconciliations, Article 15 states that firms are required to put in place a testing methodology and approach for their reporting processes. The multimillion pound fines issued by the Financial Conduct Authority for transaction reporting breaches over the last five years have often been on transactions which have been reported as valid and been through some form of reconciliation process but ultimately have still breached Chapter 17 requirements of the supervisory manual.  It is these breaches that your testing approach must be able to identify.  The often piecemeal, sample-based testing that is common in firms today will not be satisfactory.

    Kaizen Reporting’s testing approaches are setting the industry standard and will enable you to meet your MiFID II requirements efficiently and cost effectively. We combine unrivalled regulatory knowledge with the latest data analytics to provide the highest level of confidence in transaction reporting. 

  • EMIR level 2 validations – are you ready?

    EMIR level 2 validations – are you ready?

    At the end of October ESMA is introducing new validations to be applied by Trade Repositories (TRs) which I think will be a good thing for reporting quality.  In this article I provide some context to the changes, but contend that validation on its own is not enough to deliver quality reporting.  Validations cannot identify records that are valid but wrong.  For that we need a much smarter approach.

    ESMA and national competent authorities have expressed concerns around the quality of reporting today and they expect firms to address this.  But to promote quality ESMA has taken its first step towards improvement with the introduction of additional validations.

    Some background

    ESMA originally required the TRs to apply very limited validations to EMIR reports. The idea was that the TRs would not reject records because of problems in data quality and submissions would not be delayed by problems with one or more data fields within the report.  Therefore ESMA and other regulators would have access to the data that was available irrespective of quality.

    This approach makes more sense the more data that is submitted with each record.  The reason is that with strict validation, a single error in one field would prevent the remaining data from being received by the TR.  However, this approach requires the reporting entity to have a strong control framework in place to ensure that errors are self-identified and rectified.

    The limited validation approach initially adopted by ESMA differs markedly from that taken for Transaction Reporting.  On launch of the Approved Reporting Mechanisms (ARMs) regime in November 2007 a detailed set of strict validations was specified by the FSA (now the FCA) to be in place before an ARM would receive authorisation. These validations are applied by the ARMs to all records submitted by reporting firms and if the record failed a validation it would be rejected by the ARM and the firm notified.  I am calling this approach strict validation.  Many firms apply their own validations prior to submitting their records to an ARM and the FCA also applies strict validation at the point of receipt creating multiple layers of strict validation the vast majority of which is duplicative.  So we see very low industry rejection rates for reports sent by ARMs to the FCA.

    Benefits of strict validation

    The primary benefit of strict validation is that the submitting firm keeps ‘holding the baby’, i.e. they know when their submission has failed and will be in breach of the timeliness obligations.  They are in effect forced to act to remedy the problem.  The reporting entity does not need to have a good control framework in place to know that they have a problem that needs fixing.

    ESMA has now undertaken a volte face and now requires the TRs to apply strict validations.  Nearly every field is subject to some sort of validation requirement per the L2 validations.

    The change in validation approach clearly introduces new challenges and costs for firms as well as the TRs.  These validations would have been better implemented before EMIR go-live, but it has taken the experience of poor quality data to crystalise this decision.

    So what should firms be doing to prepare?

    There is the immediate problem of ensuring that you will be able to continue to report post October.  That means assessing the impact of the new validations on existing positions and correcting in advance any errors that would result in updates to those positions being rejected.  Similarly, firms should consider whether their process for dealing with rejections can handle an increase in volumes particularly in the early period.

    More than that, firms should be looking at how to identify records that are valid but wrong.  This requires testing of the EMIR reports at the Trade Repository and reviewing the adequacy of their control framework over EMIR reporting more generally.  Errors can be introduced into the reporting process or are a result of an incorrect interpretation of the reporting requirements so care must be taken to ensure that the testing that is conducted doesn’t build in the same interpretation errors.

    More can be said on testing but I will leave that for another post. If you have any views on the above I would be keen to hear them.

  • ESMA reveals latest on MiFID II progress

    ESMA reveals latest on MiFID II progress

    On 7th July, Clifford Chance hosted a workshop on MiFID II progress and implementation at which ESMA’s Head of Markets Division Rodrigo Buenaventura provided an update.

    Mr Buenaventura outlined the continuing challenges faced by ESMA. He confirmed that the eagerly awaited final Technical and Regulatory Standards will now be published in September. With regards to timeline and what now appears to be building rumours around delay, Mr Buenaventura confirmed that there is no discussion at this time in this regard and ESMA is moving towards the 3rd Jan 2017 date. Despite recognising this would be challenging, they currently consider this as achievable. Furthermore, he advised that there is no current provision for phasing in particular aspects of the legislation, although acknowledged that over time this could be considered but it was too early for such consideration.

    He highlighted the key issues that require further consideration and these are clearly still a concern to market participants. These include:

    • non-equity transparency
    • commodity reporting
    • liquidity classification

    ESMA is considering the most appropriate approach towards liquidity calculation and whether this should be undertaken against individual securities or whether to adopt a group approach, for example a dependency upon issuance size. Their preference is currently unclear and will require further analysis.

    The liquidity calculation determines what instruments must be trade reported for market transparency. ESMA believes that the number of instruments that will be subject to trade reporting obligations will increase twenty fold.

    ESMA highlighted they will have a different role under MiFID II as consolidator of various important market data for transparency purposes in order to calculate liquidity and establish reporting obligations. They consider a single engine for this is beneficial to the financial community, avoiding reporting obligations to multiple CAs.

    ESMA also recognises there are significant challenges in respect of the establishment of position limits and that the European environment is completely different to the US. In the US some 60 limits exist whereas in Europe this runs into the thousands.

    Particularly interesting to those in the regulatory reporting arena was the fact ESMA confirmed it has significant concerns around the quality of the data reported under both the MiFID and EMIR regimes. Mr Buenaventura stated they are determined to ensure improvements in the quality of reporting and are working with the various colleges in an effort to address this.  ESMA recognises the importance of improving the quality of derivative reporting ahead of MiFID II implementation.

    ESMA advised they have undertaken significant analysis of market data, having reviewed more than two terabytes of EMIR data on top of significant bond market data to consider the appropriate way forward. ESMA recognised they will need to work with market providers in an effort to source the appropriate data for liquidity calculation and establishing appropriate position limits.

    Overall, ESMA stated they consider the implementing legislation should be an improvement for market participants given the harmonisation that regulation creates as opposed to a directive. Supervision convergence should ensure consistent approaches around requirements across the EU.

    With regards to the approach around implementation, questions were raised around adopting a similar approach to the EBA and the implementation of CRD given the issues experienced with EMIR Q&A.  ESMA will consider this and acknowledged the level of queries will be considerably higher and possibly ten times the 2000 or so queries that were raised under EMIR.

    Overall, Mr Buenaventura highlighted the importance placed on reporting and the significant changes that are taking place.  Furthermore, he stated that the focus on the problems with current standards provides a clear indication that regulators are serious about ensuring reporting quality is improved in order to implement the new legislation effectively. ESMA clearly recognise that the poor quality of data today is detrimental to the objectives the reporting obligation are attempting to achieve and so firms should take note of the obligation to have a control framework in place at MiFID II go-live.

  • A review of the key TRUP 3.1 changes for MiFID

    A review of the key TRUP 3.1 changes for MiFID

    The FCA published revised transaction reporting guidance in TRUP 3.1 on 6th February 2015. The key changes come into effect six months after publication on 6 August 2015 whilst other changes which are considered to be for clarification purposes have immediate effect.

    The changes impact the following areas:

    • Trading capacity field
    • Reporting the unit price for bonds
    • Venue field clarifications
    • Strategy trades
    • Self-hitting trades
    • Firms’ systems and controls over transaction reporting activities

    Capturing changes in the firm’s and clients’ positions

    TRUP 3.1 states that “Firms must ensure that the trading capacity field is populated in transaction reports so as to accurately reflect the changes in positions of the firm and its client(s) at the time of the transaction(s).”

    FCA are looking to capture under its rules and guidance what is reportable in terms of changes in position. There are some scenarios where firms’ current use of the trading capacity field results in a change in position of a client or a firm to not be reflected in the transaction reports. This requirement could be interpreted more broadly to require the reporting of all changes in client and firm positions and I don’t think that is the intention. This would introduce full lifecycle event reporting. Lifecycle events are post transaction events which results in changes to existing contracts such as increases in notional or a change of counterparty or beneficiary. Lifecycle event reporting is not being introduced in TRUP 3.1 rather MiFID II sets out the requirements in respect of lifecycle events. The current MiFID II consultation excludes derivative novations, assignments and compressions from reporting which would not enable these changes in position to be captured.

    Trading capacity changes

    Whilst on the surface the change appears straightforward, it masks a great deal of complexity. The cause is the fact that the legal agreements between a firm and its clients and counterparties determines how this field is to be populated.

    In general this can work quite well. Many firms operate in a principal capacity and populate accordingly. Where firms operate in both a principal and an agency capacity, the complexity begins. Where a firm provides a fill from its own book but is acting as agent for its client it is operating in both a principal and agency capacity. The new TRUP guidance requires that both capacities are to be reported. This is achieved by using the “internal” to denote transfers in and out of an internal account. It is expected that positions would always clear from the internal account. The same process will be applied to trades where the firm fills an agency order by trading in a principal capacity against a counterparty or on venue.

    This means firms will have to have reporting processes in place to capture booking scenarios where there is a transfer from a principal book to an agency book/client account. Recoding of systems to put this into effect is likely to be non-trivial exercise particularly where an actual internal account or washbook is not used.

    The TRUP includes brief examples which I would recommend are closely reviewed.

    These changes are to be implemented by 6th August 2015.

    Unit price for bonds and bond futures

    The price to be reported for Bonds has always been the clean percentage price where the percentage is based on the par value of the bond. There has however, been open questions around instruments that are bond like but are traded in a similar way to equities. This would include securitised instruments that pay a coupon. TRUP 3.1 clarifies that such instruments should be reported with the traded price. So if it is traded as based on a percentage of par, the percentage is reported whilst if it has a price in monetary terms that value should be reported (in the major currency).

    As trading conventions for bonds are not uniform, we are still left with the problem of converting prices from the market convention to a percentage. So problematic bond instruments such as French convertibles which are usually traded with a dirty price based on units and Belgian OLOs which are trading with prices agreed in the form of a yield, will now have to be reported in percentage terms. The Belgian OLOs are especially problematic as firms are required to report trading in these instruments to the Belgian FSMA with the price in a yield format which is contradictory to MiFID and FCA requirements.

    Reporting the venue

    Reporting the venue on which a trade is executed remains a problem field for firms and we see many instances where errors have been introduced when capturing the venue identifier. Whilst there are no new obligations emerging from the TRUP changes, the revised text goes some way to clarify how to populate this field however there are still further elements that firms need to consider.

    Sup 17 and TRUP 3.1 require the use of a MIC code when trading under the rules of a “trading venue”. MiFID I provides the applicable definition of trading venue able:

    “(8) ‘trading venue’ means a regulated market, MTF or systematic internaliser acting in its capacity as such, and, where appropriate, a system outside the Community with similar functions to a regulated market or MTF;”

    There are numerous venues within the EU which have been allocated a MIC code. By definition, as they are within the EU they cannot be considered to be a regulated market or MTF (Multilateral Trading Facility). Similarly, there are venues or platforms outside of the Community which have been allocated MIC codes, many of which cannot be considered to be of similar functions to a regulated market or MTF.

    As such it is not sufficient to establish that there is a valid MIC code for the platform upon which the trade was undertaken. An assessment needs to be made as to whether the platform has similar functions to that of a regulated market or MTF.

    MIC segment codes

    MIC codes are now split between an operator code and the segment code. The venue field should reflect the market identifier code (MIC code) of the market segment where the trade is agreed to be under the rules of the trading venue unless the trade is an OTC derivative trade. OTC derivatives are always reported as “XXXX” in the venue field.

    Happily, the FCA has introduced some latitude in those circumstances where the segment traded is unknown or uncertain whereupon the Market Operator MIC code can be reported. This scenario arises when trading on Xetra where exchange fill data does not identify the segment the instrument was traded on and therefore the operating MIC (XFRA) may be utilised.

    Strategy trades

    Strategy trades are trades where a derivative and its associated underlying are traded at the same time. For strategy trades executed on Aii markets, the underlying, which often has an ISIN identifier, cannot be reported using the Aii market’s MIC code as an Aii identifier is expected by the ARMs and FCA’s ZEN system. The guidance clarifies that in such instances “XOFF” should be reported in the venue field and the ISIN of the underlying in the instrument identifier field.

    Self-hitting trades

    Where a firm trades on exchange, particularly if they are trading in significant volumes, they may hit an order on the order-book which has been placed by another desk, algo or DMA client submitting orders for the same firm. The guidance clarifies that such trades are to be considered transactions and are therefore reportable irrespective of subsequent clearing activities which are likely to net out the two trades to zero. Where the trade is immediately cancelled prior to a trade report being published, then an execution is deemed not to have taken place and a transaction report is not required.

    Firms are expected to have implemented reporting in compliance with the above by 6th August 2015.

    Transaction reporting arrangements within firms

    As in previous versions of the TRUP there is guidance on the FCA’s expectations in respect of reporting firms’ controls over the accuracy, completeness and timeliness of their reporting. TRUP 3.1 is more explicit than previously and sets out expectations in respect of the training that those involved in transaction reporting are expected to have (including elements of the training content) and the expectation that firms will conduct front to back reconciliations between front office systems and the reported transactions.

    Whilst many firms will already have controls in place, a review of the controls and whether they satisfy all the areas outlined in the TRUP is recommended.

    Kaizen Reporting Services

    Kaizen offers a suite of services which meet all the requirements of the TRUP 3.1 including execution of front to back reconciliations, reconciliations to FCA data, report testing services as well as comprehensive training on the reporting obligations and reporting health checks.

    If you have concerns or questions about EMIR or Transaction Reporting then please contact us. We would be happy to provide an initial review of your transaction reports at no cost allowing you to try out our report testing service.

  • NYSE LIFFE MIC changes following migration to ICE Futures Europe

    NYSE LIFFE MIC changes following migration to ICE Futures Europe

    The NYSE LIFFE Market Identifier Code (MIC code) is to change following their migration to ICE Futures Europe including guidance on BClear instruments.

    This change has a direct impact upon firms’ regulatory reporting obligations impacting both EMIR trade repository reporting and MIFID transaction reporting obligations. This note summarises the changes and what action firms should be taking.

    The ICE migration is complicated in that the exchange contracts are being migrated over 5 different dates with the final date of migration being 17th November 2014. Firms should note that fixed income instruments migrated over three different dates therefore the MIC for the respective contract needs to accurately reflect these changes. Further complexity is that close attention is also required in respect of the appropriate MIC being applied for example the MIC code is different for Equity Index Futures (IFLL) and Options (IFLO) contracts and this needs to be identified correctly in firms static data and subsequent reporting.

    What should firms be doing?

    Firms’ static data needs to be amended to reflect the correct MIC code at the time of the changeover for the impacted contracts. Post implementation quality assurance testing should be applied to ensure that EMIR and MiFID transaction reports reflects the MIC changeover and any timing errors are corrected.

    With various LIFFE contracts being migrated to new MIC codes in stages firms will need to take great care to ensure that they use the correct MIC code for the relevant contract at the right time. For quick reference table detailing the precise changes to the appropriate MIC and the respective dates this was applied please refer to the below table which contains the full details.

    LIFEE Contract Migration to ICE Futures Europe

    [supsystic-tables id=’7′]

    BClear

    Firms should also note, that going forward, trading previously undertaken utilising LIFFE BClear for wholesale market activity, will now be undertaken under ICE “block” trading rules. When reporting as per the above table, firms should consider the product sector and contract type and report the appropriate MIC ongoing from it’s respective migration date. Dependent upon the security, this trading activity will be subject to MiFID and/or EMIR reporting requirements. Firms are advised when reporting this activity that they are required to report the appropriate MIC in recognition of the particular security.

    See below for further clarification.

    • “Block” trade on an Equity Index Future the appropriate MIC is IFLL
    • “Block” trade on an Equity Index Option the appropriate MIC is IFLO
    • “BlocK” trade on White Sugar Futures and Options the appropriate MIC is IFLX

    Firms should refer to the “LIFFE to ICE Futures Europe Transition Notice” published September 2014 for further details of the migration impact.