Author: louie.aldworth

  • How to navigate UK and EU EMIR Refit reporting changes

    How to navigate UK and EU EMIR Refit reporting changes

    EMIR Refit introduces wholesale change at a granular level for EMIR reporting. Firms must be compliant with the new standards from 29 April 2024 in the EU and 30 September 2024 in the UK. Each of these implementations is a large lift, and a headache for all firms concerned.

    Even the lucky firms with just a single UK obligation will need to source regulation from a whole new set of documents and sources. With this comes inefficiency in navigating the material, as well as potential divergence created in the final drafting.

    The main potential source of divergence is in the reporting guidelines themselves. The EU document was published in December 2022 and is currently being digested by firms. We expect the FCA to publish a series of smaller guideline articles for the UK, in contrast to the sizeable Reporting Guidelines published by ESMA in December 2022.  The FCA will use feedback from its industry engagement working groups to help steer the topics and direction of the aforementioned guideline articles.

    Many of those who work within transaction reporting in the UK will only have worked with EU documentation up until this point. Due to the different approaches of publishing documentation between the EU and UK regulators, it can leave compliance and reporting teams asking questions such as “where are the field requirements for the UK?”, “where are the requirements in the FCA handbook?” or, even “how does the UK differ from the EU”?

    The Single Rulebook platform hosts the latest UK and EU EMIR Refit rules, guidance and related documentation. Its intelligent literal and semantic search functionality means that the relevant UK and EU EMIR Refit rules can be located in seconds with the functionality to also find the corresponding UK or EU rule at the same time.

    What are the key changes of EMIR Refit?

    The new regulation will standardise messaging on the ISO 20022 format, implement UPI for more robust product identification, clarify the UTI generation waterfall and crucially, increase the number of reportable fields to 204 in the UK and 203 in the EU.

    How will the UK publish rules for UK EMIR Reporting?

    UK EMIR reporting falls under the FCA’s remit and all new rulemaking is published via policy statements and legal instruments. The following publications relate to UK EMIR Refit:

    • PS23/2 – Changes to reporting requirements, procedures for data quality and registration of Trade Repositories under UK EMIR
    • FCA 2023/3 – EMIR Rules (Procedures for Ensuring Data Quality) Instrument 2023
    • FCA 2023/4 – FCA Standards Instrument: The Technical Standards (EMIR Reporting and Data Quality and Miscellaneous Amendments) Instrument 2023
    • FCA 2023/5 – Technical Standards (EMIR Registration of Trade Repositories and Miscellaneous Amendments) Instrument 2023

    Where are these rules available in the FCA Handbook?

    These rules are not currently available in the FCA Handbook; they will only be published when they enter into force. For the interim period, these PDFs are the only published versions of the new requirements. When published, the main guidance will appear in two places.

    • EMIRR will be published as a new “Specialist Sourcebook”. This contains rules applicable to trade repositories.      
    • Two new FCA Technical Standards will be created:
      • Technical Standards on the Standards, Formats, Frequency and Methods and Arrangements for Reporting
      • Technical Standards on the Minimum Details of the Data to be Reported to Trade Repositories  

    There are also a number of less substantive amendments that will be made to the FCA Handbook, for example adding definitions to the glossary.

    Finally, FCA 2023/4 and FCA 2023 make changes to other “onshored” FCA technical standards. The complete extract is as below.

    Legal Instrument

    Change

    Comment

    FCA 2023/3

    The Glossary of definitions is amended in accordance with the Annex A to this Instrument.

    Add EMIRR definition

    FCA 2023/3


    The General Provisions sourcebook (GEN) is amended in accordance with the Annex B to this instrument.

    Legal administrative update

    FCA 2023/4


    The FCA revokes the following technical standards insofar as they apply in all cases, except in the case of central counterparties:

    (1) Commission Implementing Regulation (EU) No 1247/2012

    and,

    (2) Commission Delegated Regulation (EU) No 148/2013 of 19 December 2012 supplementing Regulation (EU) No 648/2012.

    Partial disapplication of previous rules


    The FCA amends the following technical standards in accordance with the relevant Annexes to this instrument:

    ●       Commission Delegated Regulation (EU) No 149/2013 of 19 December 2012 supplementing Regulation (EU) No 648/2012

    ●       Commission Delegated Regulation (EU) No 151/2013 of 19 December 2012 supplementing Regulation (EU) No 648/2012

    ●       Commission Delegated Regulation (EU) No 2016/957 of 9 March 2016 supplementing Regulation (EU) No 596/2014

    Administrative updates to document references and updates to ensure consistency of field names and action types.

    FCA 2023/5

    The following technical standards are amended in accordance with the Annexes to this instrument.

    ●       Commission Delegated Regulation (EU) No 150/2013 of 19 December 2012 supplementing Regulation (EU) No 648/2012

    ●       Commission Implementing Regulation (EU) No 1248/2012

    ●       Commission Delegated Regulation (EU) No 151/2013 of 19 December 2012 supplementing Regulation (EU) No 648/2012

    Administrative updates to document references and updates to operational risk and control requirements for trade repositories.


    To date, changes to onshored RTS and ITS have not been made available in consolidated form by the UK Government. As a result, firms will need to establish other ways of navigating and retaining control over this type of change.

    You can now find these documents on the FCA’s website by setting a future date and navigating through the folders.

    The EMIRR specialist sourcebook can be found here by opening the Specialist Sourcebooks folder.

    The new technical standards can be found here by opening the European Markets Infrastructure Regulation > 2023 folder.

    Mapping UK to EU rules

    As the rules were drafted within similar timeframes, we can build a map of the rules in the UK with the corresponding EU rules. This helps firms ensure that their reporting is aligned from day one. Firms will also need to monitor and manage the impact of future divergence between these requirements.

    Document

    UK

    EU

    TR Validations and inter-TR reconciliation

    FCA 2023/3

    Annex C

    (EMIRR Sourcebook)

    RTS 2022/1858

    Minimum Details of the Data to be Reported to Trade Repositories

    FCA 2023/4

    Annex A

    RTS 2022/1855

    Standards, Formats, Frequency and Methods and Arrangements for Reporting

    FCA 2023/4

    Annex B

    ITS 2022/1860


    In order to demonstrate control and compliance in both jurisdictions, it is also important to map the rules at a more granular level which the Rule Maps functionality in the Single Rulebook platform can provide. 

    Other Content that You Will Need

    The rules themselves are not enough to complete the migration. The full suite of ancillary regulatory documents is below. Firms will also need to refer to the documentation published by their chosen repository and follow their precise instructions.

    Document

    UK

    EU

    Guidelines


    EMIR Refit Reporting Guidelines

    Validation Rules

    UK EMIR Validations

    EU EMIR Validations*

    xml Schemas

    Incoming Messages

    Outgoing Messages

    Incoming Messages*

    Outgoing Messages*

    Mapping Table


    Mapping table

    Breach Notification

    UK European Market Infrastructure Regulation (UK EMIR) – reporting errors and omissions notification form (fca.org.uk)

    Contained within EU EMIR Validations

    * Please note that the EU Validations, Incoming Messages and Outgoing Messages were updated by ESMA on 6th September 2023 but the version number of each zip file remains 1.0.0.


    Conclusion

    Implementing the EMIR Refit transaction reporting changes will require close attention to the fine detail of the changes between EU and UK jurisdictions. Subject matter expertise will again be in short supply and firms will need to plan their project well to decrease the risk of reporting errors and non-compliance.

    Kaizen’s EMIR Refit Toolkit provides support at every stage of your project:

    1. Validations – Firms can test the validity of their submission files to ensure that reports meet the validation rules as defined by the regulator.
    2. Accuracy on Demand –  A new service, ‘Accuracy on Demand’ utilises Kaizen’s award-winning testing methodology to check whether your TR submissions are not only valid but accurate.
    3. Accuracy Testing – Kaizen’s flagship product is the gold standard in regulatory assurance, delivering a complete set of testing, down to every field of every record, tailored to your business.
    4. Single Rulebook – in addition to providing the regulatory content, Single Rulebook’s online platform also provides visual rule maps, traceability and annotation tools for EMIR Refit that can help firms manage the regulatory change brought about by the revised regulation.
    5. EMIR Refit Core Training – Training is an integral part of the systems and controls required for accurate reporting. Our interactive half-day course provides a comprehensive understanding of the EMIR Refit reporting requirements.
    • For a conversation with Chris Dingley on how to navigate your EMIR Refit reporting changes, contact us.
  • UPI – Unique Product Identifier Explained

    UPI – Unique Product Identifier Explained

    The Unique Product Identifier (UPI) is the long-awaited new taxonomy for better describing OTC derivative products and the various characteristics of how each derivative is structured.

    At its simplest level the UPI replaces the current simplistic OTC derivative taxonomy values such as “FX Forward” or ISDA’s “ForeignExchange:Forward” with an identifier mapped to far more granular attributes in a centralised database.

    That database is run by ANNA-DSB and much like ISIN codes, will mean that various parties can be sure they are talking about the same OTC derivative because they can look up that UPI in the database and all see the same attributes.

    ROCking out with ANNA

    Alphabetti spaghetti time for the acronyms.

    The ROC gave the mandate to ANNA to establish and run the DSB for UPI.

    Clear?

    No?

    Ok. The Regulatory Oversight Committee (a supranational group of financial market regulators and authorities that amongst other duties oversees the LEI framework) is leading the global rollout of UPI. As well as helping to establish the UPI protocols and taxonomy, the ROC has mandated the Association of National Numbering Agencies (ANNA) with establishing and operating a facility for obtaining and maintaining UPIs. This facility is called the Derivatives Service Bureau (DSB) and is essentially a paid-for service where users can obtain an existing UPI if one already exists or have a new UPI generated if it doesn’t. Think of it as a big centralised Excel spreadsheet that debits your credit card every time you glance in its direction.

    Taxonomies? Attributes? What?

    This stuff is admittedly hard to visualise so let’s break it down with examples.

    Let’s take good old Credit Default Swaps (CDS). Because had they not crashed the world’s economy in 2008 we wouldn’t be here today discussing UPI as part of the remedy for that misadventure.

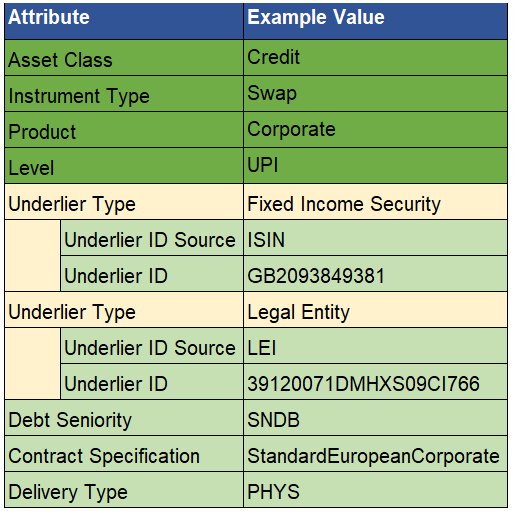
    A firm has a CDS in its systems with various product attributes that describe things like what the underlying asset the CDS is based on and it wants to obtain the UPI for that CDS.

    The firm submits a query to ANNA-DSB with various inputs describing the CDS.

    The UPI query inputs for a CDS on a corporate bond are shown below:


    ANNA-DSB searches the UPI database to see if a UPI already exists for a CDS matching these various inputs. If no UPI exists, the DSB will assign a new UPI and create a new record in the database for subsequent users to see.

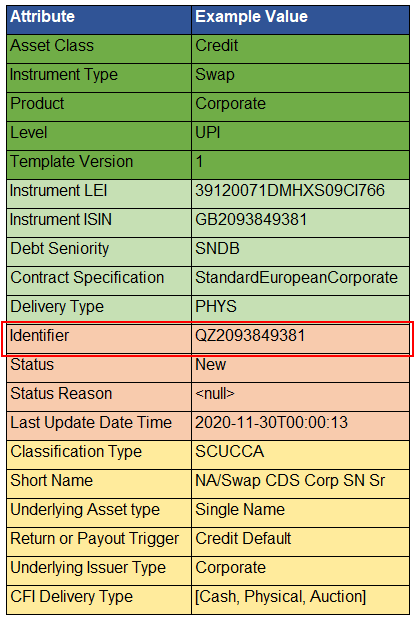
    The DSB then responds to the query with the resulting UPI (highlighted) and additional characteristics as shown below.


    Now whenever the firm communicates with another firm, regulator or party they can all use DSB data to know that UPI QZ2093849381 refers to a Credit Default Swap on a European corporate bond with ISIN GB2093849381, with CFI code SCUCCA and issued by LEI 39120071DMHXS09CI766.

    So similarly to the LEI where the database maintained by GLEIF means that firms can use an LEI code to ensure that they are talking about the exact same legal entity, the rationale behind UPI is that a central database of products provides clarity that firms are talking about the exact same OTC derivative product.

    FX Example

    The UPI query inputs and outputs vary based on the asset class and product type.

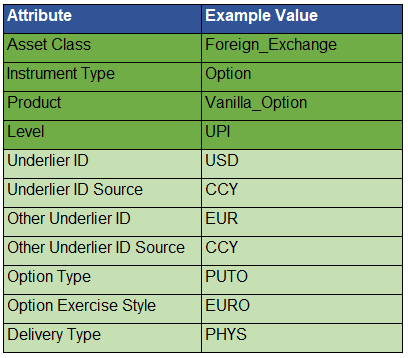
    If we consider Foreign Exchange then, if a firm has an FX Option in its systems and it wants to obtain the UPI for that FX Option.

    The firm submits the below query to ANNA-DSB with various inputs describing the various characteristics of the FX Option.


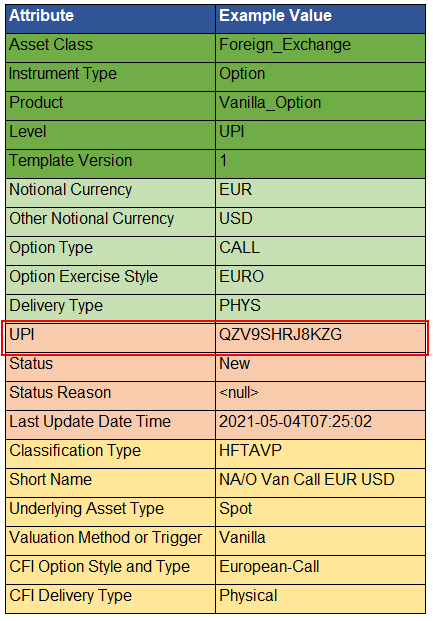
    DSB then responds to the query with the resulting UPI (highlighted) and additional characteristics as shown below.


    Now all parties can use DSB data to know that UPI QZV9SHRJ8KZG refers to an FX Option on a EUR vs USD, with CFI code HFTAVP, that’s a European-style physically settled call option.

    Interest Rates Example

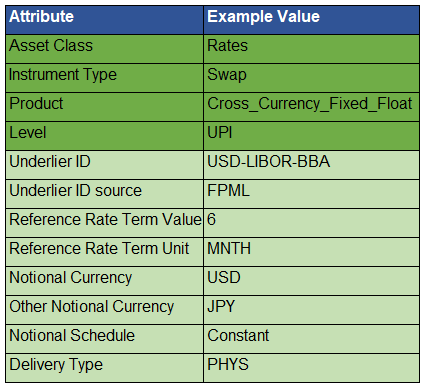
    Next if we look at interest rates, if a firm has a cross-currency fixed-float swap and it wants to obtain the UPI for that swap.

    The firm submits the below query to ANNA-DSB describing the rates swap.


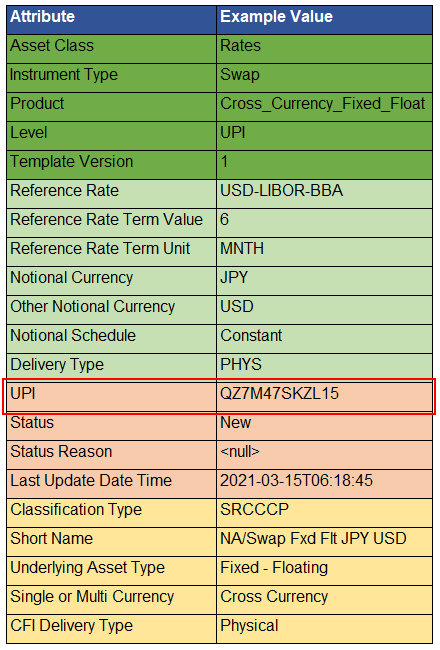
    DSB then responds to the query with the resulting UPI (highlighted) and additional characteristics as shown below.


    Now all parties can use DSB data to know that UPI QZ7M47SKZL15 refers to an cross-currency fixed-float swap on USD vs JPY, with CFI code SRCCCP that’s physically settled.

    So UPI is like an ISIN then?

    UPI essentially sits between a CFI code and an ISIN in terms of how granular or specific it gets.

    The CFI code describes the basic attributes but does not get as far as underlying assets, currencies etc.

    Taking the CFI from the previous rates example, we see that SRCCCP is the CFI code for a physically settled, cross-currency, fixed-floating, rates swap.

    Diagram below generated using ISDA’s CFI Code Generator:


    The UPI takes it to the next level of granularity by telling us this rates swap is also based on USD vs JPY, uses the USD-LIBOR-BBA floating rate and has a six-month period for that reference rate. So the UPI is far more specific than the CFI which just outlines the broad characteristics.

    ISIN would take it even further in terms of granularity because ISIN also tends to reference the trading venue where it traded and any venue specific characteristics such as the currency it’s traded/priced in.

    Why not just use ISIN?

    Two main reasons…

    1. The more forgiving reason is that since ISINs are often specific to the trading venues this means that using ISINs makes it more difficult to aggregate products with the same characteristics that are traded on different venues. Given the whole OTC derivative reporting framework is geared towards systemic risk, the regulators want the ability to aggregate transactions at product level, rather than venue level, when examining counterparty exposure. So UPI being venue agnostic is beneficial for this surveillance.
    2. The less forgiving answer is that outside of EMIR (EU & UK versions) no other regulators use ISINs for OTC derivatives. EU and UK reporting is therefore the outlier and much like the reporting of Exchange Traded Derivatives (ETDs) that underpins it, the use of ISINs for OTC was widely considered crazy but nonetheless made it into the rulebooks.

    So whilst ESMA and the FCA pushed ahead with ISINs for OTC derivatives the remainder of the regulators globally have patiently waited for UPI to be ready as a global solution much like the LEI.

    UPI Pay to Play

    Unlike LEIs (where the legal entity obtaining an LEI has to pay an annual fee for that LEI but the database and data is essentially free to all), ANNA-DSB will charge users for creating UPIs and accessing the UPI data in general. This is a little more controversial as UPI’s adoption across many of the OTC derivative reporting regimes amongst other use-cases means that many firms will have no alternative other to register with ANNA-DSB and pay for the privilege.

    Time will tell whether other cottage industries and resources pop up around UPI data in much the same way as you see a plethora of LEI websites and utilities whenever you search for an LEI these days. I personally hope so because ANNA-DSB needs remuneration for creating and maintaining the UPI services, that much is reasonable. But everyone having to repeatedly pay to access the same data seems a lot less reasonable in the long run.

    Similarly to the LEI rollout, we’d expect an explosion of new UPIs at the start (when the CFTC goes live with UPI in January) and another explosion when EMIR Refit follows in April next year. But that growth in new UPI population will theoretically tail off and eventually slow right down where only exotic edge-case UPIs are requested, or UPIs on newly created credit or equity underlying instruments.

    Conclusion – The Big Short rerun

    The UPI is a good concept in general and, after what seems like a very long time in the making, it is finally becoming a reality. It should help to improve clarity and consistency across the industry and for regulatory reporting in general. However we see a great deal of confusion around what UPI really means and with six months to go until the CFTC UPI go live, this is concerning. 

    If the UPI allows various regulators to aggregate similar derivative contracts together to better assess the systemic risk then that can only be a good thing. I’ll happily watch the excellent The Big Short film again but I don’t need to relive the crisis itself. There is clearly a great deal of work ahead to get UPI up and running and fully integrated across many firms and many systems.

    Tables (apart from ISDA’s) sourced from ANNA-DSB.

    • Still scratching your head over UPI?  For a conversation with Alan or one of our regulatory specialists, please get in touch. 
    • Is your firm prepared for EMIR Refit? To find out more about our EMIR Refit Toolkit, please contact us.
  • WATCH: Why Shareholding Disclosures matter to your firm

    WATCH: Why Shareholding Disclosures matter to your firm

    Kaizen’s Regulatory Advisory Director Angie Huff and aosphere’s Fiona O’Shea are joined by BlackRock’s Samantha Withers to cover the complexities of shareholding disclosure and what you need to be doing to comply with the latest rules and regulations.

    Topics they cover include:

    • What are shareholding disclosures?
    • If I am a UK company do rules in other jurisdictions apply to me?
    • Why are these rules so complex?
    • If we have multiple legal entities do we disclose each position separately?
    • What are the sanctions if we do not comply?
    • Has Brexit changed the UK regime? What do I need to do?